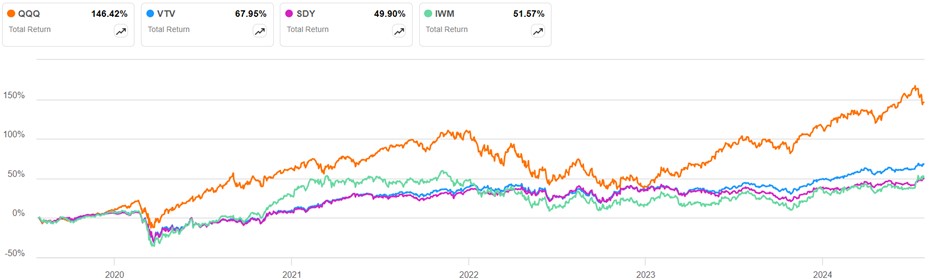
Tech stocks have been unstoppable for the past fifteen or so years. Here is a chart from Seeking Alpha for total return of the tech-heavy QQQ fund (orange line) over the past five years, compared to a value-oriented stock fund (VTV), a fund focused on dividend-paying stocks (SDY) and the Russel 2000 small cap fund IWM.
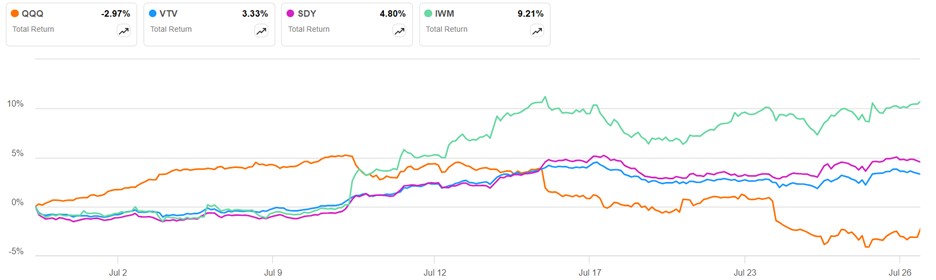
QQQ has left the others in the dust. There has been a reversal, however, in the past month. The tech stocks have sagged nearly 10% since July 11, while the left-for-dead small caps (IWM, green line) rose by 10%:
Some of this is just mean reversion, but there seems to be a deeper narrative shift going on. For the past 18 months, practically anything that could remotely be connected with AI, especially the Large Language Models (LLM) exemplified by ChatGPT, has been valued as though it would necessarily make every-growing gobs of money, for years to come.
In recent weeks, however, Wall Street analysts have started to question whether all that AI spending will pay off as expected. Here are some headlines and excerpts (some of the linked articles are behind paywalls):
““There are growing concerns that the return on investment from heavy AI spending is further out or not as lucrative as believed, and that is rippling through the whole semiconductor chain and all AI-related stocks,” said James Abate, chief investment officer at Centre Asset Management.”
““The overarching concern is, where is the ROI on all the AI infrastructure spending?” said Alec Young, chief investment strategist at Mapsignals. “There’s a pretty insane amount of money being spent. Jim Covello, the head of equity research at Goldman Sachs Group Inc., is among a growing number of market professionals who are arguing that the commercial hopes for AI are overblown and questioning the vast expense required to build out infrastructure required for the computing to run and train large-language models.”
“It really feels like we are moving from a ‘tell me’ story on AI to a ‘show me’ story,” said Ohsung Kwon, equity and quantitative strategist at Bank of America Corp. “We are basically at a point where we’re not seeing much evidence of AI monetization yet.”
Google stock got dinged last week for excessive capital spending, even though earnings were strong. Microsoft reports its Q4 earnings after the market closes today (Tuesday); we will see how investors parse these results.
Two weeks ago we described a simple way to achieve roughly double investing returns on some asset class like an S&P 500 stock basket, or on some commodity like gold or oil, by buying shares in an exchange-traded fund (ETF) whose price moves up or down each day two times as much as the price of the underlying stocks or commodities. For instance, if the S&P 500 stocks go up (or down) by 2% on a given day, the price of the SSO ETF will move up (or down) by 4%. And last week we noted that buying deep in the money call options can also result in an investment which can move up or down by twice the percentage of the underlying stock. These call options side-step the volatility drag implicit in the 2X funds, but require some housekeeping on the investors part to roll them over once or twice a year.
Today we present a third approach for multiplying the return on your investment dollars. This is to buy shares of a fund which holds two different asset classes, in a leveraged form. As an example: if you buy $100 worth of the fund PSLDX, you are buying the equivalent of $100 worth of S&P 500 stocks PLUS about $100 worth of long-dated US Treasury bonds. (PSLDX happens to be an old-fashioned mutual fund, not an ETF, but no matter). It works like this: The fund takes your $100 and buys a bucket of bonds. It then uses those bonds as collateral, and uses futures to get around $100 worth of exposure to the price movements of the S&P 500 stocks. There is not quite a free lunch here, since there is a “carry” cost on the futures, which is about equal to the LIBOR/SOFR short term interest rates (currently ~ 5%).
PSLDX does not promise exactly 100/100 stock/bond exposure, but it comes out pretty close much of the time. A similar product is NTSX which is leveraged x1.5. It gives 90/60 stocks/mixed-term bonds. NTSX has outperformed PLSDX in recent years, since the price of long-term (10-20 year) bonds has been crushed due to the rise in interest rates. RSSB is a recent entry into this space, offering 100/100 exposure to global stocks/laddered Treasuries.
Another reason these leveraged stock/bond products have done relatively poorly in the past two years is that the cost of leverage is actually higher than the bond coupons, due to the inverted yield curve. This problem will go away if the Fed lowers short-term rates back down to near zero, as they were prior to 2022, but lingering inflation makes that prospect unlikely.
That said, if I have $200 to invest and want $100 stock and $100 bond coverage, I can put $100 into one of these 100/100 funds, and still have $100 left to collect interest on or to invest in some other, hopefully higher-yielding venue. So, these stock/bond funds have their place.
Where this so-called asset stacking shines even more is combining stocks or bonds with something like managed futures. Managed futures are an excellent diversifier for equities (see here). Moreover, since managed futures are typically held in both long and short positions, there will be less financing (carry) cost associated with them. When both stocks and bonds cratered in 2022, managed futures went up. Thus, funds like BLNDX (50 global stocks/100 managed futures) and MAFIX (stocks plus managed futures) went up in 2022, and then continued to rise as stocks recovered. Thus, the returns for these two funds have been steadier and higher than plain stocks (SP 500) over the past three years:
Total returns for past three years, for BLNDX (50 stocks/100 managed futures), SP500 stocks, BND broad US bonds, and MAFIX stacked multi-asset.
BLNDX and its sister fund REMIX are readily available at most brokerages (I hold some), while MAFIX may have daunting minimum investment requirements. RSST is a recent 100/100 stock/managed futures ETF that is easily invested in, and seems to be performing well.
Disclaimer: As usual, nothing here should be considered advice to buy or sell any investment.
Last week we described a simple way to achieve roughly double investing returns on some asset class like an S&P 500 stock basket, or a narrow class of stocks such as semiconductors, or on some commodity like gold or oil. That way is to buy one of the many exchange-traded funds (ETFs) which use sophisticated derivatives to achieve a 2X or even 3X daily movement in their share prices, relative to the underlying asset. For instance, if the S&P 500 stocks move up by 2% on a given day, the SSO ETF will rise by 4%.
Of course, these leveraged funds will also go down two or three times as much. They also have a more subtle disadvantage, which is that when the markets go up and down a lot, they tend to lose value due to their daily reset mechanism.
In this post we describe a different way to achieve roughly double returns, which does not suffer from this volatility drag issue. This way is to buy long-dated deep in-the-money call options on a stock or a fund.
Say what? We have described how stock options work here and here. The reader who is unfamiliar with options should consult those prior articles.
A stock option is a contract to buy (if it is a call option) or to sell (if it is a put option) a given stock at some particular price (“strike price”), by some particular expiration date. Investors generally buy calls when they believe that the price of some stock or fund will go up. For a call option with a strike price far below the current market price of a stock, the market price of the option will move up and down essentially 1:1 with the market price of the stock.
For instance, as I write this the market price of Apple is about $230. Suppose I think Apple is going to go up by say $40 in the next six months. One way for me to capture this gain is to invest $230 in buying Apple stock. The alternative propose here is to instead of buying the stock itself, buy, say, a call option with a strike price of $115 and an expiration date of January 17, 2025. The current market price of this option is about $119.
Other things being equal, we expect that the market value of this call option will go up by $40 if Apple itself goes up by $40. But we have invested only $119, rather than $230, so our return on our investment is roughly double with the option than by buying the stock itself.
There is a subtle cost to this approach. At a stock price of $230 and a strike price of $115, the intrinsic value of this call option is $115. But we pay an extra $3 of extrinsic value when we buy the option for $118. This extrinsic value will gradually decay to zero over the next six months.
Thus, if Apple went up by $40 within the next month or so, we could turn around and sell this call option for nearly $40 more than our purchase price. But if we wait for six months before selling it, we would only net $37 (i.e., $40 minus $3). This is still fine, but it illustrates that there is a steady cost of holding such options. This annualized cost is about equal to or slightly higher than the prevailing short term interest rate (5% /year). This option pricing makes sense, since an alternative way to control this many shares would be to borrow money at current interest rates (5%) and use those borrowed funds to buy Apple shares. Options and futures pricing is generally rational, to make things like this equivalent, or else there would be easy arbitrage profits available.
As a side comment, the reason I am focusing on deep in the money calls here is that the extrinsic premium you pay in buying the call gets lower the further away the strike price is (i.e. deeper in the money) from the current stock price. A deeper in the money call does cost you more up front, but net net its dollar movements up and down more closely track (1:1) the movements of the underlying stock. So, if I am not trying to guess right on any market timing, but simply want to get the equivalent of holding the underlying stock but tying up less money to do so, I find buying a call that is about 50% in the money generally works well.
How I Use Deep in the Money Call Options
I consider the technology-oriented stock fund QQQ to be a core holding in my portfolio, so I would like to stay exposed to its movements. But I might as well do this on a 2X basis, to make better use of my funds. I do hold some of the 2X ETF QLD. But if we experience a lot of market volatility, the price of QLD will suffer, as explained in our previous post.
As a more conservative approach here, I recently bought a deep in the money call on the QQQ ETF. As usual, I went for a call option with a strike price roughly half of the market price, with an expiration date 6-12 months away. When this gets close to expiration (May-June next year), I will “roll” it forward, by selling my existing call option, and buying a new one dated yet another 6-12 months further out. This takes little work and little decision making. I will pay the equivalent of about 5% annualized cost on the decay of the extrinsic option premium, but I come ahead as long as QQQ goes up more than 5% per year.
This is a little more work than just holding the 2X QLD ETF, but it gives me a bit more peace of mind, knowing I have done what I can to smooth out some of the risk there. Of course, if QQQ plunges along with the markets in general, I will be looking at double the losses. For that reason, I am taking some of the money I am saving by using these leveraged approaches, and stashing it in safe money market funds. In theory that should give me “dry powder” for buying more stocks after they drop. In practice, I may be too frozen with fear to make such clever purchases. But at any rate, I should not be appreciably worse off for having used these leveraged investments (2X funds or deep in the money calls).
Disclaimer: As usual, nothing here should be considered advice to buy or sell any investment.
Most years, stocks go up, by something like 9%. Wouldn’t it be nice to invest in a fund that went up double those amounts? Such funds exist. They use futures or other derivatives to move up (or down!) by double, or even triple, the percentage that the underlying stock or index moves, on a daily basis.
For instance, a common unleveraged fund (ETF) is SPY that roughly tracks the S&P 500 index of large U.S. stocks is SPY. SSO is a 2X fund, which gives double the returns of SPY, on a daily basis. UPRO is a 3X fund, giving triple the returns. 2X funds exist for many different asset classes, including semiconductor stocks, treasury bill, and crude oil – see here. And similarly for 3X funds.
Since all the action in stocks these days seems to be in large tech companies, I will focus on the NASDAQ 100 index universe. The leading unleveraged fund there is QQQ. The 2X version is QLD, and the 3X is TQQQ. Let’s look at how these three funds performed over the past twelve months:
QQQ is up a respectable 36%, but QLD is up by 70%, and TQQQ by a mouth-watering 106%. You could have doubled your money in the past twelve months simply by investing in a 3X fund instead of holding boring 1X QQQ.
These leveraged funds can be utilized in more than one way. One approach is to just put the monies you have allocated for stocks into such funds, and hope for higher returns. Another approach is to put, say half of your speculative funds into a 2X fund (to get roughly the same stock exposure as putting all of it into a 1X fund), and then use the remaining half to put into other investments, or to keep as dry powder to give you the option to buy more equities if the market crashes.
What’s not to like about these funds? It turns out that a year of daily doubling of returns does not necessarily add up to doubling of yearly returns. There is “volatility drag” associated with all the exaggerated moves up and down. As an illustration of how this works, suppose you held a stock that went down by 50% one day, say from a price of $100 to $50. The next day, it went back up by 50%. But this would only get you back to $75, not $100.
It turns out that with these leveraged funds, as long as stocks are generally going up, the yearly returns can match or even exceed the 2X or 3X targets. But in a period with a lot of volatility, the yearly returns can fall far short. And in a down year, the combination of the leverage and the volatility drag lead to truly horrific losses. For instance, here is what 2022 looked like for these funds:
QQQ was down by 31%, which is bad enough. But imagine your $10,000 in TQQQ melting down to $3,300 that year.
And here is the chart from January 2022 to the present:
QQQ is up 27% in the past 2.5 years, 2X QLD is up only 16%, while 3X TQQQ is actually down by 6%, as it could not recovery from 2022.
This was a kind of a worst-case scenario, since 2022 was an exceptionally bad year for QQQ, coming off a fabulous 2021. A chart of the past five years, which includes the 2020 Covid crash and recovery, and the 2022 crash and subsequent recovery still shows the leveraged funds coming out ahead over the long term:
The net returns on QLD (321%) were about double QQQ (158%), while the more volatile TQQQ return (386%) was plenty high, but fell well short of three times QQQ.
In my personal investing, I hold some QLD as a means to free up funds for other investments I like. But if I smell major market trouble coming, I plan to swap back into plain QQQ until the storm clouds pass.
There are some other ways to get roughly double returns, which suffer less from volatility drag than these 2X funds. I will address those in subsequent posts.
Disclaimer: As usual, nothing here should be considered advice to buy or sell any investment.
Folks who follow the stock market know that the average company in the S&P 500 has gone essentially nowhere in the last couple of years. What has pulled the averages higher and higher has been the outstanding performance of a handful of big tech stocks. Foremost among these is Nvidia. Its share price has tripled in the past year, after nearly tripling in the previously twelve months. Its market value climbed to $3.3 trillion last week, briefly surpassing tech behemoths Microsoft and Apple as the most valuable company in the world.
What just happened here?
It all began in 1993 when Taiwanese-American electrical engineer Jensen Huang and two other Silicon Valley techies met in a Denny’s in East San Jose and decided to start their own company. Their focus was making graphics acceleration boards for video games. Computing devices such as computers, game stations, and smart phones have at their core a central processing unit, CPU. A strength of CPUs is their versatility. They can do a lot of different tasks, but sequentially and thus at a limited speed. To oversimplify, a CPU fetches an instruction (command), and then loads maybe two chunks of data, then performs the instructed calculations on those data, and then stores the result somewhere else, and then turns around and fetches the next instruction. With clever programming, some tasks can be broken up into multiple pieces that can be processed in parallel on several CPU cores at once, but that only goes so far.
Processing large amounts of graphics data, such as rendering a high-resolution active video game, requires an enormous amount of computing. However, these calculations are largely all the same type, so a versatile processing chip like a CPU is not required. Graphics processing units (GPUs), originally termed graphics accelerators, are designed to do enormous number of these simple calculations simultaneously. To offload the burden on the CPU, computers and game stations for decades have included on auxiliary GPU (“graphics card”) alongside the CPU.
This was the original target for Nvidia. Video gaming was expanding rapidly, and they saw a niche for innovative graphics processors. Unfortunately, they the processing architecture they choose to work on fell out of favor, and they skated right up to the edge of going bankrupt. In 1993 Nvidia was down to 30 days before closing their doors, but at the last moment they got a $5 million loan to keep them afloat. Nvidia clawed its way back from the brink and managed to make and sell a series of popular graphics processors.
However, management had a vision that the massively parallel processing power of their chips could be applied to more exulted uses than rendering blood spatters in Call of Duty. The types of matrix calculations done in GPUs can be used in a wide variety of physical simulations such as seismology and molecular dynamics. In 2007, and video released its CUDA platform for using GPUs for accelerated general purpose processing. Since then, Nvidia has promoting the use of its GPUs as general hardware for scientific computing, in addition to the classic graphics applications.
This line of business exploded starting around 2019, with the bitcoin craze. Crypto currencies require enormous amount of computing power, and these types of calculations are amenable to being performed in massively parallel GPUs. Serious bitcoin mining companies set up racks of processors, built on NVIDIA GPUs. GPUs did have serious competition from other types of processors for the crypto mining applications, so they did not have the field to themselves. With people stuck at home in 2020-2021, demand for GPUs rose even further: more folks sitting on couches playing video games, and more cloud computing for remote work.
Nvidia Dominates AI Computing
Now the whole world cannot get enough of machine learning and generative AI. And Nvidia chips totally dominate that market. Nvidia supplies not only the hardware (chips) but also a software platform to allow programmers to make use of the chips. With so many programmers and applications standardized now on the Nvidia platform, its dominance and profitability should persist for many years.
Nearly all their chips are manufactured in Taiwan, so that provides a geopolitical risk, not only for Nvidia but for all enterprises that depend on high end AI processing.
When I first started reading of “Lender-on-Lender Violence” this year, images of bankers in three-piece suits brawling in the streets of Lower Manhattan came to mind. It turns out that this is a staid legal term for a practice which has been around for some time, but is becoming more common and consequential.
Consider a case where say three lenders (e.g. banks or more likely venture capital funds) have lent money to some startup or struggling company XYZ. Let’s call these lenders A, B, and C. Now XYZ needs even more funding, perhaps because they need to build another factory, or perhaps because things are not working out as they hoped and they cannot pay off the original loans and still stay in business.
Now Lenders A and B get together and cook up a scheme. They will lend some more money to company XYZ to largely replace the original loan, but they contrive to get legal terms for that new loan that give it a higher priority for payment than the original loan. This is called “up-tiering” the new loan. This has the effect of reducing the market value of the original loan.
Lender C is now hosed. It faces murky prospects for repayment on that original loan. Lenders A and B offer to buy them out of the original loan for 40 cents on the dollar. Lender C proceeds to sue Lenders A and B.
Will Lender C prevail? Probably not, if the course of recent cases is any guide. Unless there is very specific language in the legal “covenant” regarding the first loan forbidding this practice, it seems to be legal.
A similar maneuver would be for a new Lender D to offer a replacement loan to Company XYZ, with legal language giving it priority over the original loan. This is called “priming.”
Yet another tactic by the aggressive lenders includes working with Company XYZ to move its more valuable assets into a subsidiary or shell company, and to get the new loan to hold that as collateral. This again hoses the “victim” lenders, since again the assurance that they will be repaid has gone down.
My Personal Experience with Lender-on-Lender Violence
Some years ago, I bought the bonds of a company called SeaDrill. I bought the bonds instead of the common or preferred stock, for an additional margin of safety. Unlike the stock, the bonds must be repaid in full, right? Both the bonds and the preferreds were paying about 9%, back when general interest rates were much lower than that are now. So, I was a lender to the company.
Silly me. Times got tough in the oil patch, and the company would have had difficulty paying off its bonds AND paying its management their high salaries. So, they went for Chapter 11 bankruptcy. I had not realized the difference between Chapter 7 bankruptcy, where the company shuts down and liquidates and pays off its creditors in pecking order, and Chapter 11, which is largely a chance for the company to put the losses on its creditors and to keep on operating.
As with the example above, some big institution offered to refinance things with new secured bonds that had priority ahead of the old bonds (which I held). In the end I got about 44 cents on the dollar for my bonds. I was not happy about that, but I did make out better than the hapless preferred stockholders, who got just a tiny crumb to make them go away. It was a learning experience. I did feel, well, violated.
Implications for the Burgeoning Private Credit Market
I will be writing more on the booming “private credit” market. Many of the loans in this space are “covenant-lite.” Back before say 2008, a large fraction of loans to business were through banks, who would insist on strong legal protection for their money. But in recent years, private equity funds have competed for this lending, allowing the borrowers to borrow on terms that give much less protection to the lenders. Cov-lite is now the norm.
Traditionally, loans (as distinct from bonds) to businesses have enjoyed decent recoveries (e.g., around 70%) in case of defaults, thanks to strong collateral backing the loans. But if we face any sort of prolonged recession and elevated defaults, the recoveries on all these loans will be far less than in the past. These are uncharted waters.
My old Honda Civic was a fairly small sedan. It had a 1.8 liter engine, that generated about 140 horsepower. It would not win any drag races, but had functional acceleration.
I recently got a Honda CR-V, a much larger, heavier vehicle. I was nonplussed to learn that it only had a 1.5 liter engine. Would I have to get out and push it up steep hills? As it turns out, this small engine can crank out some 190 horsepower. Given the size of this crossover SUV, this still does not make for a peppy drive, but at least I can actually pass another car as needed.
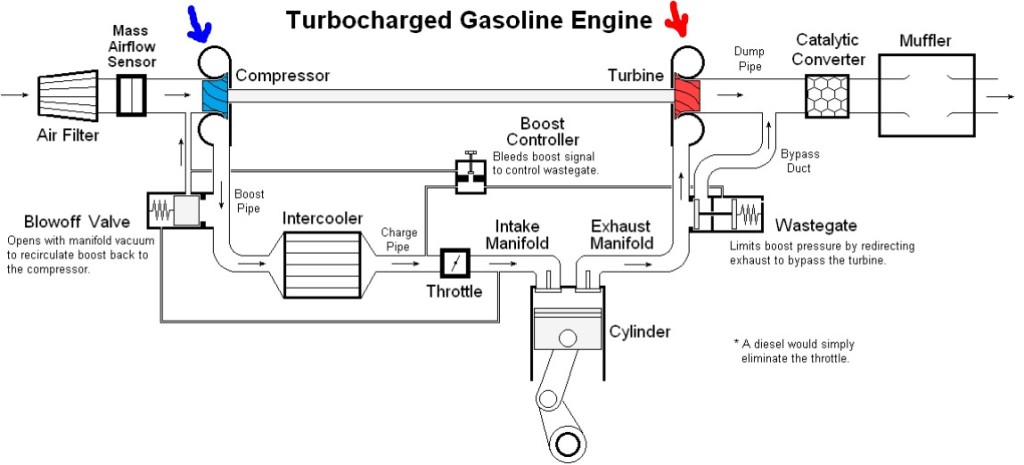
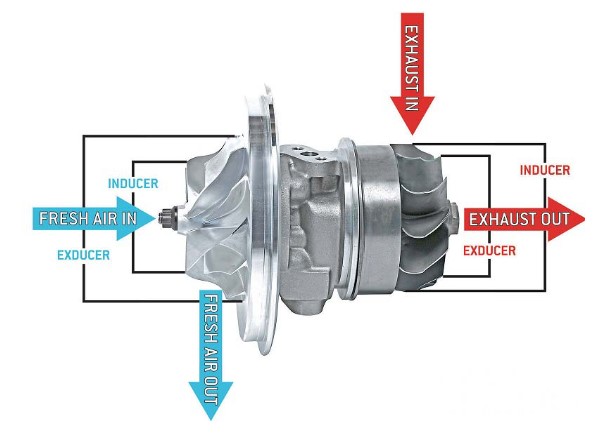
This high power with small engine displacement is made possible by the magic of turbocharging. As the (hot, expanded) exhaust gas leaves the engine, it goes through a turbine and makes it spin. A connected power shaft then spins a compressor, which takes outside air and jams it into the engine at higher pressure, i.e., higher density. With extra air stuffed into the engine cylinders, the engine can inject extra gasoline (keeping the air/fuel ratio roughly constant) – -and voila, high power output.
A schematic of this setup is shown below. I drew in a red arrow to mark the exhaust turbine, and a blue arrow for the intake air compressor. The rest should be fairly self-explanatory.
When the engine is turning at low-moderate speeds (say below 2000-3000 RPM), the turbine is doing relatively little, and so you are essentially driving around with a small (1.5 L) engine. This is good for gas mileage. When you floor it, the engine spins up and the turbo boost kicks in, giving considerably more power. [1]
What’s not to like? Apart from the potential maintenance headache of a rapidly spinning, complex chunk of precision machinery, there are a couple of issues with driving turbocharged engines that drivers should be aware of. There are articles and videos (see good comments there) that address these and other issues in some detail.
( A ) Time Lag Before Turbo Boost Kicks In
With a normal non-turbo engine, you can feel the power kick in nearly immediately when you depress the pedal. The pedal opens the throttle, and instantly the engine is gulping more air (and fuel).
With a turbo, there can be a detectible time lag. The engine must rev up until the turbo effect starts to kick in, and then it spins faster, and there is more air shoved into the engine. As long as you know this, you can drive accordingly. This might be a life and death matter if as you are in the middle of passing a car on a two-lane highway, and suddenly an oncoming car appears in your passing lane. If you are not up to full power by that point, such that you can complete the passing quickly, you could become a statistic. I have only faced that situation maybe once every ten years in my driving, but it should be figured in.
The actual time lag varies from one model to another. I’d suggest just testing this out on your car. In some safe driving scenario, floor it and assess how much of a lag there is.
( B ) Don’t turn the engine off immediately if it has been running fast.
The thought here is to let the engine slow down to idle, and maybe even cool down a hair, before turning it off. The reason is that if the engine is revving at say 2000 rpm, and you suddenly turn the engine off, the oil pumping action stops, but the turbo is still spinning away in there. Having the turbine spinning away with no oil circulation can wreck the bushings.
There are articles and videos (see good comments there) that address these and other issues in some detail.
Comment on Driving Honda CR-V Turbo Engine
Various engines have been used in CR-Vs. The 1.5 L turbo has been common in North America since 2017. It was designed to not have a very noticeable lag, in the sense that nothing happens for two seconds, and then the vehicle lurches forward. The turbo effect reportedly starts to kick in at 2000 rpm. However, this effect is progressive, so the power at 2000-3000 rpm is still modest. So, if you just push halfway down on the accelerator, the response is modest. If you floor it, the engine will within a second or two scream up to like 5000 rpm, and then start to really accelerate. That said, I have a visceral aversion to revving my engines that close to the red-line danger zone on the tachometer (my previous non-turbo cars I never took above about 3500 rpm, never needed to). Even with all that revving, the net acceleration is still modest.
Another factor with driving a CR-V is the “Econ” fuel-saving engine setting. When that is on, it seems to prevent the engine from revving over about 3500 rpm. So, if I plan to pass another car, or if I need power for some other reason, I need to remember to punch the leafy green Econ button to turn off this mode.
The bottom line is that I will think twice, maybe thrice, before passing another vehicle on a two-lane road in my CR-V.
ENDNOTE
[1] That is the theory anyway: great gas mileage most of the time, and bursts of power available for those rare times when you need it. The reality seems to be a little different. There may be reason to believe that turbocharged small engines give good idealized EPA test gas mileage numbers, but that in ordinary driving, the results are not so great. The turbo is never actually turned off, it just contributes more or less at various RPMs. The turbocharging forces the manufacturer to adjust the air/fuel mixture to be less efficient, in order to avoid knock. So, the manufacturer may be essentially manipulating things to look good on the EPA tests. A larger engine, where some of the cylinders are shut off when not under load, may be more efficient. See video.
Financial markets have sustained themselves for nearly two years now on the hope that within 1-2 quarters, the Fed will finally relent and start lowering interest rates. This hope gets dashed again and again by data showing stubbornly persistent high employment, high GDP growth, and high inflation, but the hope refuses to die.
Long-term interest rates had been falling nicely for the last month, based on expectations of rate cuts in the fall. Then came Friday’s jobs report, and, blam, up went 10-year rates again. The Bureau of Labor Statistics (BLS) published its “Establishment” survey of data gleaned from employers. Non-farm payrolls rose by US 272k. This was appreciably higher than the 180k consensus expectation.
The plot below indicates that this number fits into a trend of essentially steady, fairly high employment gains (suggesting ongoing inflationary pressures):
There are fundamental reasons to take the BLS Establishment figures with a grain of salt. They have a history of significant revisions some months after first publication. Also, BLS uses a “birth/death” model for small businesses, which can account for some 50% (!) of the job gains they report. [1]
Another factor is that all of the net “jobs” created in recent quarters are reported to be part-time. According to Bret Jensen at Seeking Alpha, “Part-time jobs rose 286,000 during the quarter, while full-time jobs fell by just over 600,000. This is a continuation of a concerning trend where over the past year, roughly 1.5 million part-time positions were created while approximately one million full-time jobs were lost. This difference is that the BLS survey does not account for people working two or three jobs, which are now at a record as many Americans have struggled to maintain their standard of living during the inflationary environment of the past couple of years.”
It seems, then, that this week’s huge “jobs added” figure is not to be taken as indicating that the economy is overheated. However, it is still warm enough that rate cuts will be postponed yet again. A different BLS survey (“Household”) showed unemployment creeping up from 4.0% to 4.1%, which again suggests a more or less steady and fairly robust employment picture.
As far as drivers of inflation, I would look especially at wage growth. That is fitfully slowing, but not nearly enough to get us to the Fed’s 2% annual inflation target. My sense is that ongoing enormous federal deficit spending will keep pumping money into the economy fast enough to keep inflation high. High inflation will prevent significant interest rate cuts, assuming the Fed remains responsible. The interest payments on the federal debt will balloon due to the high rates, leading to even more deficit spending. If we actually get an economic downturn, leading to job insecurity and a willingness of workers to accept slower wage growth in the private sector, the federal spending floodgates will open even wider.
This makes hard assets like gold look attractive, to hedge against inflating U.S. dollars. This is one reason China has been quietly selling off its dollar hoard, and buying gold instead.
[1] For more in-depth treatments of employment statistics, see posts by fellow blogger Jeremy Horpedahl, e.g. here.
The Red lobster restaurant chain has historically positioned itself in what was hopefully a sweet spot between slow, expensive, full-service restaurants, and cheaper fast-food establishments. With its economies of scale, the Red Lobster franchise could engage in national advertising and improved supply contracts, giving it an advantage over small family-owned local restaurants.
The firm has been struggling for a number of years, caught between the quasi-upscaling of many fast-food chains, and the rise of fast-casual competitors like Chipotle. Also, seafood is more expensive to procure compared to chicken and beef, and the pandemic made a long-lasting dent in their revenues. That said, Red Lobster has been viable business for decades.
However, the firm has been adversely affected by financial engineering by outside companies. General Mills spun off Red Lobster to a company called Darden Restaurants in 1995. In 2014 Darden sold Red Lobster to a private equity firm called Golden Gate Capital for $2.5 billion. Golden Gate promptly plundered Red Lobster by selling its real estate out from under it. Instead of owning their own land and buildings, now the restaurants had to pay rent to landlords. This put a permanent hurt on the restaurant chain’s profits. After this bit of financial engineering, the private equity firm in 2019 sold a 49% stake to a company called Thai Union. Thai Union bought out the rest of Red Lobster ownership from Golden Gate in 2020.
The Iron Fist from Outside
Thai Union is a huge seafood producer, which operates massive shrimp farms in Southeast Asia and sells a lot of shrimp to Red Lobster. Although Thai Union initially said they would not interfere in the operations of Red Lobster, that’s not how it panned out.
An article by CNN author Nathaniel Meyersohn details how Thai Union took effective control of red lobster management decisions by 2022. Given the restaurant chain’s poor financial performance, it’s understandable that Thai Union would want to shake things up, but unfortunately the hatchet men they brought in appeared to have done more harm than good. Numerous off the record conversations agreed that the outside CEO was unnecessarily rude as well as incompetent. Knowledgeable Red Lobster veterans were driven out, and morale plummeted. Per Meyersohn:
Thai Union’s damaging decisions drove the pioneering chain’s fall, according to 13 former Red Lobster executives and senior leaders in various areas of the business as well as analysts. All but two of the former Red Lobster employees spoke to CNN under the condition of anonymity because of either non-disclosure agreements with Thai Union; fear that speaking out would harm their careers; or because they don’t want to jeopardize deferred compensation from Red Lobster…
Former Red Lobster employees say that while the pandemic, inflation and rent costs impacted Red Lobster, Thai Union’s ineptitude was the pivotal factor in Red Lobster’s decline.
“It was miserable working there for the last year and a half I was there,” said Les Foreman, a West Coast division vice president who worked at Red Lobster for 20 years and was fired in 2022. “They didn’t have any idea about running a restaurant company in the United States.”
At Red Lobster headquarters, employees prided themselves on a fiercely loyal culture and low turnover. Some employees had been with the chain for 30 and 40 years. But as Thai Union installed executives at the chain, dozens of veteran Red Lobster leaders with deep knowledge of the brand and restaurant industry were fired or resigned in rapid succession. Red Lobster ended up having five CEOs in five years…
Former Red Lobster employees describe a toxic and demoralizing environment as Thai Union-appointed executives descended on headquarters and interim CEO Paul Kenny eventually took over the chain in 2022. Kenny, an Australian-born former CEO of Minor Food, one of Asia’s largest casual dining and quick-service restaurants, was part of the Thai Union-led investor group that acquired Red Lobster.
Kenny criticized Red Lobster employees at meetings and made derogatory comments about them, according to former Red Lobster leaders who worked closely with Kenny…
At the direction of Thai Union, Kenny became interim CEO, according to Red Lobster’s bankruptcy filing.
In the months after Kenny took over, Valade’s leadership team and other veteran leaders left. In July of 2022, the chief operations officer and six vice presidents of operations overseeing restaurants were abruptly fired shortly before Red Lobster’s annual general manager conference.
Kenny appointed a Thai Union frozen seafood manager, Trin Tapanya, as Red Lobster’s chief operations officer overseeing restaurants. Tapanya had no experience running restaurants. He did not respond to CNN’s requests for comment.
Other Thai Union representatives also became more closely involved across Red Lobster’s supply chain, finance, operations and strategy teams…Thai Union took a larger role in Red Lobster’s supply chain decisions, despite pledges in 2020 that it would not interfere.
Red Lobster had spent decades developing a wide array of suppliers to buy at competitive prices and mitigate the risks of becoming too reliant on any single supplier.
Thai Union blew that up.
Red Lobster employees say they were pressured by Thai Union representatives to buy more seafood from Thai Union. Thai Union representatives also began sitting in on meetings between Red Lobster and seafood suppliers, said one of the former Red Lobster employees who witnessed these conversations. Thai Union was the direct competitor of these other seafood suppliers, and suddenly had intimate access to their products, prices and strategy. “Our suppliers were really upset that [Thai Union representatives] were in those meetings with them,” this person said.
Red Lobster now claims that Thai Union pushed out other shrimp suppliers, “leaving Thai Union with an exclusive deal that led to higher costs to Red Lobster”.
The “Endless Shrimp” Disaster The final blow to Red Lobster was offering an every-day special of all the shrimp you can eat. The firm had historically offered occasional all you can eat specials, to draw in first-time customers. But they had learned from a disastrous extended all you can eat crab special back in 2003, that if you are not very careful, you can lose a ton of money letting people eat all they want of an expensive food item.
Apparently, Thai Union pressured Red Lobster into offering an every-day “Endless Shrimp” special starting in June, 2023. Old guard Red Lobster management tried to push back, but were overruled. For Thai Union, this was of course a chance to sell more shrimp. But it led to huge losses on the part of Red Lobster. Internet personalities boosted their viewings by wolfing down plate after plate after plate of expensive shrimp:
The deal quickly went viral on social media. People started posting videos on Tik Tok showing how many shrimp they could eat. It became something of a challenge where people would try to eat as many shrimp as possible to gain social media clout. For example, a YouTuber called The Notorious Bob ate 31 plates of shrimp. Each plate has six shrimp so he ate 186 shrimp in total … another YouTuber called Sir Yacht stayed at Red Lobster for 10 hours and ate 200 shrimps throughout the day.
Red Lobster has now filed for Chapter 11 bankruptcy protection from its creditors, while it further downsizes to try to stay afloat. Thai Union has written down its investment in Red Lobster to the tune of $540 million, and its creditors now own the company.
The various actors in our current financial system played their usual roles here: General Mills spun off a non-core business; a private equity firm plundered its acquisition and then dumped it, presumably making gobs of money in the process for its partners; a supplier acquired a downstream company to develop a more integrated business line; a venerable American brand simply lost ground (think: Sears) in the competitive market place as tastes and competition changed over time, with vicious cost-cutting unable to save it.
This story is somewhat tragic, but I’m not sure there are any real villains, apart from the obnoxious outside CEO. Thai Union is a powerhouse seafood supplier, but they simply did not understand the American restaurant business and could not come up with a viable plan to fix Red Lobster. The now-unemployed restaurant workers may be victims, but the cooks and wait staff and store managers who worked extra hard, short-handed to keep serving their customers well despite horrible upper management – – to me, those are the heroes here.
I ran across an article by Lyn Schwartzer on seeking Alpha last week, which I thought was insightful regarding investments. Here is my summary.
The article is Most Investments Are Bad. Here’s Why, And What To Do About It. The article’s first bullet point is “Historical data shows that the majority of investments, including bonds, stocks, and real estate, perform poorly.” Unpacking this, looking at various investment classes:
Bonds and Stocks
Investment-grade bonds typically pay interest rates just a little above inflation, so it’s not surprising that they have been mediocre investments over the long-term. The prices of long bonds (10 years or more maturity) tended to rise between about 1985 and 2020, as interest rates came steadily down, but that tailwind is pretty much over.
It has been known for years, e.g. from a study by Hendrik Bessembinder, that only a tiny fraction of stocks makes up the vast majority of returns in equity markets. I wrote about this a couple of years ago on this blog.:
The rise of the S&P is entirely due to huge gains by a tiny subset of stocks. The average stock actually loses money over both short and long time periods. … half of the U.S. stock market wealth creation [1926-2015] had come from a mere 0.33% of the listed companies… Out of some 26,000 listed companies, 86 of them (0.33%) provided 50% of the aggregate wealth creation, and the top 983 companies (4%) accounted for the full 100%. That means the other 25,000 companies netted out to zero return. Some gave positive returns, while most were net losers.
As investors, we of course want to know how to lock in on those few stocks that will perform well. I see two approaches here, not mentioned in the article. One is to be very good at analyzing the finances and market environments of companies, to be able to pick individual firms which will be able to grow their profits. Being lucky here probably helps, as well. An easier and very effective method is to simply invest in the S&P 500 index funds like SPY or VOO. Because these funds are weighted by stock capitalization, they inexorably increase their weighting of the more successful companies and dial down the unsuccessful companies. This dumb, automatic selection process is so effective that it is very difficult for any active stock-picking fund manager to beat the S&P 500 for any length of time.
What the article suggests in this regard is to focus on businesses that have “durable competitive advantages (network effects, powerful brands, intangible property, economies of scale, oligopoly participation, and so forth),” or to try to pick up decent/mediocre companies at a low price.
The big tech companies which are mainly listed on the NASDAQ exchange have these durable advantages, and indeed the QQQ fund which is comprised of the hundred largest stocks on the NASDAQ has far outpaced the broader-based S&P 500 fund over the last 10 or 20 years.
Real Estate
All of us suburbanites know that owning your own home has been one of the best investments you can make, over the past few decades. The article points out, however, that real estate in general has not been such a great performer. If your property is not located close to a thriving metropolitan area, where people want to live, it can be a dog. The article cites abandoned properties all around Detroit (“large once-expensive homes that are now rotting on parcels of land that nobody wants”), and notes, “In Japan, there are millions of abandoned countryside homes that are nearly free. Many of them are in beautiful and safe rural areas, and yet there is insufficient demand for them.”
And so, “Most real estate falls somewhere between those extremes. It performs decently, especially when considering that it can replace the owner’s rental income or be rented out for cashflows, but after maintenance and taxes are considered, its unlevered total return from price appreciation and cashflow generation net of maintenance leaves something to be desired relative to gold.”
Gold As a Reference
The article uses gold as, well, the gold standard of investing returns. The supply of gold creeps up roughly 1.5% per year, so after say 95 years there is four times as much physical gold as before. We find that an ounce of gold will buy more food or more manufactured goods than it did a century ago, but that is because our efficiency of producing such things has increased faster than the gold supply. On the other hand, “All government bonds have underperformed gold over the long run, and most unlevered real estate has underperformed gold as well.” Stocks in the broad U.S. market (most foreign stock markets did more poorly) greatly outperformed gold, but that is only accomplished by the top 4% of stocks. The other 96% of stocks as group did not generate any excess returns.
Owner-Operators versus Passive Investors
I am looking at these issues from the point of view of a passive investor – I have some extra cash that I want to plow into some investment, and have it return my original capital plus another say 10%/year, without me having to do extra work. It turns out that many companies, especially smaller ones, provide useful products to customers and they make enough profit to pay off the owner/operators and the employees, but not enough to reward outside passive investors, too. These companies serve an important role in society, but are not viable investment vehicles:
Being an owner-operator of a business, or a worker at a business, makes a lot of sense. However, the vast majority of businesses are not strong enough to provide good returns for outside passive investors after all expenses (including salaries) are considered.
Good returns for outside passive investors are reserved for only the best types of companies; companies that are so dominant and high-margin that even after paying all of their executives and workers, they have plenty of excess profits for outside passive investors. Although stocks from any sector can have these characteristics, Bessembinder’s research found that major outperformers were disproportionally concentrated in the technology, telecommunications, energy, and healthcare/pharmaceutical sectors. They are on the right side of an emerging tech trend, they have network effects, they have economies of scale, they have protected intangible property such as patents, or they are part of an oligopoly, and so forth.
Similarly, real estate (especially unlevered), works most easily when it is occupied or used by the owner. After all, you must live somewhere. Now, you can make money buying and renting/flipping properties, but that typically demands work on your part. You add value by fixing the tenant’s toilet or arranging for a plumber, or by scoping the market and identifying a promising property to buy, and by working to upgrade its kitchen. All this effort is not the same as just throwing money at some building as a passive investor, and walking away for five years.
Upping Returns via Leverage
This is a packed sentence: “Historically, a key way to turn mediocre investments into good investments has been to apply leverage. That’s not a recommendation; that’s a historical analysis, and it comes with survivorship bias.”
For example, banks have historically borrowed money (e.g. from their depositors) at lowish, short-term rates, and combined a lot of those funds with the bank corporate equity, to purchase and hold longer-term bonds that pay slightly higher rates. Banks are often levered (assets vs. equity) 10:1. This technique allows them to earn much higher returns on their equity than if they used their equity alone to buy bonds.
It is easy to leverage real estate. If you put 20% down and borrow the rest, bam, you are levered 5:1. Now if the value of your house goes up 6%/year while you are only paying 3% on your mortgage, the return on the actual cash (the 20% down) you put in becomes quite juicy: “After maintenance and recurring taxes, the majority of unlevered real estate, even when rented out for cashflows, doesn’t outperform gold. But unlike gold, 5-to-1 leverage makes real estate actually pretty good in many contexts, and historically allows it to outperform gold.”
Large corporations can leverage up by issuing relatively low-interest bonds: “They can borrow large amounts of money for decades at low interest rates, and use that capital to organically expand their business, buy smaller companies, or buy back their own shares. Either way, they are borrowing abundant fiat currency at low rates and using that capital to build or buy business equity, and they are arbitraging that spread for shareholders.”
Savvy firms like Warren Buffett’s Berkshire Hathaway take it a step further, by having controlling interests in insurance companies, and investing the low-cost “float” funds, as we described here. From the article:
Berkshire has also made a habit out of buying small and medium sized private businesses in full. Many of these smaller companies would have higher borrowing costs if they were independent. But Berkshire can buy a lot of them, and then issue corporate debt at the parent company level at much lower interest rates than any of them could issue on their own. So he can buy a lot of unlevered cashflow-producing small or medium-sized businesses, and turn them into a portfolio of businesses that are levered with Berkshire’s very low cost of capital.
Now other companies like Ares Management and Apollo are jumping onto this arbitrage bandwagon, buying up insurance companies to get access to their captive cash, to be used for investing.
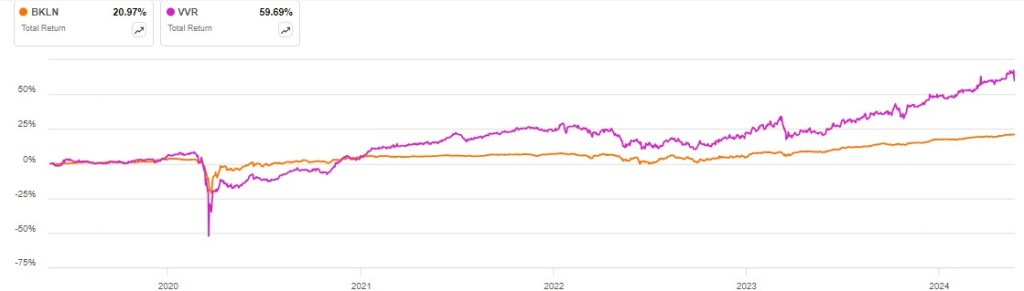
Here is another rough example of the power of leverage. The unleveraged fund BKLN holds bank loans, and so does the closed end fund VVR. But VVR borrows money to add to the shareholders’ equity. There is more complication (discount to net asset value) with VVR which we will not go into, but the following 5-year chart of total returns (share price plus reinvested dividends) shows nearly triple the return for VVR, albeit with higher volatility:
The Changing Global Economic Landscape
The article closes with some summary observations and recommendations. The past 30-40 years have been marked by ever-decreasing interest rates, and by cooperation among nations and generally increasing globalization. It seems that these trends have broken and so what worked for the last four decades (buy stocks, shun gold) may not be as good going forward:
For equity and real estate investors, the key takeaways from this piece are 1) do not extrapolate the prior decades for a given investment and instead assess it with this context in mind, 2) try to emphasize the sectors [such as Big Tech] that Bessembinder identified as ones that disproportionally generate excess returns, and 3) look for companies that have locked in or are otherwise still able to play this arbitrage game going forward in a more difficult environment for it.
Additionally, hard monies [i.e. gold, silver] become a serious alternative once again in this context, and are worth serious consideration for a portfolio slice, because the hurdle rate for stocks to outperform them is high when there are not a lot of tailwinds at the backs of stocks.