For the past two years, we’ve had a unified government in which the Republican party has populated the White House and had majorities in both chambers of congress. Once the new legislators are in office we’ll have a divided government. That means that the political party controling the White House won’t also control the senate and house of representatives. In the spirit of saying something of substance, I want to know what the implications are for our fiscal picture.
One can measure fiscal health in many ways. Does a divided government bode well for shrinking the deficit? Rather than spit-ball about politics, I take the data since 1960 in one hand and a model in the other. See the end notes for model details.
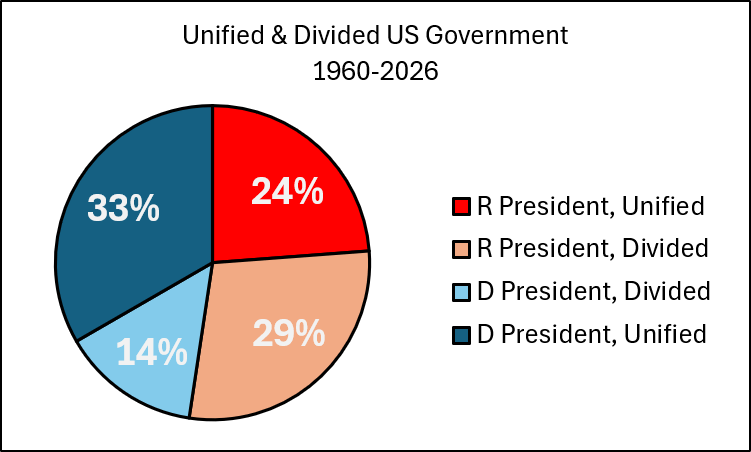
Since 1960, the most popular form of government split has been a Democratic president and unified government, followed by Republican presidents and a divided government. Democrats have controlled at least one chamber of congress for 62% of the years. Do these splits matter for federal outlays, receipts, and the deficit? Since a unified democratic government was most common, I use that as the baseline fiscal case and compare the cases to it.
Below are the average impacts of government-party types on federal spending, revenues, and the deficit. The blanks are insignificant differences. On average, the only party split that results in less spending is a Democrat president with divided government. Those and unified Republican governments raise more revenue and reduce the budget deficit from its trend (there was a small decline in in discretionary spending at the start of Trump’s 2nd term with a unified government). The bad news for deficit hawks is that Republican presidents with a divided government – the type that we’ll have for the next two years – perform poorly. On average, they reduce government revenue and increase the deficit. Again, all of this is ‘on average’.
I predicted a ‘moderate red wave’ here in 2022. I predict a blue wave for 2026 that is bigger than the red wave of 2022, though not a ‘mega tsunami‘
That post looks good now with the exception of those last five words- it was in fact a blue ‘mega tsunami’ by Kalshi’s definition (Democrats hold 240+ House and 54+ Senate seats).
This comes after a longtime WSJ editorial writer hoped for a big Republican loss, something I’ve never seen from the WSJ before. But if they speak for the markets, it makes sense- US stocks opened up 2% the day after the election.
Crypto and gold prices are also up, an odd combination. Oil prices are down, perhaps seeing an end to the Iran war as more likely. Polymarket shows the odds of a US invasion of Iran this year down 5%. John Ossoff and Ron Desantis saw their odds of becoming President in 2028 rise at the expense of JD Vance and Gavin Newsom.
What will we see change on economic policy? Congress may lower tariffs and take back some of the tariff power they have long delegated to presidents. The Federal Reserve board will feel more free to raise interest rates if they think it is warranted. Many state-level results mean data centers will get harder to build, which will hurt the ‘picks and shovels’ companies literally building them but not necessarily the frontier labs who won’t be able to spend as much on racing ahead. NVDA and Micron stock is down while Google, Meta, Anthropic and OpenAI are up.
But the fact that President Trump still has veto power will limit how many big changes we’ll see over the next two years for anything that would require a new bill. Welcome back to divided government, to gridlock, and to checks and balances.
This is my last post before the midterms Tuesday. What will they bring?
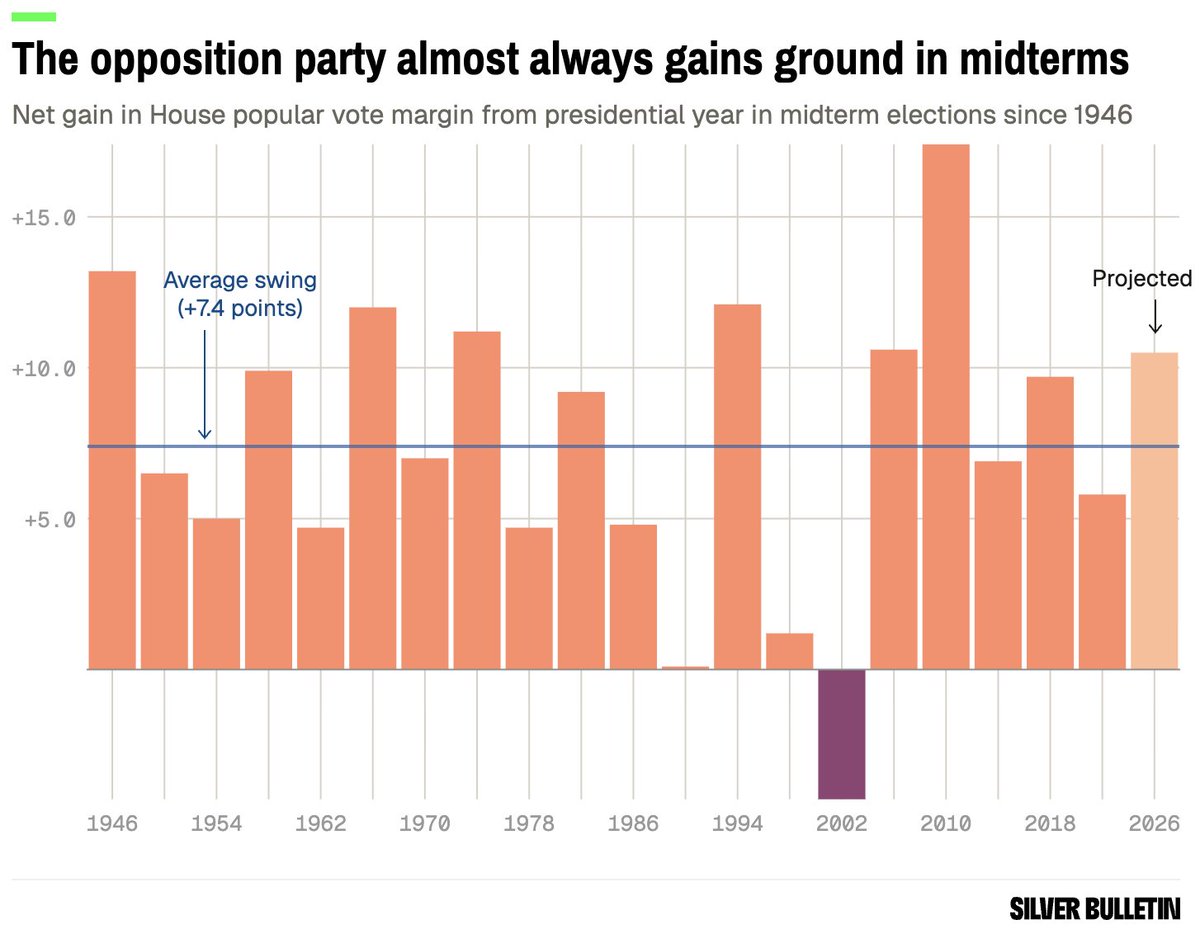
Midterm elections are usually bad for the President’s party:
I don’t think this year will be an exception to the rule. I see many indicators pointing in the same direction.
The largest US prediction market Kalshi currently gives Democrats a 91% chance to take the House and a 66% chance to take the Senate. The international Polymarket and play-money Manifold currently give slightly higher chances, 93/67 and 94/69. Forecaster Nate Silver is higher still at 95/76.
The best odds I’m seeing for Republicans among the models I have followed for years is Ray Fair giving Dems only a 60% chance to take the House (he doesn’t forecast the Senate). In Fair’s model, the economy is working in favor of Republicans; inflation is a negative for them but economic growth is a stronger positive (including the 3.4% Q3 GDP estimate just released today).
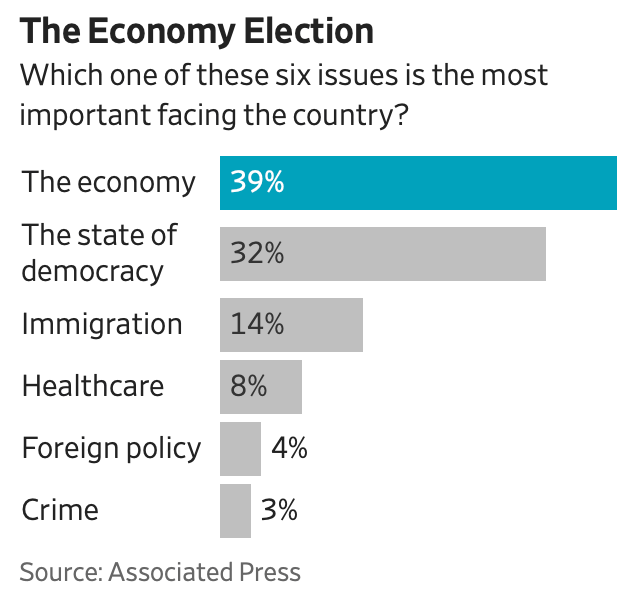
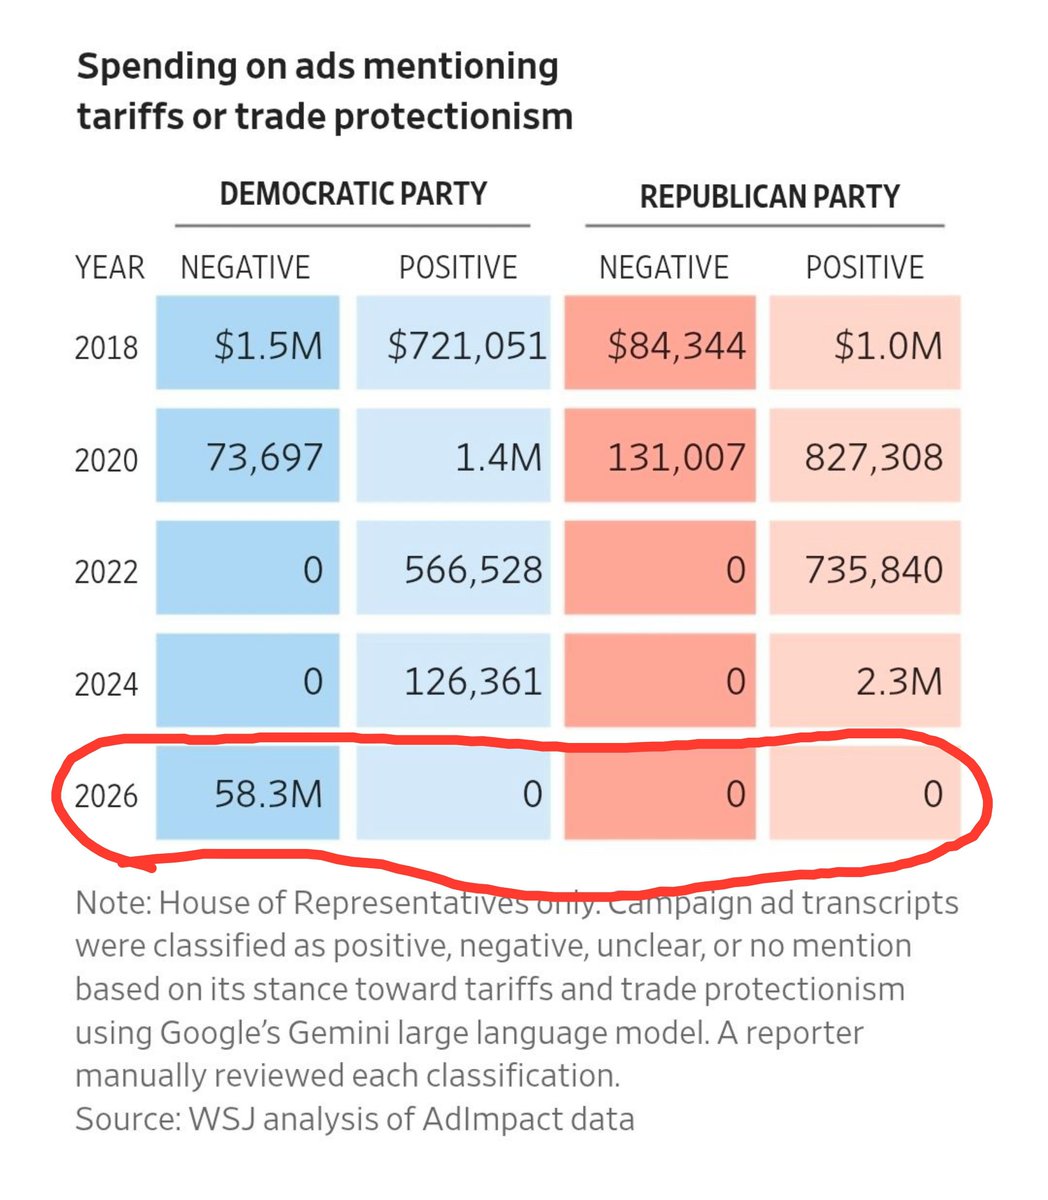
In practice though I think economic issues are working in favor of Democrats. The economy is good in many ways, like 4.2% unemployment- but most people aren’t happy about it. Consumer sentiment is at record lows. Economic growth is solid but largely driven by the AI boom, which gives people plenty to be nervous about. Inflation is only a bit high (3.4% vs a 2% target) but easy to tie to administration policies like tariffs, war, and pressuring the Fed to lower interest rates. Ad spending indicates that politicians on both sides think tariffs have gone from a minor issue that voters have mixed feelings about to a major issue that voters don’t like:
Gas prices have long been especially salient, and are currently high because of the Iran war. I said here in March:
if the US administration wants to avoid a midterm wipeout driven by high gas prices, I see only 3 options:
Get lucky and see the Iranian regime fall quickly
Negotiate an end to the war quickly (which might itself be unpopular if they can’t get a good deal) or just declare victory and go home (but its not clear whether Iran would re-open the strait now just because the US stopped bombing)
Restrict Exports
But they took none of those three options, and now it seems the midterm wipeout is coming.
I predicted a ‘moderate red wave’ here in 2022. I predict a blue wave for 2026 that is bigger than the red wave of 2022, though not a ‘mega tsunami‘. The main things Republicans have going for them are the Senate map (Dems need to win in multiple 2024 red states to win) and the possibility that angry anti-incumbent voters will take down some Dems too.
The phrase “are you better off than you were 4 years ago?” seemed to have been a winning campaign slogan for Ronald Reagan in 1980. But when I looked at the data, it didn’t really hold up, if we are looking at real income growth to determine “better off.” Real family income growth was actually positive under Carter, but he lost reelection. Then four years later, Reagan won reelection, despite having negative real income growth. This is a pattern we see often in recent presidential reelection years. Interestingly, it does not appear to be 4-year income growth that matters, but 1-year income growth might.
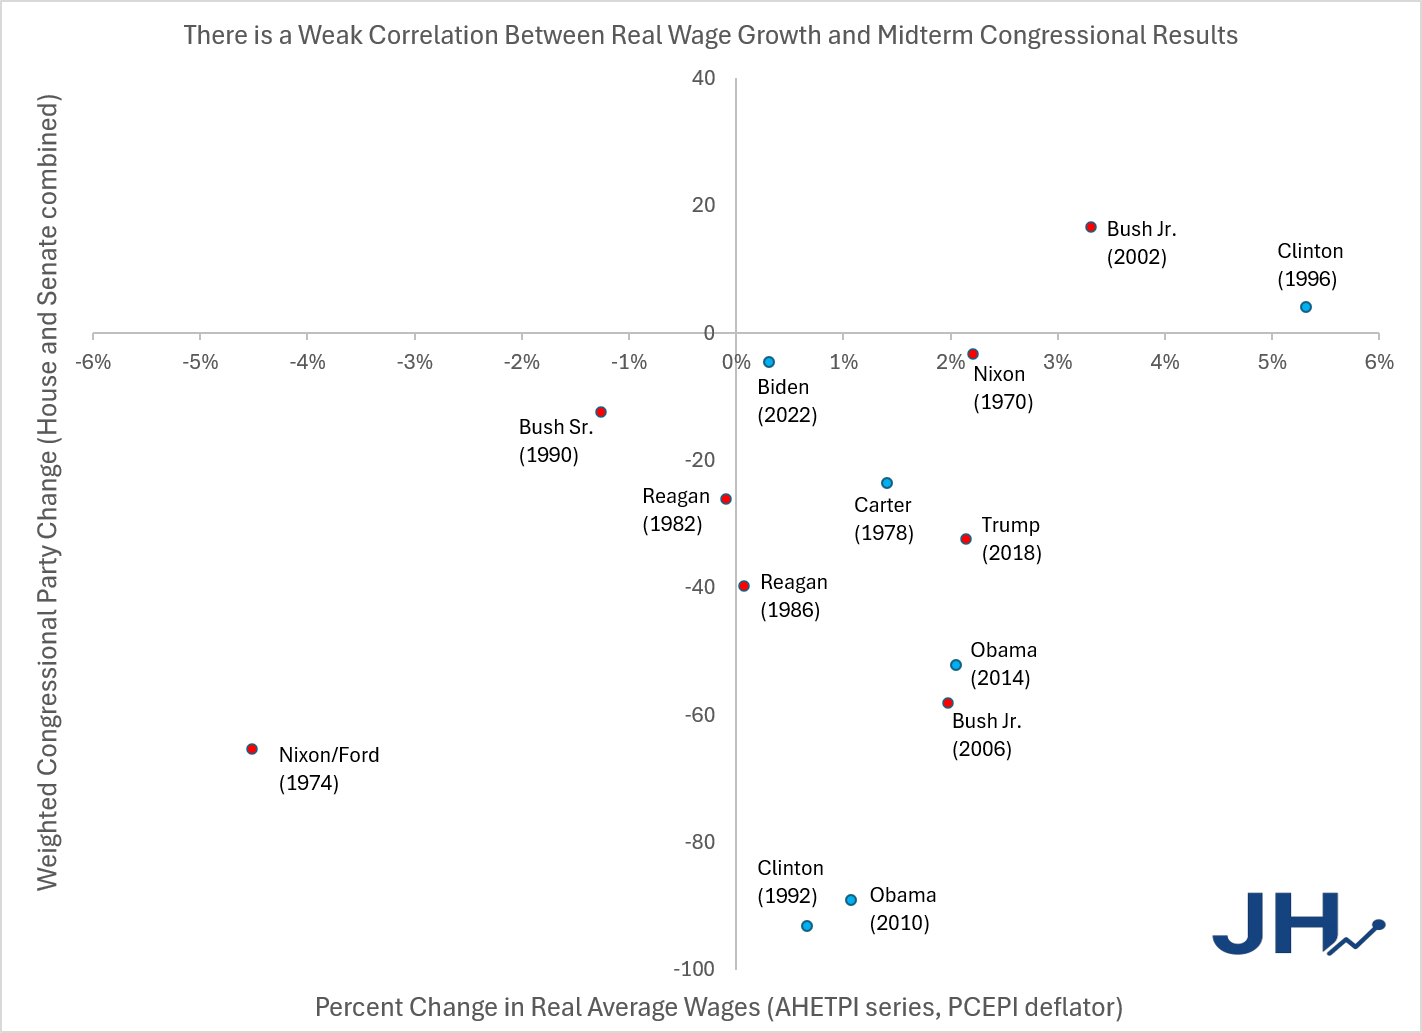
Is there any similar data we can look at for midterm elections? It is well known that Presidents almost always lose seats in a midterm election. But might they lose fewer seats if the economy is performing well? The following scatter plot shows all midterm elections since 1970. On the horizontal axis is the percent change in real wages (AHETPI series, deflated by the PCEPI) from the January a President takes office until November of the midterm election year. The vertical axis shows the net change in Congressional seats for the party of the President, including both the Senate and House (I weight Senate seats at 4.35x House seats, which is somewhat arbitrary).
Figure 1
What can we learn from this scatter plot? I would say there is a weak correlation between the variables: better real wage growth means losing few seats. The sample size is small, so I am reluctant to plot a trendline, but it would be positive. The only two midterm elections since 1970 where the President’s party actually gained Congressional seats had very high wage growth: Bush in 2002 (3.3%) and Clinton in 1996 (a very robust 5.3%). Very negative wage growth shows up just once, for the Nixon/Ford midterm in 1974, and here the Congressional losses were pretty massive.
Now you might object that other factors matter. And surely they do. The Republicans probably would have lost a lot of seats in 1974 anyway, due to Nixon’s resignation. But I’m sure the higher rates of inflation and resulting negative real wage growth didn’t help. And Bush probably got a significant post-9/11 hero bounce in 2002, though the real wage growth might have helped too.
However, Clinton and Obama had the worst midterm losses in this era, in 1992 and 2010, much worse than Nixon/Ford in 1974, and despite positive but weak real wage growth. Does this mean the correlation is useless?
Here’s one way to save it: compare Presidents against themselves. While Clinton and Obama had poor showings in their first midterm elections, their second midterms were much better — and had much better wage growth! Ditto for Nixon, though in reverse: his first midterm was pretty good, and so was real wage growth. Reagan had similarly bland real wage growth rates in both midterms, and had similarly mediocre Congressional losses. Bush did worse in his second midterm — again, you could blame a reverse-9/11 effect, with voters now weary of the global War on Terror, but wage growth was also worse.
What does this all mean for Trump? While we don’t have the full wage growth picture yet, through 18 months it has been pretty mediocre: 0.3%, and falling in recent months due to inflation exceeding wage gains for most of 2026. On social media and among pundits, a lot of people are trying to make comparisons to Biden. “But gas prices were even higher under Biden!”
If Figure 1 is at all useful, it is probably most useful to compare Trump to himself, in his first midterm. Wage growth through November 2018 was about 2.1%: not bad, not great. And he suffered middling Congressional losses. Because wage growth will almost certainly be much worse this time around, we can expect Trump to perform much worse than in his first, 2018 midterm. If Democrats pick up 20 seats in the House and 5 seats in the Senate (current prediction markets suggest about this many), this will put Trump pretty close to the Reagan 1986 point in Figure 1. That feels about right, given recent history, though it wouldn’t be surprising if the Republicans lost even more seats, since that would be a Congressional shift not much different from Trump’s first midterm.
So many things are happening that it’s hard to decide which to write about. So I’ll briefly cover several that would each deserve a full post on a normal week:
1. The Fed voted unanimously to raise rates to 4%, showing that the Warsh Fed still has some independence from the President.
2. The 10-year Treasury bond hit 5%. The CBO’s long-term budget forecasts assume 4% rates for the 10-year, and looked unpleasant even with that rosy assumption. The UK dumped Prime Minister Liz Truss over their 10-year hitting 4.5%.
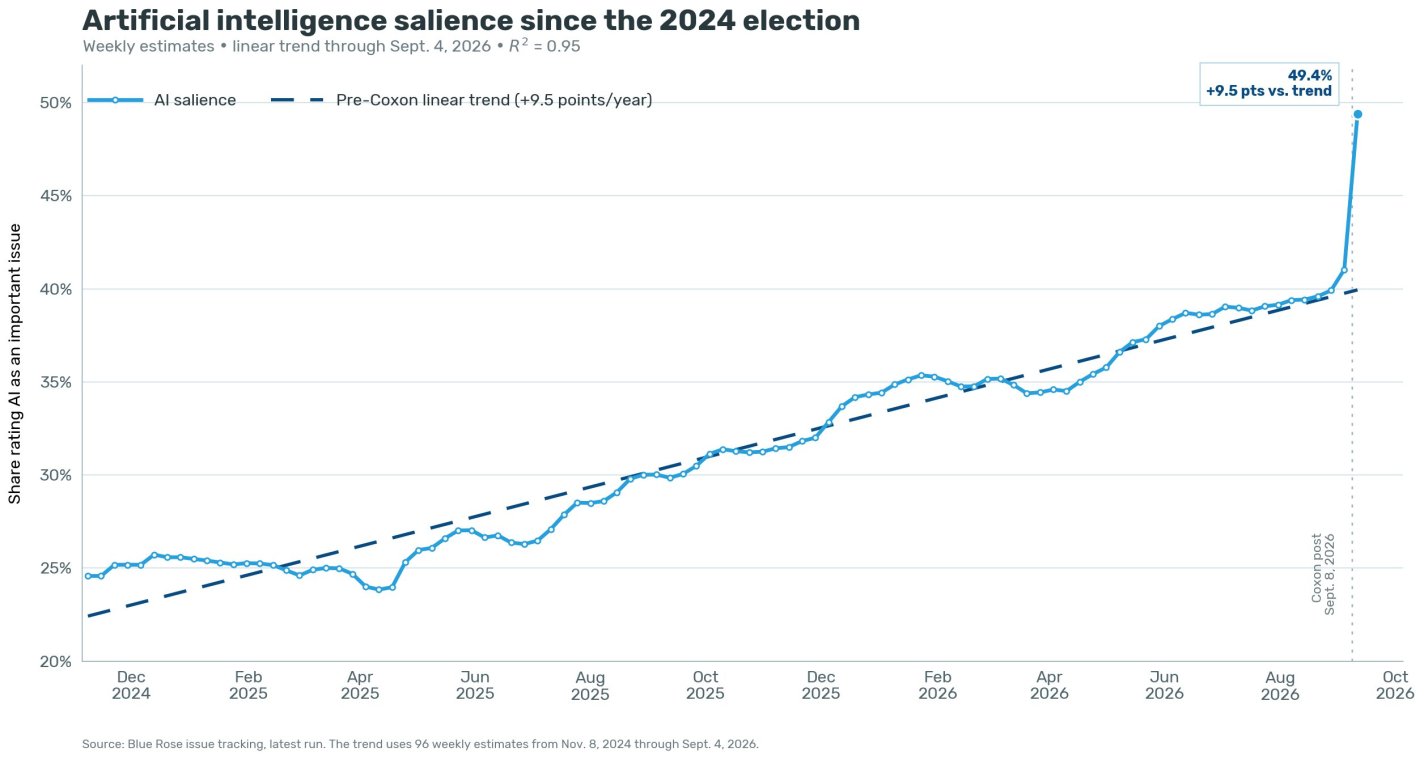
3. Jacob Coxon resigned from Anthropic over AI safety concerns and set off a surprisingly large firestorm over it.
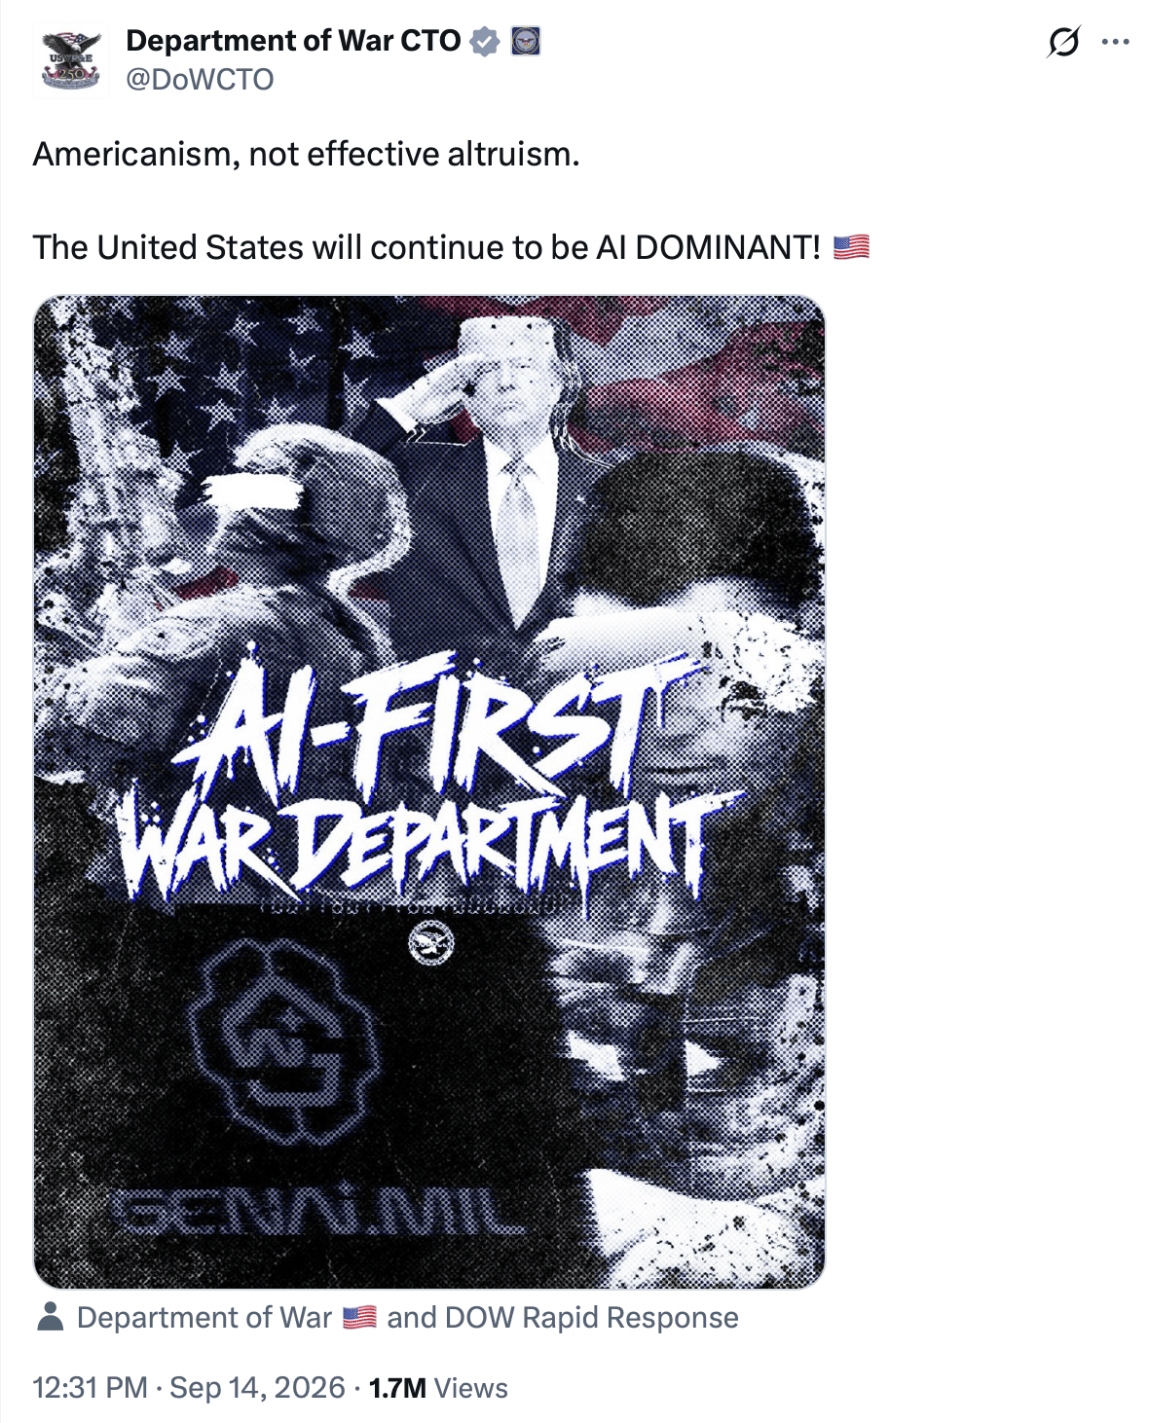
4. The Trump administration reacted by insisting we move forward with AI, with the Department of War blaming Effective Altruists for trying to slow it down:
I suspect this could lead many people to get into Effective Altruism by promoting it from ‘weird thing for nerds‘ to ‘something you can do to oppose Trump’. If that interests you, this is a good place to start.
5. EA hero Michael Kremer (whose work inspired many donations to deworming) was just appointed Chief Economist of the World Bank.
6. But AI progress keeps rolling. Quantum theorist Scott Aaronson declares the Singularity is here:
I recoil from the neverending shell game where you say “oh sure, of course AI can now [escape from its sandbox / solve Millennium Problems / whichever dramatic thing it most recently did], no one ever denied that [I did deny it], wake me up when AI does [thing AI hasn’t yet done but is going to do next year], that’s when I’ll reevaluate my whole worldview [no I won’t].” Where no matter how fast the rollercoaster accelerates, even after your whole familiar world has vanished behind you, you’re still inventing reasons why it doesn’t count.
My position on AI is merely the conservative, skeptical position of 2006, updated with intellectual honesty for the reality of late 2026. And that position, if you need me to spell it out, is as follows:
It seems to me that the Singularity has already started; it’s just wildly unevenly distributed.
I’m honestly surprised we have yet to see an upsurge of millenarianism. Y2K concerns came and went 2000 years after Jesus’ birth. But see how much people worry about AI now, and realize it will only get more powerful as we approach 2000 years after his death- 2033, or if you trust the revisionists, 2030.
Governors serve for 4 years in most US states. You can find many rankings of state economies out there, but they tend not to measure how states have done over the last 4 years- instead they either use measurements based on levels (things like mean income which were mostly determined by events before the current governor’s term), or one year of growth (which has a lot of randomness), or they don’t explain what period it is based on at all.
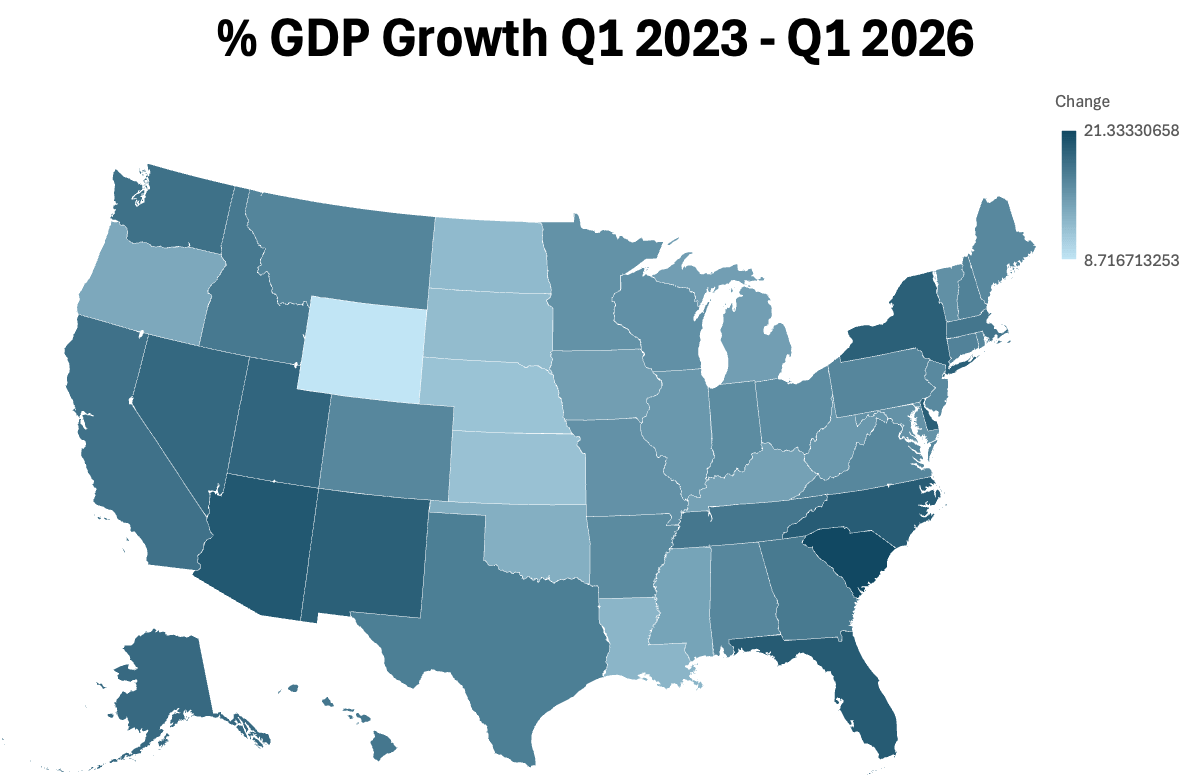
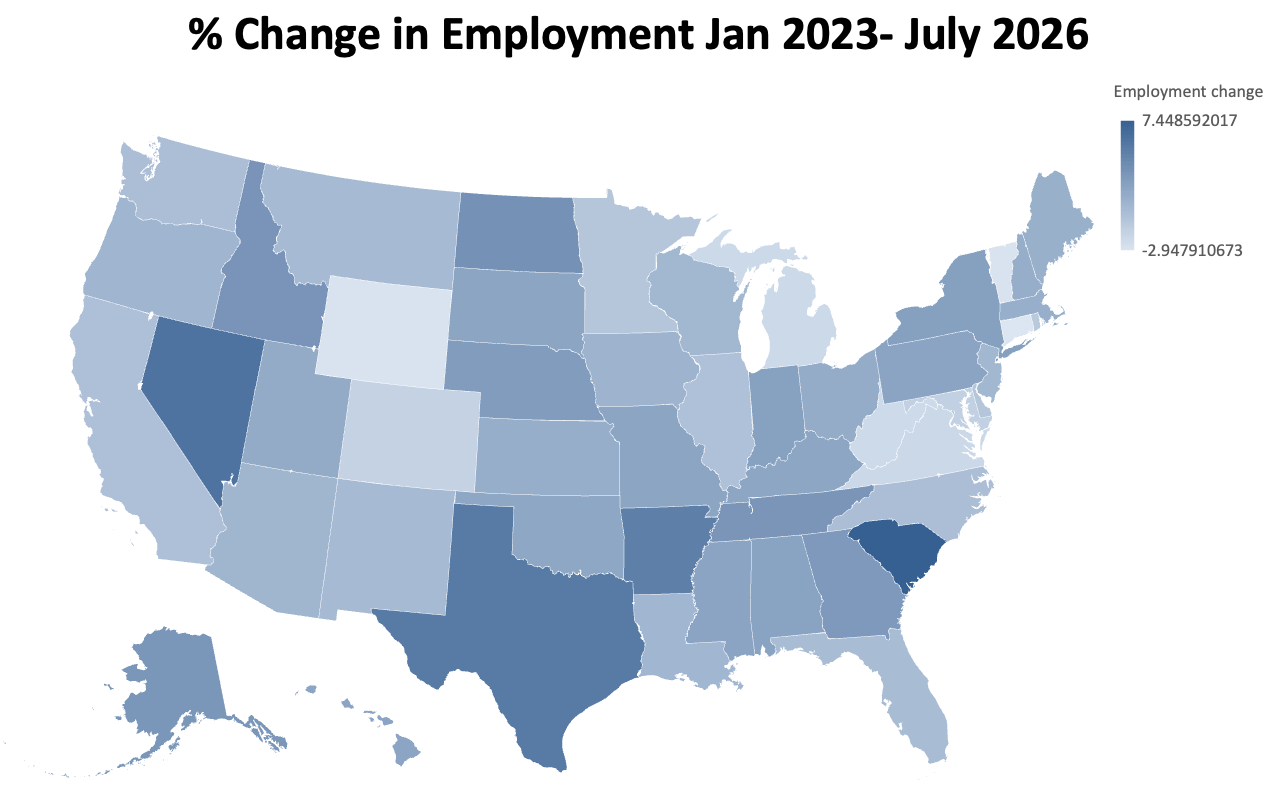
But if you want to know how a state’s economy has performed under an incumbent governor (for instance, to inform your vote on whether to re-elect them), the best way is to measure it’s economic growth over the period of their term- most commonly, 4 years. A governor currently up for re-election following their first term would typically have taken office in January 2023. Below I map how two of the most commonly used economic measured have fared by state from January 2023 to the most recent available data (what is available differs by measure):
Source: My calculations from BEA current-dollar GDPSource: My calculations from BLS data on total employment
Overall South Carolina looks best and Wyoming looks worst. There might be other economic measures you prefer, like poverty rates or median income- but whatever measure you prefer and whatever politician you are evaluating, I encourage you to check how that measure has changed since their term started and how that ranks compared to other similar regions.
This post was inspired by the mailers that would-be Rhode Island Governor Foulkes’ campaign keeps sending me suggesting I vote for her in the primary against incumbent Rhode Island Governor Dan McKee because “we are last in the country for our economy”, citing this CNBC ranking. Looking into the source, CNBC says:
There has been a lot of shade thrown at the United Kingdom recently from economists and political scientists. Economic growth has gone down the tubes and there have been six prime ministers over the past decade. As an American, I didn’t really know if that was a lot. The social media says that we’ve had a lot of turnover recently. Is six prime ministers in ten years a lot in the UK’s parliamentary system? I grew up watching Tony Blair on TV for a ten-year stretch. But I had no context for the historical norm or whether there is any precedent. Here I look at the data.
Right now, there are a record number of former prime ministers still living (PM). Prior to the recent spike, the maximum number of living people who had left office was five. Right now in 2026, there that number is nine! And if the current PM, Andy Burnham, follows the recent trend of short stints in office, then they’ll hit ten. As an American, it’s hard for me to imagine having 10 living former presidents. According to the below charts, the British are probably a bit jarred too!
Why So Many?
In last week’s post I noted that we’re tied for the most living former presidents. But truly, the UK’s numbers are what inspired me to look at this topic in the first place. To recap, the number of living ex-executives can be caused by 1) Longer lifespans, 2) Leaving office at a younger age, and 3) More unique executives. In the US, being currently tied for the record is overwhelmingly driven by longer lifespans. What about the UK?
If you count president Trump, the number of living former presidents is at a historic high of five (Clinton, G.W. Bush, Obama, Trump, Biden). The number of living ex-presidents can increase for three reasons. 1) More people becoming president, 2) ex-presidents having longer lifespans, and 3) presidents leaving office earlier in life. Why do we have so many right now?
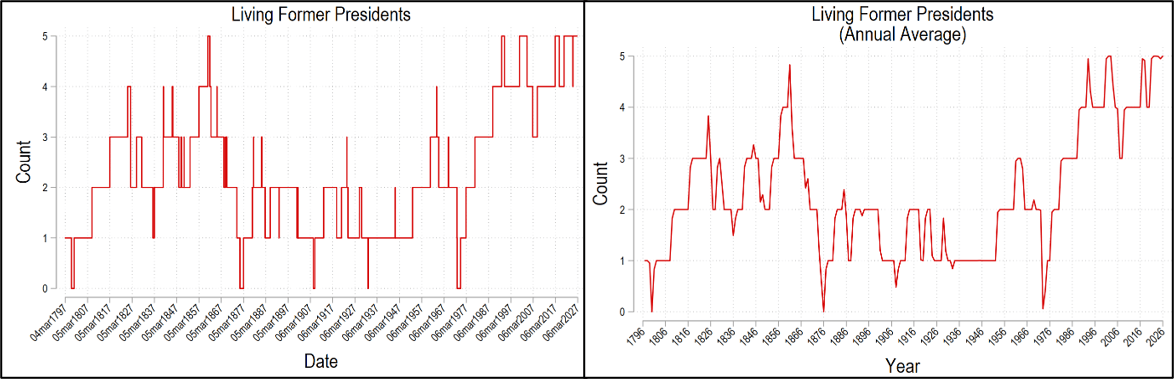
The historical maximum number of people who both 1) leave office and 2) live simultaneously with others is five. It first happened in 1861 when Abraham Lincoln (16th) was president for just under a year before John Tyler (10th) died in 1862. Since then, the number of living ex-presidents has been mostly below four if not below 3. The figures below graph the number of people living who have been US president. The left graph uses daily data and the right uses the annual average (weighted by day).
In fact, besides Washington, we’ve had four other periods when there were ZERO ex-presidents living. The first was under Grant (18th). This changes my perspective of that period. Living ex-presidents provide a sense of continuity – that something from the past continues today. They give us hope that our country will continue into the future. Grant presided over part of the reconstruction era. For part of this presidency, there was no one else who knew how he felt and no living person who had been in his position. What a tenuous time!*
The other presidents who, at some point, had no living predecessors were Theodore Roosevelt (26th), Herbert Hoover (31st), and Richard Nixon (37th). But since 1981, we’ve had three or more living presidents. So, most of us feel like that’s “normal”. Imagine if there was just Trump, and that’s it. That’d feel jarring.
1) Are More People Becoming President?
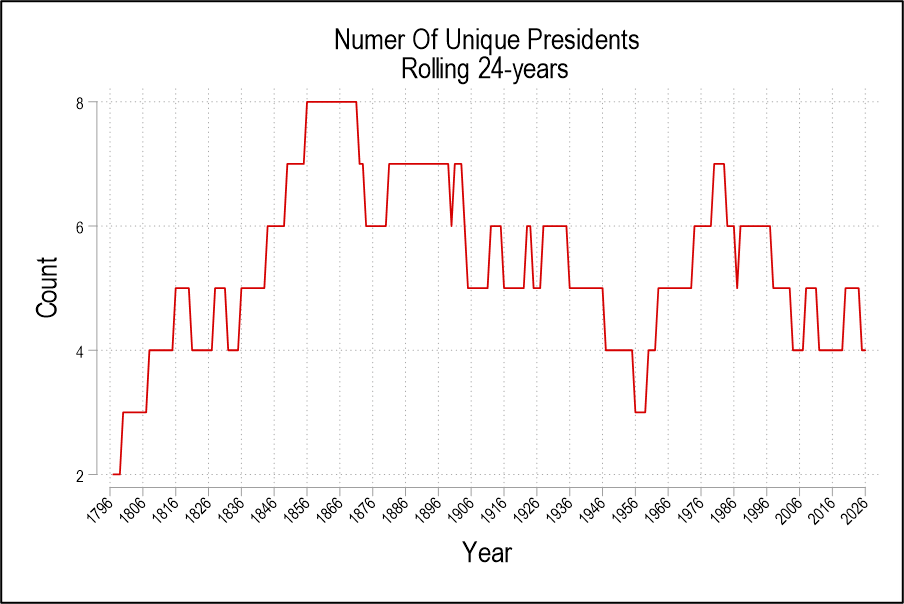
A presidential term is four years and only one president was in office for more than two terms, Franklin Roosevelt (32nd). Let’s take a 24-year trailing average. With 8-year tenures, the least number of presidents is 3. With 4-year tenures, the greatest number of presidents is 6. Assassinations and other deaths of sitting presidents can push the number higher. The graph below is the number of unique people to act as head of state over the prior 24 years (I say ‘unique’ because Cleveland (22nd & 24th) and Trump (45th & 47th) both served two non-consecutive terms).
We can conclude that the number of unique presidents is not exceptionally high at this time. The historical average is about 5.2 unique presidents. We’ve been below that since 1998 owing to a higher proportion of two-term presidents since then. Before Biden (46th), Bush (41st) was the last time that we had a one-term president. So, in terms of executive regimes, the 21st century has been unusually stable. But this stability also places downward pressure on the number of surviving ex-presidents. So, we’ve had many living ex-presidents despite our few regime changes. Reason 1) doesn’t explain why we have so many living ex-presidents now.
Alan Greenspan died this week at age 100. He was the Federal Reserve chair during my entire childhood.
But since I wasn’t really following markets and macro at the time, I don’t think of him in terms of monthly announcements about interest rates. What I find most interesting now is the winding personal and intellectual path he took to become a long-serving Fed chair.
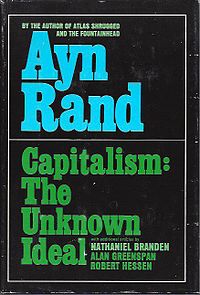
He studied clarinet at Julliard before later getting economics degrees at NYU. He supposedly attended the famous 1944 Bretton Woods conference that organized the post-war international monetary system- but as part of an orchestra, not as a monetary economist. In 1966 he coauthored “Capitalism: The Unknown Ideal” with Ayn Rand, where he argued against antitrust and consumer protection laws and for the gold standard. This may be why my intro macro professor Bobbie Horn always referred to Greenspan as “Ayn Rand’s boy toy”.
His advocacy for the gold standard is striking given that just two years later he would join the campaign of Richard Nixon, who took the US off the gold standard in 1971. Then Greenspan would go on to chair the Fed in the now-standard discretionary manner while making, as far as I can tell, no attempts to move it back in the direction of a gold standard.
While it’s unclear whether Greenspan’s unusual path improved his ability as a Chair, it was at least possible then to reach the office by his somewhat unusual path. Since his 1987 appointment the path to the highest appointed offices narrowed to include only more conventional candidates. Randy Barnett and Josh Blackman noted this in a 2015 article on the Supreme Court:
earnest, platinum-résumé’d law geeks have their eyes set on “the Big Bench,” so they keep tidy lives because they think they might someday face a confirmation hearing. It is an unfortunate reality today that to be a judge, you cannot hold vehement opinions prior to the nomination and confirmation process.
I see similar forces at work in economics, where the 50 economists who have a shot at being Fed Chair and the 500 who think they do all hold their tongues. But what does that mean for the kind of Fed Chairs we get?
the truth about SCOTUS-wannabes who “trim their sails” and limit their potential based on a fear of a future confirmation hearing: Such persons lack the character a justice needs…. “Courage is a muscle. You develop courage by exercising it. Sitting on the fence is not practice for standing up.” Imagine what it takes to live your whole professional and personal life as a “justice-in waiting.” These SCOTUS-wannabes spend their careers seeking the approval of others, in the hopes that one day they will be nominated because of their friendships across the political spectrum.
Barnett and Blackman argued that this should change, and I think this is now in the process of changing again:
Such willfully “stealth candidates” should be disqualified from consideration for the Supreme Court…. We need jurists who are fearlessly committed to the rule of law, reputation be damned…. Paper trails are an asset, not a disqualification.
I heard so many recommendations to read Julius Caesar on the Conquest of Gaul and Winston Churchill on the Second World War– and the recommendations were right. We’re incredibly lucky that some great wartime leaders also happened to be great writers who chose to take the time to share their perspective on the history they helped make.
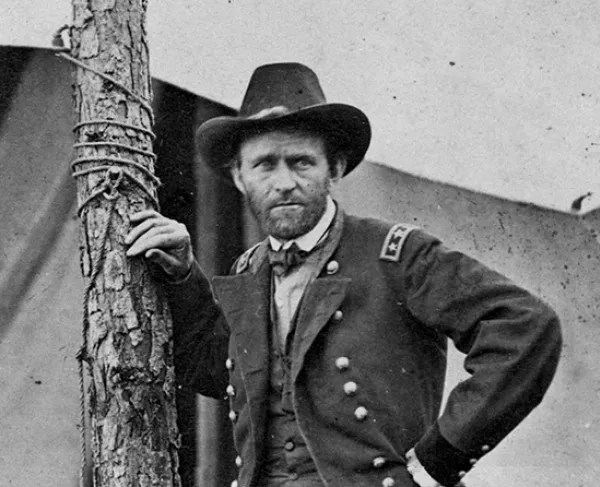
I rarely heard Ulysses S Grant mentioned as being in the same class of writer- but after reading his memoirs I think he should be. He was obviously a central wartime leader like they were, the highest-ranking general in the victorious Union army by the end of the US Civil War. But I’d never heard how he was also a great writer. He makes history like the campaigns of the Mexican and Civil wars feel understandable, while also sharing funny human stories. Some of these asides feel like they could have been written by Mark Twain, who did in fact help Grant edit and publish his memoirs.
It’s the rare doorstopper book that I wish were much longer- Grant was a two-term US President but his memoirs don’t cover those years at all. I don’t know how much of this is because he wanted to avoid the topic (he’s usually considered a much better general than president) and how much is that he simply ran out of time by dying of cancer.
A few highlights to give you an idea of what Grant was like. Certainly more like a modern economist than I expected: