Economy of Communion and Expressive Rationality

Today I am learning about The Economy of Communion movement in Omaha, NE. My visual first impression of downtown Omaha is that it looks like mid-century New York City.

The Economy of Communion, founded by Chiara Lubich in Brazil in 1991, is an example of cooperation emerging through voluntary economic relationships. Businesses participating in the movement operate in competitive markets, but they commit to sharing profits and supporting people in need.

EoC gave me some books in which I came across a chapter by Luigino Bruni that included a passage on expressive rationality:

A rationality that is capable of communion should also transcend the simple instrumental logic… This term was introduced to indicate economic action that is guided not by a logic that is primarily instrumental, but by the desire to “express” something of one’s own personality or one’s own values…

Some concept of this runs through economic literature (Kreps 1997). Bruni claims that the idea can be traced back to Max Weber. The EoC project could also relate to the work of Elinor Ostrom (1990), who challenged the conventional wisdom that common resources inevitably suffer from overuse. Ostrom documented communities that successfully developed their own institutions for cooperation.

  • Economy of Communion. “About the Economy of Communion.” Official project website.
  • Kreps, David M. “Intrinsic Motivation and Extrinsic Incentives.” The American Economic Review, vol. 87, no. 2, 1997, pp. 359–64. JSTOR, http://www.jstor.org/stable/2950946. Accessed 7 Nov. 2026.
  • Ostrom, Elinor. 1990. Governing the Commons: The Evolution of Institutions for Collective Action. Cambridge University Press.

The Blue Wave Was Not That Surprising If You Followed Prediction Markets

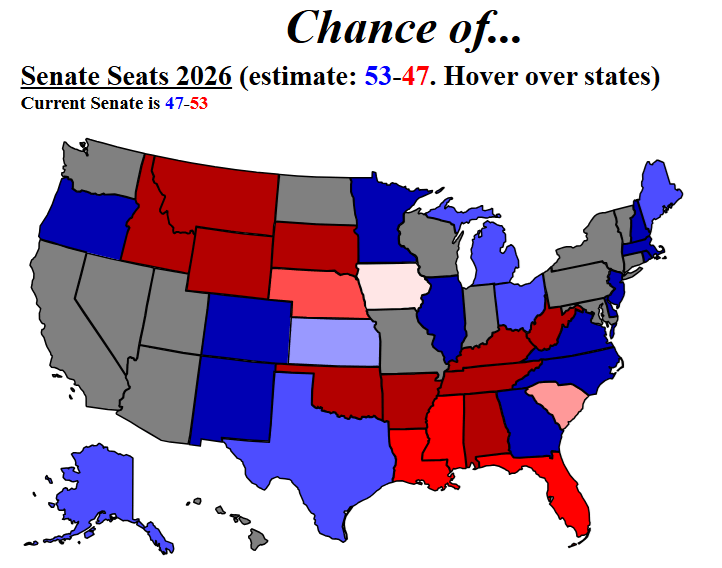
The election last night was clearly a victory for Democrats. But was it a surprise? For the most part, no, especially if you follow prediction markets. Here’s what the Senate map looked like on ElectionBettingOdds.com the night before the election:

Of course, there are still a few surprises on that map, such as Iowa, South Carolina, and maybe Mississippi. But only Mississippi was a huge surprise. Betting markets had Iowa as a toss-up, and South Carolina as 2/1. And even in Mississippi, the Democrat had 1-in-7 chances based on the average across three betting markets. 1-in-7 chances do happen sometimes! None of the states that were solid blue or red on the map (indicating >90% chances) went the other way. But even without those three races, it was clear that Democrats were the favorite (even if the extent of their domination wasn’t completely clear the day before).

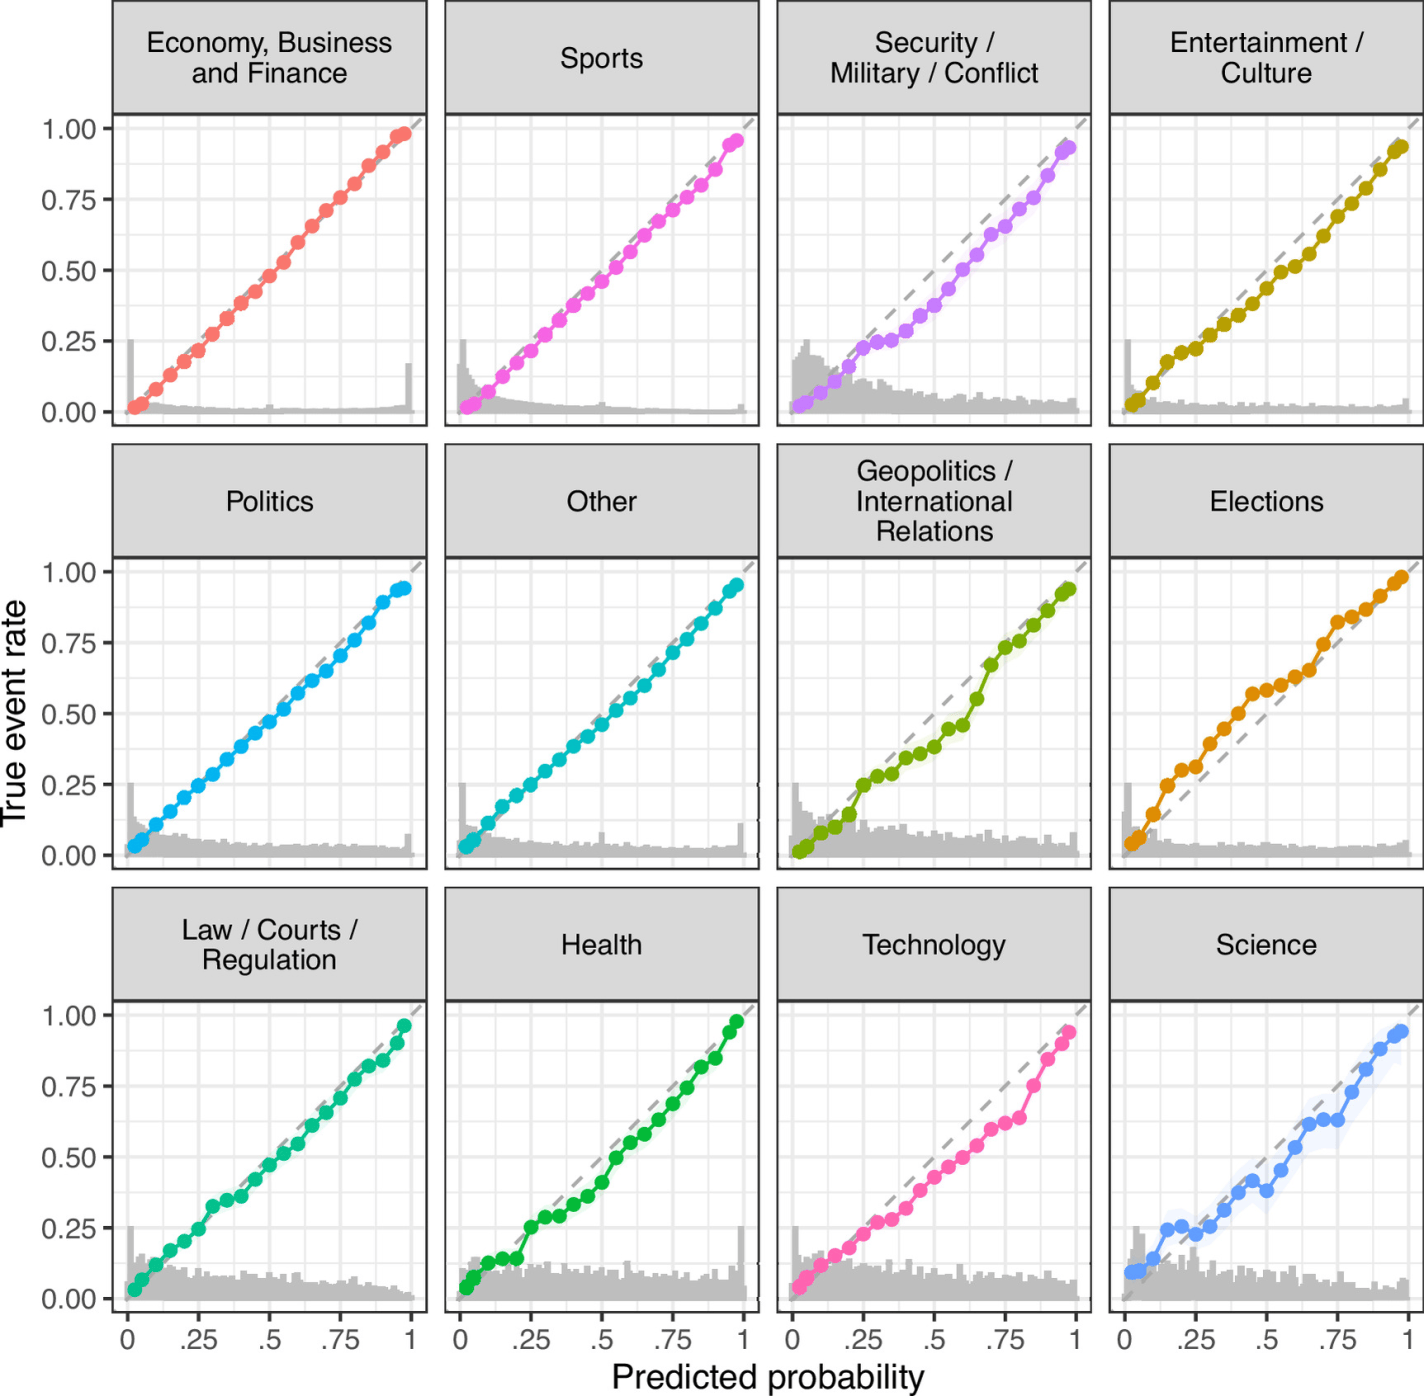
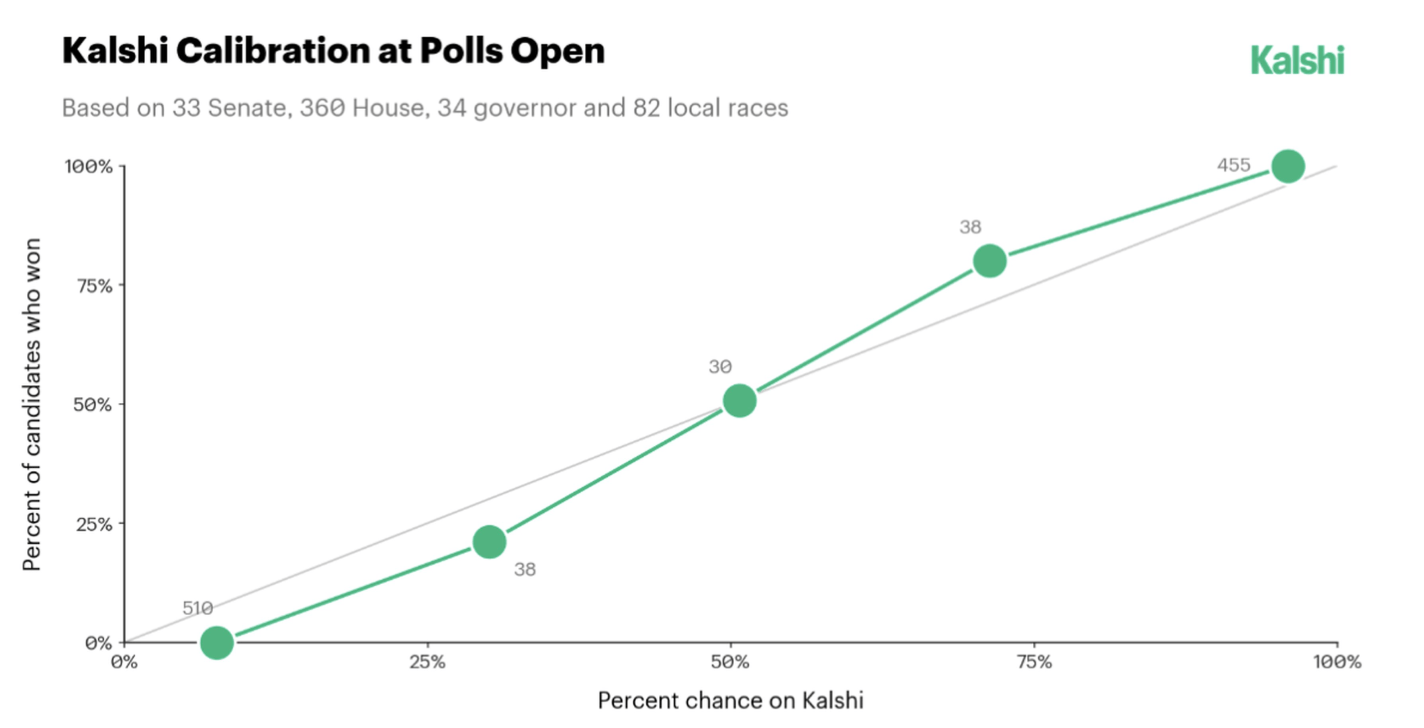
And these are not just a few cherry-picked results from one election. A recent paper published in PNAS shows that across a wide variety of outcomes, prediction markets are “well calibrated” — that is, events with X% probability on prediction markets tend to happen… about X% of the time!

UPDATE: Here’s a calibration Kalshi just provided for the 2026 midterms:

Halloween candy quality has plummeted

There’s plenty of press about sticker shock on halloween candy prices this year, but the day having arrived and the candy now opened, I can tell you the biggest shock to me was how notably inferior it was to standard “full size” candy equivalents. The Kit Kats are thin and flavorless, the Twizzlers taste like bottom shelf generics. I had heard that chocalate products had reduced their cocao content, but Twizzlers? I tried a few other gummmy candies from other brands and they were inedible. As a livelong afficianodo of Halloween childhood sugar crashes and adult weight gain, this is a generational crime.

It’s a good reminder that shrinkflation often hits quality harder than quantity. Whether there is a direct tariff or not, the reality is that everything costs more to import than it used to. Cross product subsidies exist in every dimension when you’re trying to fill a cargo ship. Your kid’s candy haul this year is one of the purest ways to experience the thousands of sources of consumer surplus lost as we’ve crippled our own economy for no reason but spite and ignorance (all dusted with the unmissable taste of xenophobia and racism).

I used to worry about the first week in the office after Halloween and all the willpower that I was going to have to muster not to sample a Twix, Kit Kat, Snickers, or Twizzler every time I needed to get up from my desk.

Not going to be a problem this year.

“You Can See Everything” and the Confidence Trap

“You Can See Everything” is one of the great film-making experiences of my lifetime. That’s not even a particilularly hot take these days. If you need a recommendation, yes, four stars, you should see it. The singular dominant theme, for my money, was the grand telephone game that “truth” is distilled through as it skips from source to source, medium to medium. By the end of the film you may find that, like me, you have updated your priors a half dozen times, left with your hands up in the air as the crushing weight of subjective reality threatens to abandon you in a fog of nihilism. Then you get home, rewatch the documentary (“The Inventor: Out for Blood”), scroll through a few bullet points of the actual case and remind yourself that no, this person is very much a crook.

But that’s not what I want to talk about. What I want to talk about is confidence.

We are told, repeatedly and with hardly any caveat, that confidence is a good thing. An admirable thing. A sexy thing. But confidence can very much be a trap, particularly if confidence becomes your comparative advantage.

The parable of the young genius has become rooted in the tale of frustrated and constrained greatness. They are precocious and unruly, possibly with a history of mild behavioral issues or sullen solitude. They follow the “normal” track for a few years, often to a prestigious college, where they catch a glimpse of great possibility and simply can’t be held back any longer. They drop out and become an entrepreneur. They pursue investment and promise unblinking greatness and unfathomable innovation with the kind of a committed sureness that only youth can provide.

They are not tradditional frauds, at least not yet, because they believe it everything they say. And why wouldn’t they? They’ve never been wrong. The first time they stepped into an environment where they might be challenged they left before any incontrovertible truths might be controverted. Let’s stop the story here because it rarely actually starts in such a way and, if it does, it usually ends quickly. Which is for the best. It’s not crazy to suggest that the best thing that can happen at this stage is failure. Whether it’s an expert in your field explaining the fallacy underlying your grand promises or venture capitalists simply sniffing out a bad investment, the train stops and you can return to building yourself. You had a good life experience, a new perspective on your own education and skills, and the a greater appreciation for what it means to have something to contribute. No harm, no foul.

But that’s not what happens to a lot of people. Not just undergraduate drop outs either. It’s what can happy to anyone that a market anoints as special. That hype can fuel you until you’ve been running on it for so long you realize, perhaps too late, that you’re no longer selling a product or even yourself. Your selling the story of you. You change your title on LinkedIn to “thought leader”, “visionary”, or “futurist”. You think you are selling yourself, but you’re not because there’s nothing actually there to sell.

And this where the trap is. What you are selling is your confidence in the words coming out of your mouth. The problem is that the words themselves don’t have any value. You don’t know how things work. You don’t know, actually know, biochemistry. Or stochastic modeling. Or tokenization and neural network modeling. You know of them and how to reference them in a manner that obscures your own lack of understanding. The only thing you know, to your creeping dread, is your continued existence in this market is dependent on continuing to dazzle others with the kind of confidence they can only dream of posessing. You’re a carnival barker without a carnival. And eventually someone’s going to walk into an empty tent and they’re going to be pissed.

And that is terrifying.

When you watch “You Can See Everything”, pay attention to how hard they are working to maintain the image that they know what they are talking about. The 3X speed videos and obsession with rapid vocabularly adoption. They know of chemical reagents. And mechanism design. And blood. And lasers. And whatever it is they desperately need to convince people they know about. And notice to whom they scrupulously avoid ever interacting with: anyone with actual scientific or technical expertise. They are always cramming for a exam they didn’t study for. I’d call them dilettantes, but dilettante implies non-trivial, if thin, knowledge about a lot of things. Genuine knowledge. They aren’t dilletantes, they’re frauds.

Imagine Elizabeth Holmes was never sent to prison. What would she be doing right now? It’s pretty obvious to me that she’d be doing exactly the same thing. Selling grand visions wrapped unwavering confidence because that is the only thing she knows how to do. The film trope of the villain confessing to the hero (and the audience) “I’ve come too far” comes to mind.

I’m not saying being confident is going to turn you into a fraud. What I’m saying is that you need to have the skills, knowledge, and other forms of human capital first so that you can offer those skills to the world confidently. Confidence is a useful social lubricant in a market full of imperfect information. It’s useful as a complement, often necessary but never sufficient. To sell naked, untethered confidence itself is to be a confidence person.

You know. A con man.
The modal number of citations is zero (in political science)

I was told when I was a graduate student that the modal published research paper was cited zero times. They then went on to say that the median was one or two, while the mean depended on how good the journal was. Well, someone went looking in political science:

“The modal number of citations to a political science article is zero is true, but most political science articles have more than zero citations is also true.” — @tompepinsky.com

— Omar Wasow (@owasow.bsky.social) 2026-10-19T00:07:13.264Z

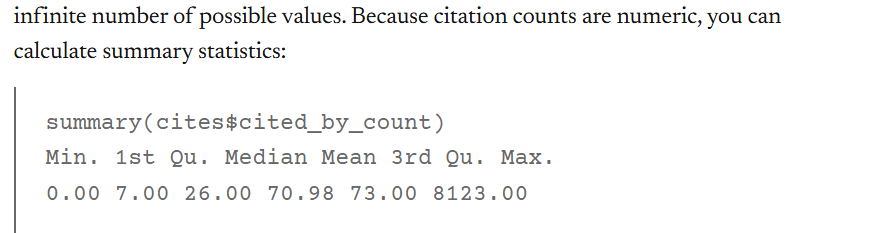
The article provides more basic statistics:

So, at least in political science the median appears to be 26 and the mean 71. That’s a lot higher than I expected, but then poltiical science articles tend to cite far more papers.

My only real thought is this: what question is each number answering? The mode really just let’s you know that the distribution is truncated at zero. It’s a mechanical artifact more than anything. The median, or any of the quantiles, on the other hand, seems only informative if you have a benchmark in your head of at what point an article seems to to be moving the literature. Is 26 substantial, or is it just inframarginal noise for the 90% of articles that don’t really matter? It seems to me all these numbers only matter as fractions of the maximum. If 8123 is the ceiling, how does that change how we interpret a paper with 7 citations?

Most of this seems more like academic appointment accounting, which is almost by definition uninteresting, but it’s a great reminder that statistics have no meaning absent a context that goes beyond other statistics. That said, with just a minimal context, it’s amazing how far knowing nothing but the mean, median, and mode can take you.

Marriages By College Major

[Edited to include divorces]

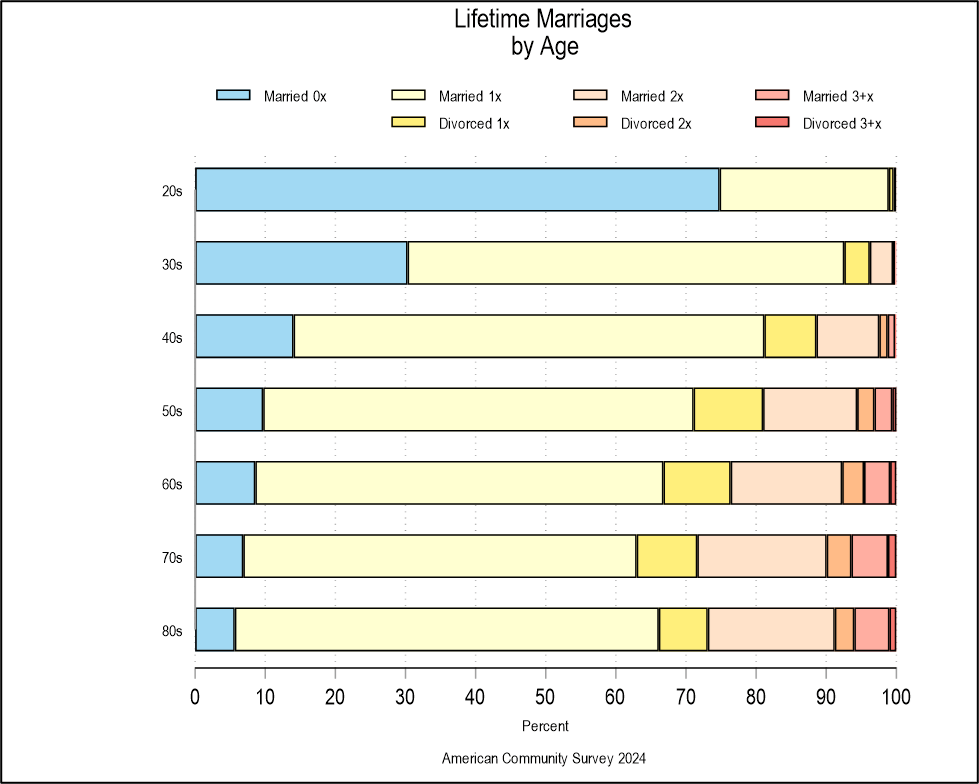
The American Community Survey (ACS) collects information on how many times people have been married.  Using the 2024 ACS, we can see how that changes across ages. Getting married is what we call an absorbing state. Once you get married once, you’ll never be married zero times again. So long as people get married across the age distribution, the proportion of never married people falls.

The same is true for getting married a 2nd time. Then, you’ll never have been married once ever again. While the proportion of people never married must shrink with age, the proportion of people married once can rise. If a few people get divorced or married a 2nd time, but an even bigger number of people get marred for the first time, then the group of people married only once can grow. The ACS stops measuring once someone has been married three times – then it’s “three or more” times. A subsequent divorce the universal absorbing state. Those people never go into another category.

The chart shows the proportion of people by age and the number of times that they’ve been married. Darker hues reflect divorces.* Importantly, this is the snapshot in 2024. So each age group is a cohort snapshot in time. That’s why the proportion of people in their 80s who’ve been married zero or one time is greater than people in their 70s. They’re a different cohort. When the now 80-year-olds were in their 70s, the sum of the blue and light yellow bars were larger than for more recent 70-year-olds.

Continue reading →

Rules aren’t real until they are

This is essentially me revisiting the core concept from last week’s observation that social norms are necessary but not sufficient. Simply read this Michael Lewis essay on the attempted takeover and dissolution of the Institute of Peace by a cadre of DOGE employees who seem little more than a gang of giddy vandals.

You can read it as the narrative is designed. There are good guys resisting a group of marauding (in some cases literal) children. But I think it implies a vastly more important question that we’ve been learning the answer to every day for the last two years: are there rules? If someone does not care to follow the rules, what are the consequences? If someone is creating bespoke rules on the fly with the implied promise that you are taking on great personal risk if you do not follow their rules, are they actually rules or are they something else?

Funny thing about high level governance, it takes on a far greater “fog of war” than a more optimistic observer of institutions might expect. The shape of the current US federal government and the actions it takes appears to be determined far more by the actions of individuals willing and capable of making decisions in a fog of war. That favors people who know that rules aren’t real if they are unenforced. But it also implies the potential for far greater consequences if an authority ever decides to impose consquences for prior transgressions within the fog of war in the interest of resetting precedent for the future.

Some Ways for Investors to Hedge Against Higher Interest Rates

Coming into 2026, all the chatter was about cutting short term rates (which the Fed does directly by fiat). Long term rates, which are generally set by the broader financial markets, were more or less steady, despite the angst over ongoing gigantic federal deficits; the world remained ready to absorb T-bonds, since they are regarded as the most liquid and secure yield-bearing instruments for global finance.

The Iran war has changed all that. The administration, like other administrations in other conflicts over the past half-century, apparently underestimated the adversary’s resilience in the face of bombing. Without further comment on the geopolitics, it suffices for our purpose as investors to assume that there is a good chance that the conflict will continue for some time, and thus oil prices will remain elevated. This works through the system as persistent inflation, even if the immediate effects of consumer gasoline prices are stripped out of the inflation measure. Bond buyers naturally must take into account expected inflation in pricing what rates they are willing to pay for. Also, the unprecedented boom in data center construction is competing for investment dollars. And so, the ten-year T-bond yield has surged from 4% in late February to over 5% now.

As everyone knows, the price of existing long-term fixed debt (e.g., T-bond, corporate bond, etc.) goes down as rate go up, since the existing bond now has to compete in the market with new, higher yielding bonds. Thus, bondholders are crying in their soup, as the price of IEF (ETF that holds 7–10-year T-bonds) has dropped 7% year to date, and the longer-termed (20+ year) TLT is down 10%. Those are big hits to what are thought to be safe, secure holdings.

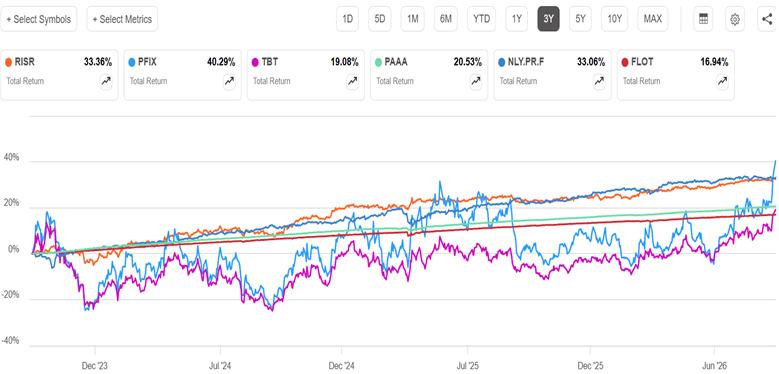
What can investors do to protect themselves against further rate increases? One approach is simply to avoid holding long-term bonds or bond equivalents (fixed-rate debt). You can hold very short term (e.g. 3-month) T-bills, as in the TBIL fund.  Or you can hold instruments with floating rather than fixed rate. For instance, FLOT holds floating-rate government debt, PAAA is a complex but AAA-rated ETF, and many preferred stocks (e.g., NLY-F) also pay some fixed increment above the current market short-term rate. The values of these instruments are relatively insensitive to overall interest rates.

For a more direct hedge, that goes up when long-term bonds values go down (i.e., when rates go up), there are several funds that use derivatives that essentially short T-bond values. TBT is a straightforward, plain vanilla -2X short of the 20+ year T-bond index. With TLT down 10%, TBT is (unsurprisingly) up a full 21% YTD (total return).  PFIX is an actively-managed fund that does something similar, but with wilder swings. It is up a sizzling 30% in 2026, but it was down by 12% in late June. Most advisors seem to recommend TBT or PFIX for tactical trading only, to hold only when you have conviction that rates are going up soon. If the Fed come out swinging tomorrow with a QE bazooka to drive down rates, these stocks will likely crater. That said, if you hold long-term bonds (or fixed-yield preferred stocks, which are like super-long term bonds) in your portfolio, folding in a little PFIX will smooth out the overall portfolio ups and downs. If rates drop and PFIX crashes, your broader bond portfolio should be up.

RISR takes a middle ground, it holds interest-only strips of mortgage-backed securities, so it brings in a decent current yield (5.8% now), and its value rises somewhat as rates go up. Its total return YTD is 6.2% – – maybe not something to brag about at a cocktail party, but it beats CDs.

Here is a 3-year chart of some of these stocks (total return):

Another strategy is to buy individual bonds and hold them to maturity, so you know exactly what the final payout will be.

Saving the best for last: it turns out that if you are a homeowner with a fixed-rate mortgage, you are effective “short” long-term debt, so you “own” a primo hedge against rate increases. Congratulations!

Disclaimer: Nothing here should be considered advice to buy or sell any security.

“Whinging” or Merely Whining?

I have heard the term “whinging” at least twice so far in 2026, both times from fairly sophisticated speakers. I don’t recall ever hearing it before this year. Is this a new trend?

“Whinging” is a British/Commonwealth term that means much the same as “whining,” although (surprisingly) they derive from completely different Old English roots. However, it feels a bit sharper and more dismissive than mere complaining. Thus, whinging is a more intellectual-sounding put-down than whining. And goodness knows how much we need more effective put-downs around here.

ChatGPT informs me that in the realm of finance, the word fills a useful niche. Calling someone a whinger often implies not just that they’re wrong, but that they’re engaging in repetitive, unproductive complaining:

In investing discussions, you’ll often see phrases like: “perma-bear whinging”, “shareholder whinging”, “whinging about management”, “stop whinging and buy the index”

where an American 30 years ago would more likely have written: whining, griping, bellyaching, complaining.

In economics, practitioners often want to distinguish between a legitimate complaint or critique, versus repetitive, emotionally-driven complaining. Thus:

Calling an argument “whinging” implies that the speaker is expressing dissatisfaction without offering analysis or solutions. That rhetorical function is useful in debates over inflation, trade, housing, inequality, central banking, or academic economics itself.

I suppose the first one who unleashes the term “whinging” wins; it is tough to dig out from being buried by a term like that. Knowing all this hopefully leaves you better armed for your next testy exchange over trends or policies.

Political discontinuities

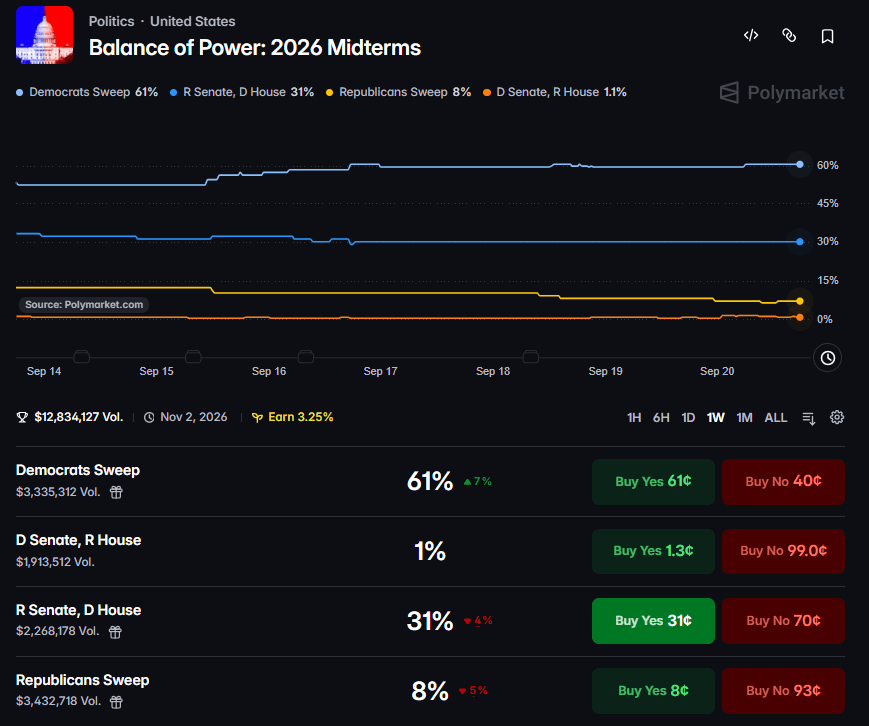
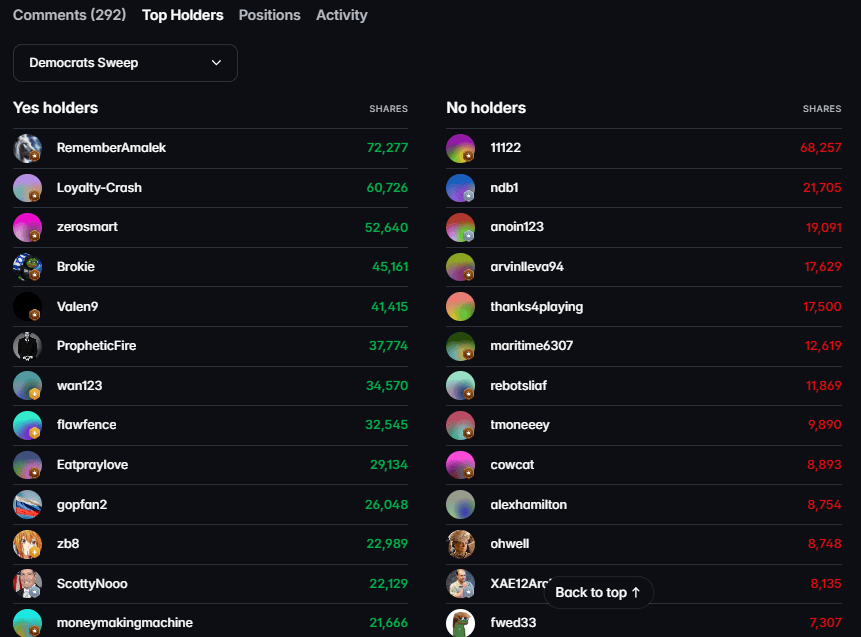
Here’s the Polymarket…market… for bets on the outcome of the US midterms in November over the last 7 days. You’ll notice a 7 percentage point (13% relative to a 54pp baseline) increase in the expected probability of the leading outcome. That’s a very big change, most of which happened over 3 days. In a $12.8 million market where the largest shareholder has $73k on the line, that is a very, very big move.

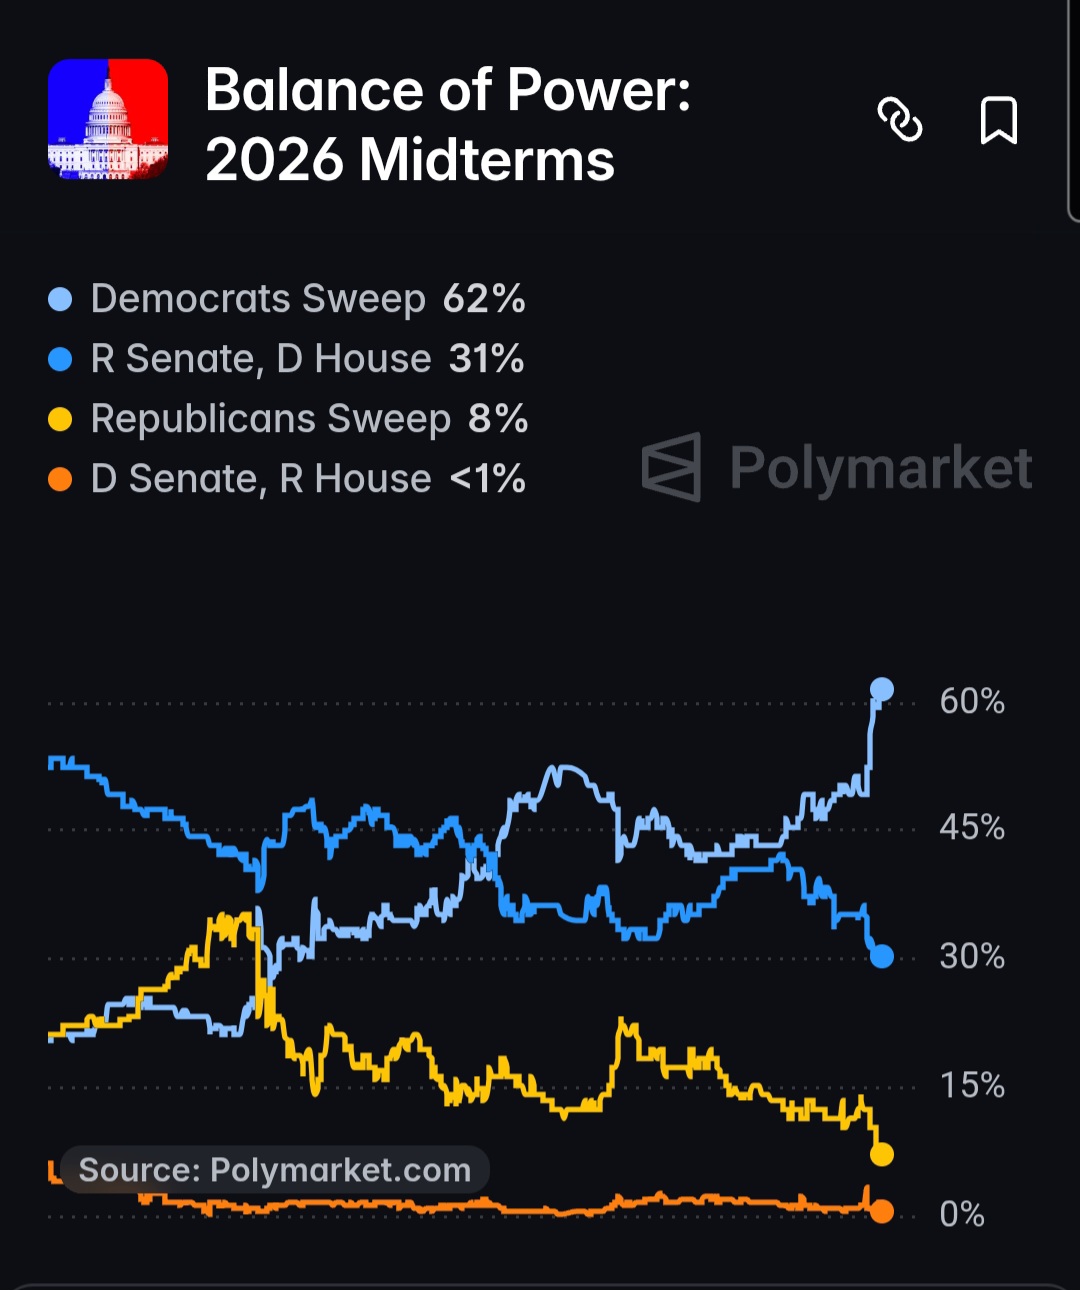
I don’t have any insight into what is happening here, I would simply note that there was to my knowledge no singular news item or event that appears to have sparked this. It’s just a great example of what makes betting markets so interesting. There is some tacit knowledge held by a relatively small number of inviduals, but within and through this market this information has now become at least partially observable in the form of a price. Now, to be extra, super, you just won’t believe how clear about this, I don’t have any insight to lay on top of this, no personal model to share, and I would strongly advise very nearly everyone against trying to participate in this market for personal profit. But, nonetheless, this is useful information. If you made me choose between a world with sports gambling or everything else gambling, I might very well choose “everything else.” At least the world captures some value from the revealed information that is, at least in part, subsidized by enabling a very real and serious addiction. I don’t know that we can say anything similarly positive about sports gambling.

Update: longer timeline as of 10am this morning (7/11 to 9/21)