Bond Market Blows Off Treasury Bond Buyback; Gold and Bitcoin Soar

Scott Bessent used to be a serious financial player. When he was with George Soros’s fund, he helped them make a billion dollars in 1992 by betting against the British pound, and $1.3 billion in 2013 with a bet against the Japanese yen. He also ran his own hedge fund, with as much as $5 billion under management. In 2023-2024 he hitched his wagon to the fortunes of Donald Trump, becoming a large campaign contributor and fundraiser. He was rewarded by being made Treasury Secretary. On January 27, 2025, the U.S. Senate voted to confirm Bessent’s nomination. (The same day, a man with multiple Molotov cocktails and a knife who intended to murder Bessent was arrested at the United States Capitol, an event seemingly lost in the noise of all the attempted assassination attempts against this administration).

The current administration has continued the policy of the previous administration of profligate peacetime federal deficit spending, some 6% of GDP annually, well above the 50-year average of about 3.8%. The only way to finance this spend is to sell more and more Treasury debt. But the more of that debt is out there, the more interest needs to be paid on it. By the mid-2030’s, interest payments will balloon to the point that they, plus mandatory transfer payments like Medicare/Medicaid/Social Security, will consume 100% of tax revenues, with nothing left for discretionary spending (including defense). Being the cabinet officer responsible for financing this mess now is sort of like being CFO of Lehman Brothers in 2008.

Which brings us to the ignominious market response to Bessent’s attempt at bond market intervention last week. As it has become more and more clear to the rest of the world that the U.S. has no intention of reining in its deficit, but instead hopes to deal with it by inflating away the value of the dollar, the market has started to demand greater compensation for holding long-term U.S. debt. If you are wondering why you now have to pay 6.65 % for a 30-year mortgage, wonder no longer. These high interest rates are making it all the more painful for Treasury to fund the deficit.

Secretary Bessent made a surprise announcement last Wednesday that his department would double its maximum purchase of older, less-liquid long-term bonds, from $2 billion per week to $4 billion. The stated purpose of this long-running buyback program is to retire hard-to-trade bonds and replace them with newer, more-liquid bonds. That’s fine, but this snap announcement shortly after its quarterly refunding plan broke with Treasury’s long-held strategy of making ‘regular and predictable’ announcements, and (together with statements by Bessant threatening further intervention) was widely seen as an attempt to talk down the long-term rates.

It worked for about one day. Long term yields initially dipped Wednesday morning by about 0.1%, but by Thursday they were about back to where they were before the announcement. Not only did traders realize the size of the intervention was far too small to move the enormous T-bond market (and would not net decrease T-bonds outstanding), but Treasury’s move became interpreted as a sign of desperation over funding the U.S. deficit. That vibe will not help bring down Treasury bond rates going forward. The value of the dollar dipped on world exchanges, while the price of alternatives such as gold and Bitcoin soared:
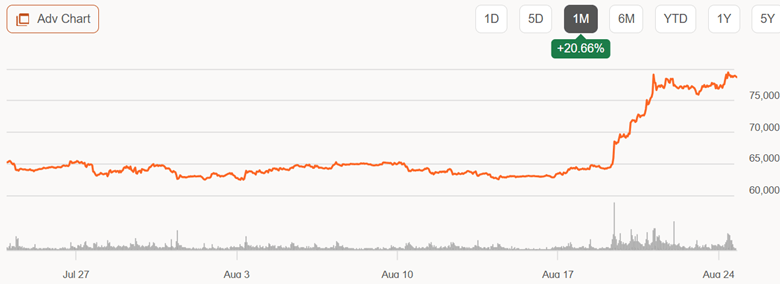
That is a chart of Bitcoin price in the past month. HODLers rejoice, the long crypto winter may be over…
How Scott Bessent Outfoxed Peter Navarro to Get the 90 Day Tariff Pause

Despite the nearly universal outcry, President Trump was standing firm on his massive tariffs. “No backing down”, etc., despite the evaporation of trillions of dollars in stock values. On Tuesday, April 8, White House spokesperson Karoline Leavitt affirmed: “The President was asked and answered this yesterday. He said he’s not considering an extension or delay. I spoke to him before this briefing. That was not his mindset. He expects that these tariffs are going to go into effect.” However, the next day, Wednesday, April 9, Trump announced on his social media platform, Truth Social, that for all countries but China, there would be a 90-day pause in reciprocal tariffs.

What happened here? The common explanations are that (1) the chaos and losses in the markets had finally grown intolerable, or that (2) the president had planned all along to pause the tariff hikes on April 9. I suspect there is some merit to both of these factors – -despite all the prior warnings, I think (1) Trump did not expect such market devastation (he sincerely believes that he is making the American economy great, so why should markets crash?), and also (2) that he had indeed planned to play around with tariff implementations in pursuit of deals.

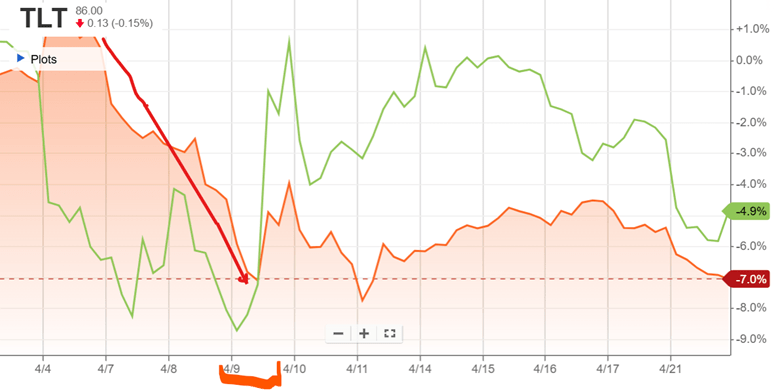
But what some analysts pointed out as a further factor was the drop in the market value of U.S. Treasury bonds, which correlates directly to a rise in interest rates. The actions of the Administration have seemingly caused market participants, especially abroad, to question the risk-free status of U.S. debt. If the government has to pay higher interest on its debt, it is game over, as interest payments will spiral up and consume an ever-higher share of the federal budget. The chart below shows in orange the price movement of the TLT fund, which holds long-term T-bonds, plummeting on April 7, 8, and 9 (red arrow), as an indicator of rising rates. TLT price then shot upwards, along with stocks (the green line is S&P 500 fund SPY) late on April 9, in the relief following the tariff announcement:

As Treasury Secretary, Scott Bessent would be particularly sensitized to the interest rate issue, and able to communicate that to the boss. He has been a successful hedge fund trader and manager, so he understands the plumbing of the system, unlike some other presidential advisors. Up till then, however, economist Peter Navarro, who is ultra-hawkish on tariffs, had had the ear of the president.

So, what did Bessent do? (This is the part that only came to my attention a few days ago, even though technically this is old news). It seems he enlisted the support of Commerce Secretary Lutnick, and adroitly chose a time when Navarro was tied up in a meeting, and barged in on the president in an unscheduled meeting so they could get him alone. And it worked! Evidently, they persuaded him that now was the time to do the clever deal-making thing and issue a pause. It’s a mark of how readily the president can change his mind that his own press spokespeople were unaware of this volte-face, and had to scramble to make sense of it. It is also interesting that cabinet members are resorting to cloak-and-dagger tactics to get policy done.

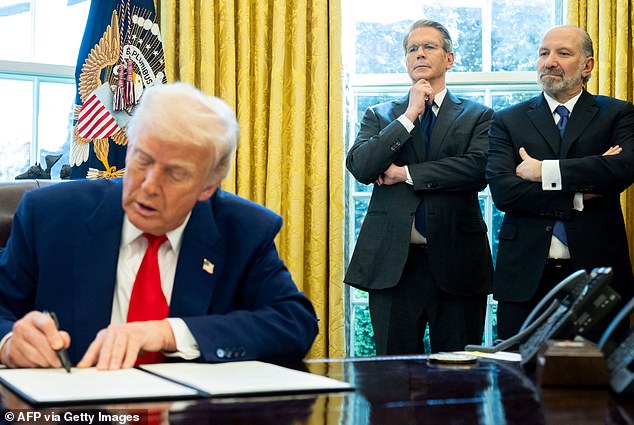
Bessent naturally gave all the credit to the president for the decision, but he and Lutnick had photos taken to show who saved the financial world – for now:

Scott Bessent (standing, left) and Howard Lutnick (right) with President Trump as he signs 90-day pause in reciprocal tariffs.  Source: Daily Mail.

The president’s recent musings about trying to fire the supposedly independent Fed chairman have since contributed to interest rates going back up again, but that is another story.