Get rich or get famous? Edward Thorp vs Myron Scholes

When finance professors publish papers claiming to find inefficiencies in asset markets, my initial reaction is skepticism. The odds are stacked against them to start since asset markets are mostly efficient. Then even if the inefficiency they found is real, shouldn’t they keep that fact to themselves and get rich trading on it?

But listening to a recent interview with Edward Thorp, I realized I shouldn’t entirely discount the possibility that someone would publish a real inefficiency, even a tradeable one. After all, Myron Scholes and Fischer Black did just that when they published the Black-Scholes model in the Journal of Political Economy. This made them famous on Wall Street and in econ/finance academia, and won Scholes the 1997 Nobel Memorial Prize in Economics.

Thorp explained that he had come up with a similar model years earlier, but instead of publishing it, he started a hedge fund and got rich. He says it makes sense that he didn’t share the Nobel Prize, partly because the Black-Scholes model was better than his, but mostly because you should need to publish and share your ideas with the world to get scientific credit for them; his prize was 20% annual returns at his hedge fund.

Why do some opt to get rich, and others to get famous? I’d say academics’ first instinct is to publish everything rather than put it into practice. But Thorp was also an academic, a math professor. Thorp was already famous for publishing a book about how to beat the house at blackjack by counting cards (which is what I knew him for before this interview), so perhaps he valued additional fame less. But he was also already rich from winning at blackjack and from book sales.

Putting ideas into practice can also bring up unanticipated difficulties. When Myron Scholes finally did start working at a hedge fund in 1994 he saw initial success, but by 1998 it had become an embarrassing blunder that inspired the book “When Genius Failed: The Rise and Fall of Long-Term Capital Management”. Scholes may have been better off sticking to academic fame.
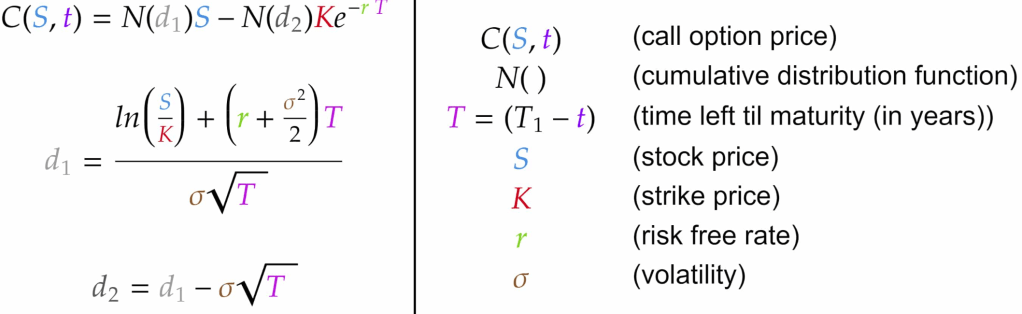
Black-Scholes formula for options pricing. The Efficient Markets Hypothesis says that markets instantly incorporate all public information, but original research like this isn’t public until you publish it, and even then it can take years for market participants to fully incorporate it

Why Many Substance Use Treatment Facilities Don’t Take Insurance

According to the latest data, about one in four facilities doesn’t accept private insurance or Medicaid, and more than half don’t accept Medicare. This makes substance use treatment something of an outlier, since 91% of all US health spending is paid for through insurance. Still, there are many reasons to prefer being paid in cash: insurance might reimburse at low rates, impose administrative hassles, and generally try to tell you how to run things.

Providers generally put up with the hassles of insurance because they see the alternative as not getting paid. But if demand for their services gets high enough that they can stay busy with patients paying cash, they will often try going cash-only. Some try to generate high demand by providing excellent service. Sometimes high demand comes from a growing health crisis, as with opioids.

Demand can also be high relative to supply because supply is restricted. US health care is full of supply restrictions, but in this case I wondered if Certificate of Need laws were playing a role. As we’ve written about previously, CON laws require health care providers in 34 states to get the permission of a government board to certify their “economic necessity” before they can open or expand. But there’s a lot of variation from state to state in what types of services are covered by this requirement; acute hospital beds and long-term care beds are most common. 23 states require substance use treatment facilities to obtain a CON before opening or expanding.

States with Substance Use–Treatment CON Laws in 2020. Created using data from Mitchell, Philpot, and McBirney

How do these laws affect substance use treatment? We didn’t really know- only one academic article had studied substance use CON, finding it led to fewer facilities in CON states. But I’ve studied other types of CON, so I joined forces with Cornell substance use researcher Thanh Lu and my student Patrick Vogt to investigate. The resulting article, “Certificate-of-need laws and substance use treatment“, was just published at Substance Abuse Treatment, Prevention, and Policy. Here’s the quick summary:

We find that CON laws have no statistically significant effect on the number of facilities, beds, or clients and no significant effect on the acceptance of Medicare. However, they reduce the acceptance of private insurance by a statistically significant 6.0%.

Overall I was surprised that CON didn’t significantly affect most of the outcomes we looked at, and appears to be far from the main reason that treatment facilities don’t take insurance. Still, repealing substance use CON would be a simple way to improve access to substance use treatment, particularly since CON doesn’t appear to bring much in the way of offsetting benefits.

Going forward I aim to investigate how these laws affect health outcomes like overdose rates, and to dig more into the text of state laws and regulations to determine exactly what is covered by substance use CON in different states. As the article explains, we identified several errors in the official data sources we were using. This makes me worry there are more errors we didn’t catch, and there are certainly things the sources just don’t specify, like in which states the laws apply to outpatient facilities. So I hope we (or someone else) will have even better work to share in the future, but for now this article is as good as it gets, and we share our data here.

College Major, Marriage, and Children

The American Community Survey began in 2000, and started asking about college majors in 2009, surveying over 3 million Americans per year. This has allowed all sorts of excellent research on how majors affect things like career prospects and income, like this chart from my PhD advisor Doug Webber:

See here for the interactive version of this image

But the ACS asks about all sorts of other outcomes, many of which have yet to be connected to college major. As far as I can tell this was true of marriage and children, though I haven’t searched exhaustively. I say “was true” because a student in my Economics Senior Capstone class at Providence College, Hannah Farrell, has now looked into it.

The overall answer is that those who finished college are much more likely to be married, and somewhat more likely to have children, than those with no college degree. But what if we regress the 39 broad major categories from the ACS (along with controls for age, sex, family income, and unemployment status) on marriage and children? Here’s what Hannah found:

Every major except “military technologies” is significantly more likely than non-college-grads to be married. The smallest effects are from pre-law, ethnic studies, and library science, which are about 7pp more likely to be married than non-grads. The largest effects are from agriculture, theology, and nuclear technology majors, each about 18pp more likely to be married.

For children the story is more mixed; library science majors have 0.18 fewer children on average than non-college-graduates, while many majors have no significant effect (communications, education, math, fine arts). Most majors have more significantly more children than non-college graduates, with the biggest effect coming from Theology and Construction (0.3 more children than non-grads).

In this categorization the ACS lumps lots of majors together, so that economics is classified as “Social Sciences”. When using the more detailed variable that separates it out, Hannah finds that economics majors are 9pp more likely than non-grads to be married, but don’t have significantly more children.

I love teaching the Capstone because I get to learn from the original empirical research the students do. In a typical class one or two students write a paper good enough that it could be published in an academic journal with a bit of polishing, and this was one of them. But its also amazing how many insights remain undiscovered even in heavily-used public datasets like the ACS. We’ve also just started to get good data on specific colleges, see this post on which schools’ graduates are the most and least likely to be married.

Eat 20 Potatoes a Day…. For Science

Several people have tried eating an all-potato diet for a few weeks and reported losing lots of weight with little hunger or effort. Could this be the best diet out there? Or are we only hearing from the rare success stories, while all the people who tried it and failed stay quiet?

Right now we don’t really know, but the people behind the Slime Mold Time Mold blog are trying to find out:

Tl;dr, we’re looking for people to volunteer to eat nothing but potatoes (and a small amount of oil & seasoning) for at least four weeks, and to share their data so we can do an analysis. You can sign up below.

I was surprised to see that they are the ones running this, since they are best known for the “Chemical Hunger” series arguing that the obesity epidemic is largely driven by environmental contaminants like Lithium. The conclusion of that series noted:

Bestselling nutrition books usually have this part where they tell you what you should do differently to lose weight and stay lean. Many of you are probably looking forward to us making a recommendation like this. We hate to buck the trend, but we don’t think there’s much you can do to keep from becoming obese, and not much you can do to drop pounds if you’re already overweight. 

We gotta emphasize just how pervasive the obesity epidemic really is. Some people do lose lots of weight on occasion, it’s true, but in pretty much every group of people everywhere in the world, obesity rates just go up, up, up. We’ll return to our favorite quote from The Lancet: 

“Unlike other major causes of preventable death and disability, such as tobacco use, injuries, and infectious diseases, there are no exemplar populations in which the obesity epidemic has been reversed by public health measures.”

That said, they did still offer some advice based on the contaminant theory that is consistent with the potato diet:

1. — The first thing you should consider is eating more whole foods and/or avoiding highly processed foods. This is pretty standard health advice — we think it’s relevant because it seems pretty clear that food products tend to pick up more contaminants with every step of transportation, packaging, and processing, so eating local, unpackaged, and unprocessed foods should reduce your exposure to most contaminants. 

2. — The second thing you can do is try to eat fewer animal products. Vegetarians and vegans do seem to be slightly leaner than average, but the real reason we recommend this is that we expect many contaminants will bioaccumulate, and so it’s likely that whatever the contaminant, animal products will generally contain more than plants will. So this may not help, but it’s a good bet. 

Overall though I think the idea here is to ignore grand theories and take an empirical approach. The potato diet works surprisingly well anecdotally, so lets just see if it can work on a larger scale. Seems worth a try; I’m sure plenty of my ancestors in Ireland and Northern Maine did 4-week mostly-potato diets and lived to tell about it. You can read more and/or sign up here. Let us know how it goes if you actually try it!

Inflation and GDP Growth Around the World

Kalshi cofounder Tarek Mansour recently shared this graph:

In hindsight it seems like an obvious graph to make, and a good way to teach Aggregate Supply / Aggregate Demand models, but I don’t actually recall seeing much like this. One obvious improvement is to include more countries. I do so below using data from Trading Economics, showing all 182 countries that have recent data on both annual GDP growth and inflation. I also flip the axes to be more consistent with the convention in economics:

This makes clear both the costs and benefits of including all countries. We see just how extreme some outliers are: hyperinflation in Venezuela, Sudan, Lebanon, and Syria; a severe contraction in Libya; and huge growth in Azerbaijan and the Maldives (errors in the data?). But all the more typical countries blend together. So here I zoom in on the more typical countries:

This makes clear the strong aversion to deflation that most countries have. Well over a hundred countries here, many with very low inflation, but only in South Sudan does inflation actually go negative. Real GDP growth does not exhibit the same sharp divide at zero, presumably because its much harder to central banks to fine-tune. Now I try to zoom and enhance one more time:

But things are starting to just get messy, so its time to drop more countries. Here I focus on the 30 largest economies (minus Turkey, which breaks the scale on inflation):

Here we see:

  • Japan is demonstrating stagnation/ low aggregate demand / “running cold”
  • Brazil, Stagflation (negative supply shocks?)
  • Poland, high aggregate demand / running hot
  • Saudi Arabia and Israel, high growth without high inflation (positive supply shocks?)

The US is on the higher end of inflation, and I still think we should be doing more about this, but in this graph we don’t look like a huge outlier. We’re all still working through Covid-related shocks. But the very latest quarterly data today (not reflected in these graphs) showed negative GDP growth in the US, sending us toward the “Stagflation” quadrant and making the Fed’s job much harder.

Fed Dot Plot vs Markets

After their last meeting in March, the Federal Open Market Committee released the summary of economic projections. Most of the variables they project are inherently difficult to predict: GDP, unemployment, inflation. But their forecasts of the Federal Funds rate should be pretty good, since they’re the ones that get to pick what it will be. The median FOMC member thinks the the Federal Funds rate will be just under 2% by the end of 2022.

I said in my last post that the Fed is under-reacting to inflation. Markets seem to agree, but they also think that the Fed will change. Kalshi runs prediction markets on what the Fed Funds rate will be, which they recently started to summarize using this nice curve:

So traders think that the Fed will raise rates faster than the Fed thinks they will, with rates getting to 2.5% by year end. Traders at the Chicago Mercantile Exchange see an even bigger change, with rates at 2.75% by year end, and 3.5% by July 2023 (the longest-term market they offer).

I lean toward the markets on this one; if they are wrong there is plenty of money to be made by betting so.

The Fed is Still Under-Reacting to Inflation

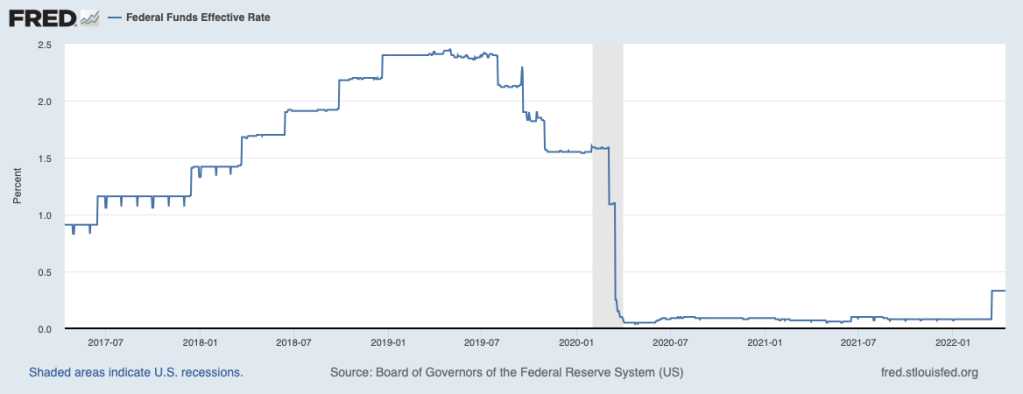
In March the Federal Reserve raised rates for the first time since Covid began:

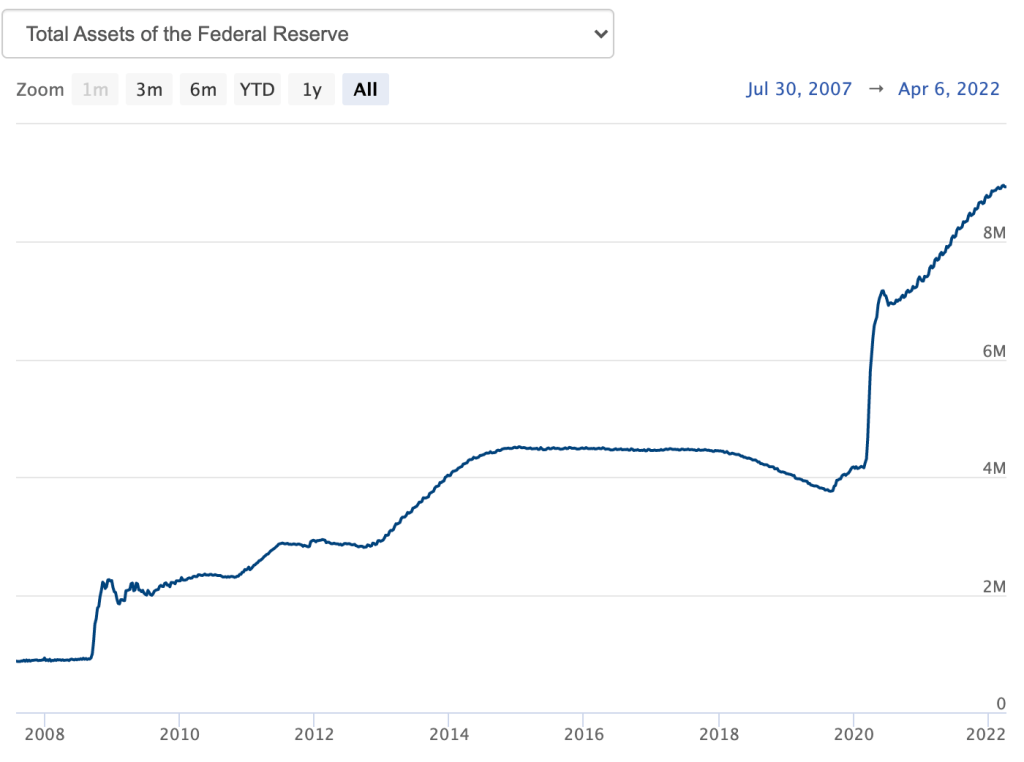
They also began to shrink their balance sheet:

Hard to see but its already down $25 billion from a peak of $8.962 trillion

These moves are in the right direction, but represent a slow start to tackling inflation that is the highest of my lifetime, with the CPI up 8.5% over the last year. While temporary supply constraints are contributing to this, it seems clear to me that excessive aggregate demand is a major driver of this inflation. The labor market has already recovered, with unemployment at 3.6% like it was in late 2019. The Covid-induced output gap is fully eliminated by one standard measure:

But market-based measures of inflation expectations remain high. The TIPS spread predicts that inflation rates over the next 10 years will be much closer to 3% than to the Fed’s target of 2%:

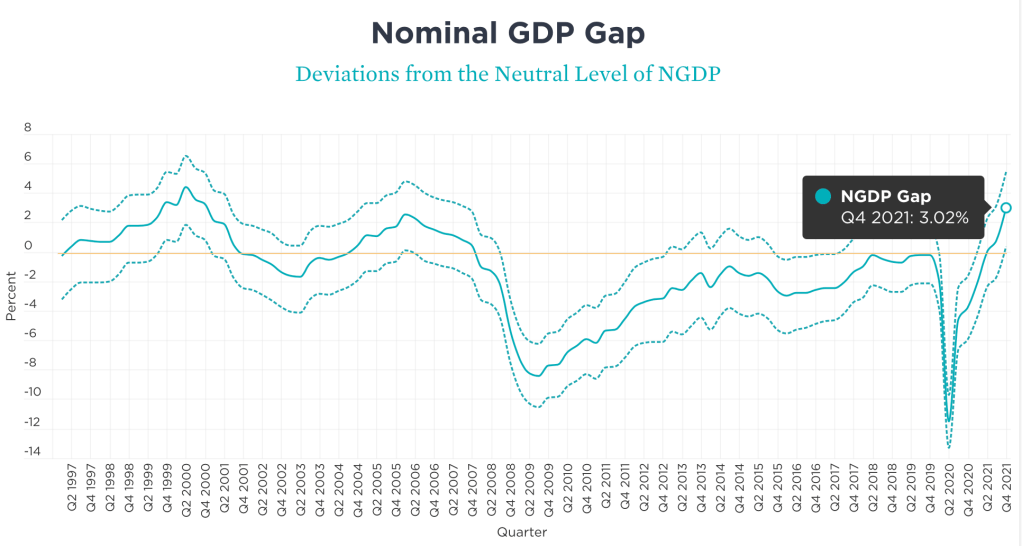
My preferred measure, the NGDP gap, is at 3% (i.e., 3% over the ideal level of 0)

Source: https://www.mercatus.org/publications/monetary-policy/measuring-monetary-policy-ngdp-gap

Overall, its seams clear that Fed policy is currently too loose. The harder question is, what exactly to do about it? How much should they raise rates? The simplest way to answer this is to use the Taylor Rule. Using the version of the rule that Bernanke describes here and using core PCE as the inflation measure (currently just 5.4% yoy, vs 8.5% for headline CPI) implies that the Fed Funds rate should be:

5.4% + 0.5*0% + 0.5*(5.4%-2) + 2 = 9.1%

As Bernanke and many others have explained, you don’t want to take the Taylor rule literally, and the Fed raising rates to 9.1% Volcker-style at their next meeting would be a terrible idea. But keeping the Fed Funds rate under 0.5% would also be a terrible idea. Markets do expect the Fed to keep raising rates this year, but slowly, so that they would be around 2.25% by December. I’ll go on record as worrying that this is too slow, and recommending that they raise rates by at least 0.5% at their next meeting, and continue doing so until market-based measures of medium-run inflation are down to 2%.

Disclaimer: I’m a microeconomist whose last post on inflation was at best only directionally right. Consider this the view of one “insider-outsider” and then go read smarter people like Scott Sumner.

Highlights from EAGx Boston

Last weekend I was at Effective Altruism Global X Boston, a great conference that worked very differently from the academic ones I usually attend. The attendees were younger and the topics were different, but the big innovation was the use of Swapcard to encourage 1-on-1 meetings. At academic conferences I spend most of my time listening to formal presentations or talking to people I already know, but here I talked to 13 new people for a half hour each, and many others more briefly.

That said, the talks I did attend were excellent. Alvea is a 3-month-old company that already has a novel DNA-based Omicron-targeted Covid vaccine in Phase 1 trials. My notes on co-founder Ethan Alley’s talk:

Learning by doing is the way to go. I learned more in 3 months as a founder than 12+ months as an MIT grad student. Like that you have to pay a company $125k to randomize your clinical trial, and they take 8 weeks to do it

Richard Cash talked about the Oral Rehydration Therapy he helped develop that has saved tens of millions of lives. In short, many people who died of diarrheal diseases like Cholera were simply dying from dehydration, and he realized that this can be prevented cheaply and easily in most cases by having them drink a solution of water, glucose, and certain salts (basically Gatorade). He noted that much of the basic research behind this had been done in the US well before it was applied in the developing countries where it has helped most, so it was crucial to simply notice how important and broadly applicable the findings were. On the other hand, some things really did work differently in developing countries; here the medical conventional wisdom was that people shouldn’t eat while they had diarrhea, but if kids are already malnourished it turns out they are better off eating anyway.

Wave is a mobile payment company that is hugely successful in Senegal but has been slow to expand elsewhere. I asked their Chief Technical Officer Ben Kuhn why this was, and his answer made perfect economic sense:

Fixed costs plus local network effects. Fixed costs: need to get approval of a country’s central bank to operate, need to hire local staff, et c. Network effects: our system gets more valuable as more of the people you send money to/from use it, and these are usually within-country. Makes more sense to keep expanding within a country until its nearly totally saturated, and only then move to the next country. There’s also a limit of how much $ we have to expand, especially since we don’t want VCs to control the company.

(My notes, not a verbatim quote)

As I talked to people I was trying to narrow down my post-tenure plans. This didn’t really work, because people gave me good new ideas without convincing me to abandon any of my old ideas. Although I talked to several senior researchers at NGOs, the ideas that stuck with me most came from talking to undergrads, and were all things that sound obvious in hindsight but that I hadn’t actually been planning to do. The one I’ll mention here as a commitment device is to post my research ideas on my website. I have many more paper ideas than I have time to write about them, and I no longer care much about whether I get credit/publications for them or someone else does. This summer I’ll post a list of ideas there, and perhaps a series of posts fleshing them out here.

P.S. If you identify at all with Effective Altruism, I recommend trying to attend a conference. I’m planning to go next to the one in DC in September.

Tradle

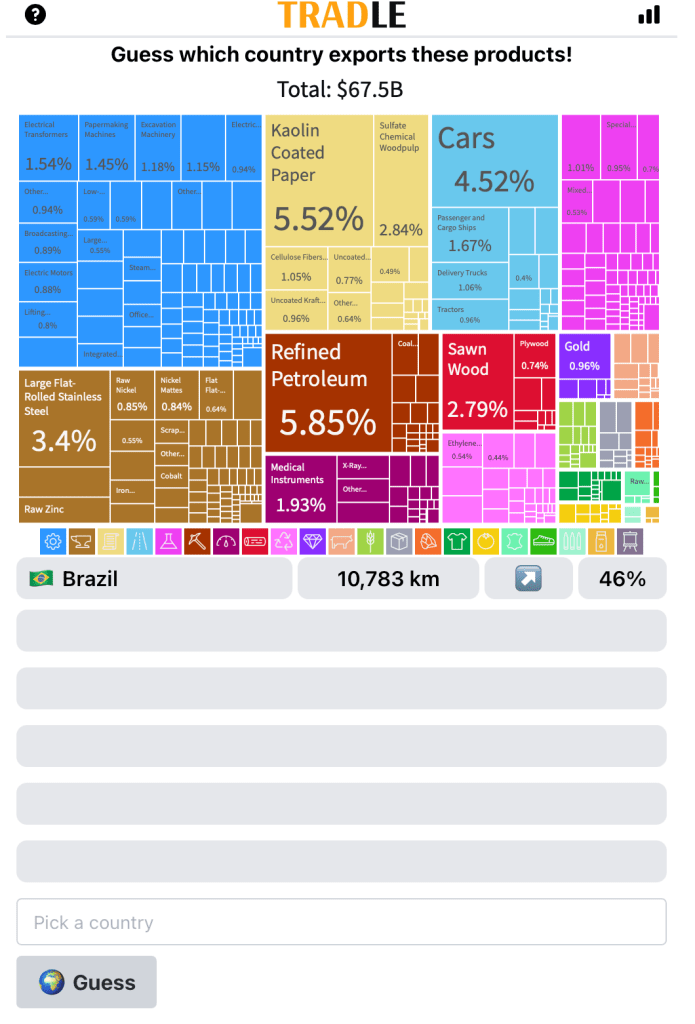
The success of Wordle has inspired a host of similar games. My personal favorite is Worldle, where you guess a country based on its shape. But the one that’s most econ-relevant and the one that I learn the most from is Tradle. You have to guess the country based on its exports:

This one would be a lot easier if I knew what Kaolin is

Its powered by data from the Observatory of Economic Complexity. I recommend checking that out after you try the game.

Post Tenure Agenda

To get anywhere new, you need to step off the treadmill

Before tenure, most academics need to publish their work in peer-reviewed journals if they want to keep their jobs. After tenure, most can publish their work anywhere or nowhere and still keep their jobs. This is a dramatic change in incentives, and you’d think it would lead to dramatic changes in behavior, particularly in a field like economics that studies incentives. In some ways it does- most professors spend less time on research after tenure. But if they do keep doing research, it is generally the same kind they did before- it seems surprisingly rare for economists to change what kind of research they do in response to their changed incentives.

On Monday the President of Providence College told me I’ve been promoted to tenured Associate Professor. I spent much of the last 10 years focused on publishing the 26 academic articles that got me here. So now I’m wondering, what do I change when freed from constraints? I’m planning a pivot toward higher-risk, longer time-horizon, potentially higher-reward research:

Different venues– publish things where people will read them, not where its most prestigious. More white papers, working papers, open access. More blog posts and popular articles, more books– not everything needs to be a peer-reviewed academic paper.

Different topics and methods– focus on work that might have policy impact even if it doesn’t publish well. Do more replications, forecasting and related work that moves us toward being a real science that establishes real truths, even if it doesn’t publish well and might anger some people. Make a point of posting data and code publicly so that its easy for others to use.

New skills– develop generalist skills or a 2nd specialty, ideally in a young/developing field like metascience or superforecasting. Breakthroughs are more likely to come that way, especially for someone not at the top of their 1st field. Create slack so that when big opportunities or needs arise, I’m not “too busy” working on old articles to do anything about it (like I was with Covid in February 2020, Bitcoin mining in 2011, et c). Of course, many of the directions I’m considering (prediction markets, consulting, angel investing, hanging around the state house) might never be “research” even if they do pan out.

The GMU economists are good role models here, though they are such outliers now that people don’t realize they often started their careers focused on publishing journal articles (admittedly some weird ones). For instance, Bryan Caplan’s first book came out 4 years after he got tenure. I’d like to hear more examples of people whose research changed for the better after tenure if you have them. I’d also like to hear about the projects you wish someone not concerned about career risk would take on.

I’m happy to be an Associate Professor at Providence College. While I wouldn’t mind hitting some higher rungs of the academic career/prestige ladder (full professor, endowed chair, NBER invitations, et c), I don’t view these as incentives strong enough to distort my choices the way needing to get a job and get tenure did. Now the goal is simply to do the best work I’m capable of, as I see it. As you can tell I’m pulled in a lot of different directions about what this will look like, but I hope that within 5 years it will be clear I’m doing quality work beyond standard applied microeconomics I’ve been exclusively focused on till now. If not, you’ll have this post to hold over me.

“I consider the “wasting of tenure” to be one of the aesthetic crimes one can commit with a wealthy life, and yet I see it all the time” –Tyler Cowen