Adam Smith and broadening horizons

Last week I had the honor of hosting Vernon Smith at Samford University and then being with him on his second day of the tour in Tuscaloosa, AL.

To introduce Vernon Smith’s new book about Adam Smith, I articulated a point that I had taken from reading Tyler Cowen’s GOAT book. Not all undergraduates have read Adam Smith, so I explained that Adam Smith was one of the first people to have a vision of a growing economy on a global scale. Afterward, I wondered if I had stated everything entirely correctly in my bold assertion. I went to consult with the source material via https://econgoat.ai/en/chat/gpt.

Joy: Does Tyler say that Adam Smith was one of the first people to imagine economic life on a globalized scale and how great the gains from trade could be?

EconGOAT GPT-4: Indeed, Tyler suggests that Adam Smith was one of the pioneering thinkers in envisioning economic life on a global scale and highlighting the immense gains from trade. In discussing Smith’s contributions, Tyler notes how Smith saw trade as a process by which nations could exchange their surplus or “superfluities” for goods they value more. While Smith didn’t quite articulate the theory of comparative advantage—later developed by Ricardo and Torrens—he was certainly heading in the right direction with his understanding of trade. This insight pointed towards a broader, more interconnected economic worldview that has since become central to economic theory (Chapter 8).

Tyler also gives Smith credit for recognizing issues with mercantilist views of trade, which often focused on stockpiling precious metals. Instead, Smith emphasized the expansion of consumption opportunities as the real benefit of trade, emphasizing its potential to enhance global prosperity. Smith’s multifaceted intellectual approach laid the groundwork for thinking about economies beyond just national borders, making him a key figure in the development of global economic thought.

Joy: When I think of a grand global vision prior to Smith, I think about religious leaders and military conquerors. Was Adam Smith the first to think of a grand global vision that fundamentally rests on individual freedom within a tolerant framework of laws and protections from harm?

EconGOAT GPT-4: Tyler acknowledges that Adam Smith played a pivotal role in developing the idea of economic globalization and the gains from trade. However, noting Smith as the absolute first might overlook other contributors. Before Smith, there were philosophers like the Scholastics and early mercantilists who considered economic ideas on a substantial, if not global, scale. The physiocrats, for example, were very much aware of how agriculture and trade could lead to prosperity for nations.

One could argue against Smith’s primacy by pointing out how people have always been aware of trade’s benefits, even if they didn’t articulate it quite as elegantly as Smith did. There’s historical evidence of trade routes as old as human civilization itself, such as the Silk Road or the trade networks of the Phoenicians. These early systems relied on a rudimentary understanding of economies of scale and specialization, even if they weren’t formalized.

Regarding your second point about religious leaders and conquerors, Smith’s vision indeed differs markedly. While others dreamt of unification through conquest or religious means, Smith’s framework empowered individuals to pursue their self-interest within a system of natural laws. This wasn’t just a vision of economic prosperity, but a moral and social vision as well. His “invisible hand” concept implies that individuals, left to their own devices within a safe legal framework, can contribute to the common good more efficiently than any central directive. This is highlighted in Chapter 8, where Tyler discusses Smith’s broader social and philosophical contributions. Smith’s ideas paved the way for modern market economies and significantly influence contemporary thought on economic freedom and globalization.

Joy: Would it be accurate to say that most people in Smith’s time had a very narrow view of the world, indeed hardly thinking beyond the borders of their own regions?

EconGOAT GPT-4: That’s a fair assessment. During Adam Smith’s time in the 18th century, most people indeed had a much narrower view of the world than we do today. Many individuals’ perspectives were limited to their immediate surroundings—villages, towns, or regions. The vastness of the globe, with its diverse cultures, economies, and possibilities for trade, wasn’t as accessible or imaginable to the everyday person as it is now.

Smith’s work in “The Wealth of Nations” was revolutionary in part because it broadened this horizon, not just for economists and policymakers but for anyone interested in economic activity. Smith’s ideas about the division of labor, specialization, and free markets opened up the concept of international trade as a means to prosperity beyond the local economy. His ability to foresee the potential for global interconnectedness in economies was ahead of his time.

I won’t excerpt our entire conversation. I eventually asked how to broaden one’s horizons.

EconGOAT GPT-4: While traveling Europe might seem like a grand adventure ripe for expanding one’s horizons (cue the “Eat, Pray, Love” montage), Adam Smith had reservations about the educational value of the “grand tour,” as it was then known. In Smith’s view, travel often led to “frivolous dissipation” rather than genuine intellectual or moral growth. Instead, he believed that real learning happened through competitive and commercial constraints—the kind you experience when you’re not just sightseeing but actively engaging with a community (Chapter 8).

That was when the bot made a genuinely funny joke about a silly modern book.

Forecasting the Fed: Description Vs Prescription

After raising rates in 2022 to belatedly combat inflation, the FOMC was feeling successful in 2024. They were holding the line and remaining steadfast while many people were getting all in a tizzy about pushing us into a recession. People had been predicting a recession since 2022, and the Fed kept the federal funds rate steady at 5.33% for an entire year. Repeatedly, in the first half of 2024, betting markets were upset that the Fed wasn’t budging. I had friends saying that the time to cut was in 2023 once they saw that Silicon Valley Bank failed. I remained sanguine that rates should not be cut.

I thought that rates should have been higher still given that the labor market was strong. But, I also didn’t think that was going to happen. My forecasts were that the Fed would continue to keep rates unchanged. At 5.33%, inflation would slowly fall and there was plenty of wiggle room for unemployment.

Then, we had a few months of lower inflation. It even went slightly negative in June 2024. Some people were starting to talk about overshooting and the impending recession. I documented my position in August of 2024. Two weeks later, Jerome Powell gave a victory lap of a speech. He said that “The time has come for policy to adjust”.  Instead of discerning whether the FOMC would cut rates, the betting markets switched to specifying whether the cut would be 0.25% or 0.5%. The Fed chose the latter, followed by two more cuts by the end of the year.

I was wrong about the Fed’s policy response function. But why? Was the FOMC worried about the downward employment revisions? That was big news. Did they think that they had inflation whipped? I’m not sure. There was a lot of buzz about having stuck the soft landing. In late 2024, I leaned toward the theory that the Fed was concerned about employment. Like, they thought that we had been doing better until then.

Continue reading →

National Survey of Children’s Health Backup

The NSCH is the latest casualty of the new administration taking down major datasets from government websites. Between Archive.org and what I had downloaded for old projects, I was able to get all the 2016-2023 topical NSCH files and post them on an Open Science Foundation page.

I took this as a chance to improve the data- the government previously only made the topical Public Use Files available in SAS and Stata formats one year at a time, so I added a merged version for all available years in both Stata and Excel formats.

I hope and expect that the National Survey Children’s Health will be back up at official websites soon. But I expect that other datasets will be taken down permanently, so now is the time to download what you think you might need and add it to your data hoard– especially if you want anything from the Department of Education.

2024 Labor Market: Not the Greatest Ever, But Pretty, Pretty Good

At the end of 2023 I asked: was 2023 the greatest labor market in US history? I presented some data to suggest that, yes, maybe, probably, it was the greatest labor market in US history.

That post was partly inspired by critics of the unemployment rate as a broad measure of labor market utilization. Yes, the UR isn’t perfect, and it misses some things. But other measures of labor force performance tend to move with the UR, and so it’s still a useful measure. 2023 saw not only some of the lowest unemployment rates in US history (rivaling the late 1960s), but also some of the highest employment rates (only beat by the late 1990s). Wage growth was also robust. And other measures of unemployment, such as the much broader U-6 rate and the Insured Unemployment Rate, were also at record low levels (though the data doesn’t go back as far).

Today I learned about a very interesting, though I think probably confusing, measure called the “true unemployment rate.” Produced by the Ludwig Institute, it uses the same underlying data source (the CPS) that the BLS uses to calculate the unemployment rate and other measures mentioned above. This “true” rate is definitely intended to shock you: it suggests that 25 percent of the workforce is “unemployed.”

But they aren’t actually measuring unemployment. What they are doing, in a sense, is combining a very broad measure of labor underutilization (like the U-6 rate mentioned above) with a measure that is similar to the poverty rate (but not exactly). They count people as unemployed if they are part-time workers, but would like to work full-time (U-6 does this). But they also count you as unemployed if you earn under $25,000 per year. Or if you don’t work at all, you are counted as unemployed — even if you aren’t trying to find a job (such as being a student, a homemaker, disabled, etc.). The entire working age population (ages 16+, though they don’t tell us the upper limit, we can probably assume 64) is the denominator in this calculation.

So again, this is attempting to combine a broad measure of employment with a poverty measure (though here poverty is defined by your own wage, rather than your household income). So of course you will get a bigger number than the official unemployment rate (or even the U-6 rate).

But here’s the thing: even with this much broader definition, the US labor market was still at record lows in 2023! Given this new information I learned, and that we are now through 2024, I decided to update the table from my previous post:

From this updated table, we see that by almost every measure, 2023 was an excellent year for the US labor market. The only measure where it slightly lags is the prime-age employment rate, which was a bit higher in the late 1990s/2000. Real wage growth was also quite strong in 2023, despite still having some lingering high inflation from the 2021-22 surge.

How about 2024? By almost all of these measures, 2024 was slightly worse than 2023. And still, 2024 was a good year. A pretty, pretty good year for the labor market. And while the UR ticked up in the middle of the year, it has since come back down a bit and is now right at 4%. As for the “true” unemployment rate, it followed a similar pattern, ticking up a bit in mid-2024, but by December it was back slightly below the level from December 2023.

Alternative “true” measures of the economy rarely give us any additional information than the standard measures — other than a shocking, but confusing, headline number.

Why Low Returns Are Predicted for Stocks Over the Next Decade

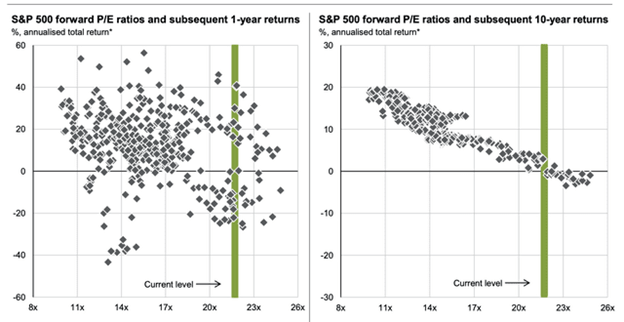
I saw this scary-looking graphic of S&P 500 returns versus price/earnings (P/E) ratios a couple of days ago:

JPMorgan

The left-hand side shows that there is very little correlation between the current forward P/E ratio and the returns in the next year; as we have seen in the past few years, and canonically in say 1995-1999, market euphoria can commonly carry over from one year to the next. (See here for discussion of momentum effect in stock prices). So, on this basis, the current sky-high P/E should give us no concern about returns in the next year.

However, the right-hand side is sobering. It shows a very strong tendency for poor ten-year returns if the current P/E is high. In fact, this chart suggests a ten-year return of near zero, starting with the current market pricing. Various financial institutions are likewise forecasting a decade of muted returns [1].

The classic optimistic-but-naïve response to unwelcome facts like these is to argue, “But this time it’s different.” I am old enough to remember those claims circa 1999-2000 as P/E’s soared to ridiculous heights. Back then, it was “The internet will change EVERYTHING!”.  By that, the optimists meant that within a very few years, tech companies would find ways to make huge and ever-growing profits from the internet. Although the internet steadily became a more important part of life, the rapid, huge monetization did not happen, and so the stock market crashed in 2000 and took around ten years to recover.

A big reason for the lack of early monetization was the lack of exclusive “moats” around the early internet businesses. Pets.com was doomed from the start, because anyone could also slap together a competing site to sell dog food over the internet. The companies that are now reaping huge profits from the internet are those like Google and Meta (Facebook) and Amazon that have established quasi-monopolies in their niches.

The current mantra is, “Artificial intelligence will change EVERYTHING!” It is interesting to note that the same challenge to monetization is evident. ChatGPT cannot make a profit because customers are not willing to pay big for its chatbot, when there are multiple competing chatbots giving away their services for practically free. Again, no moat, at least at this level of AI. (If Zuck succeeds in developing agentic AI that can displace expensive software engineers, companies may pay Meta bigly for the glorious ability to lay off their employees).

My reaction to this dire ten-year prognostication is two-fold. First, I have a relatively high fraction of my portfolio in securities which simply pump out cash. I have written about these here and here. With these investments, I don’t much care what stock prices do, since I am not relying on some greater fool to pay me a higher price for my shares than I paid. All I care is that those dividends keep rolling in.

My other reaction is…this time it may be different (!), for the following reason: a huge fraction of the S&P 500 valuation is now occupied by the big tech companies. Unlike in 2000, these companies are actually making money, gobs of money, and more money every year. It is common, and indeed rational, to value (on a P/E basis) firms with growing profits more highly than firms with stagnant earnings. Yes, Nvidia has a really high P/E of 43, but its price to earnings-growth (PEG) ratio is about 1.2, which is actually pretty low for a growth company.

So, with a reasonable chunk of my portfolio, I will continue to party like it’s 1999.

[1] Here is a blurb from the Llama 3.1 chatbot offered for free in my Brave browser, summarizing the muted market outlook:

Financial institutions are forecasting lower stock market returns over the next decade compared to recent historical performance. According to Schwab’s 2025 Long-Term Capital Market Expectations, U.S. large cap equities are expected to deliver annualized returns of 6% over the next decade, while international developed market equities are projected to slightly outperform at 7.1%.1 However, Goldman Sachs predicts a more modest outlook, with the S&P 500 expected to return around 3% annually over the next decade, within a range of –1% and 7%.42 Vanguard’s forecasts also indicate a decline in expected returns, with U.S. equities falling to a range of 2.8% to 4.8% annually. These forecasts suggest that investors may face a period of lower returns compared to the past decade’s 13% annualized total return.

Is there a competitive threat to the NBA?

On its merits, the dumbest trade in the history of the NBA, if not modern professional sports, occurred last week. There is no shortage of content explaining why the trading of Luka Doncic for Anthony Davis was a poorly exectuted trade in which the Dallas Mavericks got pennies on the dollar from the Los Angeles Lakers. Even if you subscribe to the theory that there is a signficant unobserved defect in Doncic motivating Dallas to avoid what would have been a new $350m contract, the fact remains they could have traded him for a host of draft assets far in excess of the value of Anthony Davis.

This has unsurprisingly spawned a cottage industry of conspiracy theories. The most popular is that the new Dallas owners are maneuvering for a casino license, but my favoirte is that the owners have inside information that a new Saudi Arabian, LIV Golf-style, rival league is in the works (I can’t find a post where such a thing was suggested. If you have a link, please put it in the comments). I have observed **ZERO** evidence for such a thing…but that doesn’t mean it doesn’t make for an excellent thought experiment, particularly since I think Saudi “sport washing” is largely motivated by a desire to diversify out of the oil business. A couple actual facts:

  1. LIV Golf
    • The conceit of LIV golf was that the PGA Tour had a global monopoly based on nothing but i) high start up costs, ii) historical capital including brand recognition, and iii) the network effects born of having every top player in the world currently participating. The Saudi Arabia’s Public Investment Fund (PIF) made the audacious move to commit no less than $2 billion in winnings and up front fees to players to switch to their rival event series. The PGA and PIF are multiple years deep into trying to negotiate a merger with the LIV tour.
  2. The Saudi Pro League (Soccer/Football)
    • The PIF took a 75% ownership stake in the league and immediately went plundering for talent around the world, signing late career-stage (but still very good) Christiano Ronaldo and a host of other excellent players, often tripling their salaries
    • They didn’t fully ignore existing contract rights, probably because of a hope to eventually integrate into the broader international soccer structure.
  3. The basketball labor pool is no longer American-dominated
    • The best player in the world is Serbian.
    • 36% of NBA players were born outside the United States.
  4. The ABA was cooler than the NBA
    • The last time the NBA faced competitiion from a rival league, they absorbed it in 1976.
    • The WHA was in many ways cooler than the NHL as well. The NHL similarly merged with them.
  5. NBA players are paid far less than their market value
    • The owners and players union have a collectively bargained team salary cap of $140.6 million per season. The highest single player salary is $56 million.
    • Young players are so underpaid relative to their value their contracts are some of the most valuable assets because they give you a competitive advantage under the salary cap. No one ever seems to bring up how much the NBA Players Unions allows owners to underpay incoming players.

So, let’s put it this way. Why *wouldn’t* the Saudi Arabian PIF invest $5 billion in creating a rival basketball league? Remember, the Saudi soccer league successfully acquired some of the best players in the world from a sport that a) has nearly zero restrictions on salary (“financial fair play” rules not withstanding) and b) is, quite frankly, miserable to play with players that are below your level. What sort of havoc could they wreak on the NBA?

They could at least double the salaries of every single non-American player in a league that, in many cases, would be a shorter flight to their home countries. For comparative pennies they could fill out the rosters tripling the salaries of all of the best players in the Spanish and Italian leagues. As the PGA learned, there are no doubt a couple dozen top American players that would be happy to play abroad for 200% salary bumps. Would a single season of Lebron be worth a half billion dollars to a nascent league? Victor Wembanyama is currently the single most valuable player asset in the NBA and is getting paid $12.77million a year. A Saudi league could start him at $60m a year today and not bat an eye. What is the career arc of a sport-altering talent worth from beginning to end for a global entertainment product?

How is this relevant to the Doncic-Davis trade?

What exactly are the incentives for players, especially non-American players, and the PIF to honor existing contracts? Having a top 5 player under contract has exactly zero value if they don’t intend to honor the deal. Let’s go further – what exactly is the value of a draft pick if the cartel enforcing your “right” to be the sole employment option for player if that draft right isn’t honored by a rival league offering higher wages? The entire market value of NBA assets is predicated on the pre-existing property rights surrounding contracts and draft status. The calculus underlying those values is made astonishingly complex by the byzantine rules of the NBA salary cap. It’s all very confusing, but also taken entirely for granted in the ecosystem of analysts inside and pundits outside the system.

What happens if a rival shows up with no regard for the pre-existing institutions of the NBA cartel?

Every NBA institution would be up for grabs. The salary cap? It threatens the ability to retain the top talent. The draft? Why would rookies accept pennies on the dollar and a single possible employer? Why would someone who grew up in Sao Paulo want to take an 80% paycut for the privlege of playing in a town they’ve never heard of? I’m sure people who grew up in Los Angeles would prefer San Antonio to Riyadh, but *how much* would they prefer it? Is it a $100 million preference?

There is no shortage of irony in European sports existing in largely unbridled market competition while American sports leagues putter on as little socialist cartels. The thing about cartels is that all the antitrust exemptions in the world won’t protect you from competition if you’re too profitable. And the NBA is very profitable.

Again, I don’t think there is reason yet to believe that the Dallas Mavericks made anything other than a foolish, no good, very bad business decision. But that doesn’t mean that it isn’t also the first sign that NBA owners aren’t 100% sure how to value their current assets going forward. This deal wasn’t just foolish, it was weird. When market prices get weird, big changes aren’t usually far off.

Telling Stories at the Campfire

This week has been busy with the enjoyable task of hosting a distinguished economist in Alabama. I can only briefly follow up on my campfire post. (Yes, this is apropos of everything.)

I do not usually use LLMs to write even part of my posts but since I am pressed for time, I will just take this as a chance to assess Claude. I pay for Claude and Grok, currently. Both of those subscriptions resulted from a particular moment when I thought I could get a particular task done with them and was in a hurry. If I could do it all over again, I would undo those subs, I think, and go more in on the OpenAI Pro products.

Prompt: Finger wagging is surprisingly ineffective; telling a compelling story is surprisingly effective. Can you expand that out into a paragraph for a blog?

Claude response: The art of persuasion often defies our intuitive assumptions. While many of us default to stern lectures and admonishing fingers when trying to change minds, research consistently shows this approach tends to backfire, causing people to become defensive and dig deeper into their existing beliefs. What proves remarkably more effective is the simple act of storytelling. When we encounter a compelling narrative, our brains react differently than they do to facts and figures alone – we become emotionally invested, our neural patterns sync with the story’s flow, and we naturally lower our defensive barriers. Stories create a shared experience that bridges ideological divides, allowing new ideas to take root not through force, but through the gentle power of narrative empathy. This explains why parables and fables have been humanity’s preferred teaching tools for millennia, while memories of being lectured rarely inspire lasting change.

Claude is always a little too verbose, in my opinion. Still, the logic and grammar are good. The machines can write.

I might write more soon about how AI’s used narrative to influence humans in the novel The Diamond Age.

RGDP Underestimates Welfare

Like many Principles of Macroeconomics courses, mine begins with an introduction to GDP. We motivate RGDP as a measure of economic activity and NGDP as an indicator of income or total expenditures. But how does more RGDP imply that we are better off, even materially? One entirely appropriate answer is that the quantities of output are greater. Given some population, greater output means more final goods and services per person. So, our real income increases.  But what else can we say?

First, after adjusting for price changes, we can say that GDP underestimates the value that people place on goods and services that are transacted in markets. Given that 1) demand slopes down and 2) transactions are consensual, it stands to reason that everyone pays no more than their maximum value for things. This implies that people’s willingness to pay for goods surpasses their actual expenditures. Therefore, RGDP is a lower bound to the economic benefits that people enjoy. Without knowing the marginal value that people place on all quantities less than those that they actually buy, we have no idea how much more value is actually provided in our economy.

Continue reading →

Triumph of the Data Hoarders

Several major datasets produced by the federal government went offline this week. Some, like the Behavioral Risk Factor Surveillance Survey and the American Community Survey, are now back online; probably most others will soon join them. But some datasets that the current administration considers too DEI-inflected could stay down indefinitely.

This serves as a reminder of the value of redundancy- keeping datasets on multiple sites as well as in local storage. Because you never really know when one site will go down- whether due to ideological changes, mistakes, natural disasters, or key personnel moving on.

External hard drives are an affordable option for anyone who wants to build up their own local data hoard going forward. The Open Science Foundation site allows you to upload datasets up to 50 GB to share publicly; that’s how I’ve been sharing cleaned-up versions of the BRFSS, state-levle NSDUH, National Health Expenditure Accounts, Statistics of US Business, and more. If you have a dataset that isn’t online anywhere, or one that you’ve cleaned or improved to the point it is better than the versions currently online, I encourage you to post it on OSF.

If you are currently looking for a federal dataset that got taken down, some good places to check are IPUMS, NBER, Archive.org, or my data page. PolicyMap has posted some of the federal datasets that seem particularly likely to stay down; if you know of other pages hosting federal datasets that have been taken down, please share them in the comments.

Was the US at Our Richest in the 1890s?

Donald Trump has repeatedly said that the US was at our “richest” or “wealthiest” in the high-tariff period from 1870-1913, and sometimes he says more specifically in the 1890s. Is this true?

First, in terms of personal income or wealth, this is nowhere near true. I’ve looked at the purchasing power of wages in the 1890s in a prior post, and Ernie Tedeschi recently put together data on average wealth back to the 1880s. As you can probably guess, by these measures Trump is quite clearly wrong.

So what might he mean?

One possibility is tax revenue, since he often says this in the context of tariffs versus an income tax. Broadly this also can’t be true, as federal revenue was just about 3% of GDP in the 1890s, but is around 16% in recent years.

But perhaps it is true in a narrower sense, if we look at taxes collected relative to the country’s spending needs. Trump has referenced the “Great Tariff Debate of 1888” which he summarized as “the debate was: We didn’t know what to do with all of the money we were making. We were so rich.” Indeed, this characterization is not completely wrong. As economic historian and trade expert Doug Irwin has summarized the debate: “The two main political parties agreed that a significant reduction of the budget surplus was an urgent priority. The Republicans and the Democrats also agreed that a large expansion in government expenditures was undesirable.” The difference was just over how to reduce surpluses: do we lower or raise tariffs?

It does seem that in Trump’s mind being “rich” in this period was about budget surpluses. Let’s look at the data (I have truncated the y-axis so you can actually read it without the WW1 deficits distorting the picture, but they were huge: over 200% of revenues!):

It is certainly true that under parts of the high-tariff period, we did collect a lot of revenue from tariffs! In some years, federal surpluses were over 1% of GDP and 30% of revenues collected. But notice that this is not true during Trump’s favored decade, the 1890s. Following the McKinley Tariff of 1890, tariff revenue fell sharply (though probably not likely due to the tariff rates, but due to moving items like sugar to the duty-free list, as Irwin points out). The 1890s were not a decade of being “rich” with tariff revenue and surpluses.

Finally, also notice that during the 1920s the US once again had large budget surpluses. The income tax was still fairly new in the 1920s, but it raised around 40-50% of federal revenue during that decade. By the Trump standard, we (the US federal government) were once again “rich” in the 1920s — this is true even after the tax cuts of the 1920s, which eventually reduced the top rate to 25% from the high of 73% during WW1.

If we define a country as being “rich” when it runs large budget surpluses, the US was indeed rich by this standard in the 1870s and 1880s (though not the 1890s). But it was rich again by this standard in the 1920s. This is just a function of government revenue growing faster than government spending. And the growth of revenue during the 1870s and 1880s was largely driven by a rise in internal revenue — specifically, excise taxes on alcohol and tobacco (these taxes largely didn’t exist before the Civil War).

1890 was the last year of big surpluses in the nineteenth century, and in that year the federal government spent $318 million. Tariff revenue (customs) was just $230 million. There was only a surplus in that year because the federal government also collected $108 million of alcohol excise taxes and $34 million of tobacco excise taxes. In fact, throughout the period 1870-1899, tariff revenues are never enough to cover all of federal spending, though they do hit 80% in a few years (source: Historical Statistics of the US, Tables Ea584-587, Ea588-593, and Ea594-608):

One more thing: in some of these speeches, Trump blames the Great Depression on the switch from tariffs to income taxes. In addition to there really being no theory for why this would be the case, it just doesn’t line up with the facts. The 1890s were plagued by financial crises and recessions. The 1920s (the first decade of experience with the income tax) was a period of growth (a few short downturns) and as we saw above, large budget surpluses. The Great Depression had other causes.