Funds Paying “Return of Capital” Give You (Sort of) Tax-Free Income

The stock of an individual company like AT&T, or a stock fund, often pays a dividend or distribution. Typically, these dividends are taxed as income. If you buy shares of a fund like MUNI that hold municipal bonds from U.S. states and cities, the dividends from that are not taxed by the feds (they are taxed on state income taxes). That’s nice, but the yield from a muni fund MUNI is only 3.3%, and the share price of MUNI drifts around with bond prices; it does not grow like the S&P500 stocks do.

What if there was a way to get highish dividends that are not taxed, at least not in the short term? There is. Funds classify their distributions or dividends in various categories. Net investment income or short-term capital gains are taxed like interest or ordinary income (highest rates). Qualified dividends or long-term capital gain returns are taxed at a lower rate. But “Return of Capital” (ROC) distributions are not taxed at all, when you receive them. (The accounting fiction is that ROC is simply your own investment money being handed back to you, rather than you getting interest or profit, which is why it is not taxed).

ROC only catches up with you when you sell your shares. Every dollar you pocket in ROC goes to lower the formal cost basis of your shares, so that increases the capital gains tax you pay when you sell.  Still, it can mean you defer paying taxes for many years, and when you do sell after many years, you will pay mainly long-term capital gains. Long-term capital gains have relatively low tax rates, and sometimes can be offset with capital losses elsewhere. So, this is a pretty good deal overall. All this only benefits you if you are holding these stocks in a taxable account, not in an IRA.

And, there are ways to not sell your shares, and hence never pay an inflated capital gains tax from all that ROC. One way not to sell your shares is to die (!). Your heirs inherit the funds at the current market value i (stepped-up basis”), without having to pay capital gains. So older folks do deliberately lard up their portfolios with ROC-paying funds or stocks, to leave to their heirs.

Another tactic is to donate the shares to charity. As I understand it, the donation gets valued at current market price, regardless of your cost basis. So, for instance, you might buy shares of XYZ fund at $100/share, collect say $50 in untaxed ROC over the next five years, and then donate the shares for a tax deduction at say $100/share (if their market price had not changed in five years). Obviously, this is only attractive if you wanted to make a charitable donation anyway.

OK, what are some funds or stocks that pay out ROC? There are number of funds which hold stocks, and write (sell) call options on them to generate income. (See here on selling options). Some (not all) of these funds pay out as mainly ROC, and are discussed here. SPYI and ETV are plain vanilla funds holding a basket of S&P500 type stocks, usually with a skew towards tech, and selling call options on them. (Or usually, selling options on an index like SPX or QQQ).  SPYI is currently paying about 11.5% yield, and ETV about 9%, both mainly ROC. ETV happens to be a closed-end fund, which can be good or bad, depending on whether you buy in when the share price is at a discount or premium to the asset value. Right now, ETV is at about a 5% discount, so it is a relatively good time to buy.

It is essential to note with these high yielding funds, the raw yield is practically meaningless. You have to look at total return, which factors in stock price over time as well as cash payout. The reason is that some funds “cheat” by paying huge yields, which sucks in investors, but those yields are not really earned by the fund, so those big payouts gradually deplete the fund’s assets.

FEPI holds an equally-weighted basket of fifteen tech stocks, and sell options on them. By selling options on individual stocks, the options income is huge; FEPI pays about 20% yield. The share price bounces around heavily, being so narrowly concentrated. If tech has a bad/good day, FEPI goes way down/up. QDTE also pays about 20%. It has a more novel strategy, selling “zero-day” options, which I won’t try to explain here. It has only been running about 6 months, but is doing OK.

A problem with all these option-selling funds is that their asset value goes down 10% if the underlying stocks go down 10%, but if stocks recover fast, the value of the funds typically do not recover as much. So, the share price of these funds keeps slipping below the price of a plain stock fund like SPY or QQQ. Now, if stocks go up (which they do most years), the price of an options fund can also go up, just not as much. The lag of these options fund is significant enough that on a total return basis (i.e. with dividends and stock price included), they usually lag behind just holding the stocks. Thus, the only reason to hold these funds is to harvest the tax-free ROC, or if you have a reason to want to generate steady income without selling off stocks.

Some 1-year total returns:

SPY        26.7%   Plain S&P 500  stock fund

SPYI       8.5%      Option fund

ETV        8.8%      Option fund

FEPI       20.2%   Option fund

QDPL     25.9%   Quadruple stock divi fund          

(Note, it is a little random that FEPI looked so good and SPYI and ETV looked poor in the past 12 months; that is not always the case. In the past 6 months, FEPI fared much worse than SPYI and ETV, which only lagged SPY by 1-2%). Some other newish option funds that pay mainly ROC are ISPY (8% yield, sells daily options, very little return lag) and three more with fairly low return drag: XDTE and QDTE (~20% yields, daily options on S&P500 and on NASDAQ 100); QYLG (6% yield; monthly options on half of NASDAQ 100).

Another fund I became aware of recently that pays mainly ROC is QDPL. It does not sell options, so it does not suffer the return lag the other funds do. It uses a futures strategy to take about 15% of the fund assets to garner roughly 4X the normal stock dividends of the S&P500 stocks. It only yields about 5.5%, but its total return keeps up pretty well with SPY. I like this one, and am including it in my portfolio with some of the options funds discussed above.

A whole other class of stocks that pay out mainly ROC is limited partnerships. These are common, e.g., among oil and gas pipeline companies like ET and EPD. These pay 7-8% and also are having strong share price appreciation. But they issue K-1 tax forms, which most mortals don’t want to deal with (I don’t).

As usual, this discussion does not constitute advice to buy or sell any security.
Why was the Democratic Convention so patriotic?

Election season tends to spoil watching sports that have ad breaks, but one positive (for me at least) is that there is constant pedagogical fodder for my public choice & political economy class, particularly with regards to the median voter thereom. The biggest gripe with the MVT that people just insist on bringing up is the minor detail that it is obviously always wrong, which just misses the point entirely. Politics is neither fast nor slow. It’s more geological in that is slow to change until it isn’t. It can be painfully slow to watch coalitions 1. Coalesce 2. Cooperate 3. Fall apart 4. Return to 1. But politics is also opportunistic, which means responses to context can sometimes manifest relatively quickly. I would argue that nothing can provoke a more stark change in a political coalition than when their opposition abandons a position or brand that appeals to the median voter.

I tend to view Trumpology the same way I view Sovietology: it’s interesting to consume out of curiosity but we probably won’t have a deep understanding and know who was right until 20 years after the fact. Warren Nutter was right about the Soviet Union being an industrial ruse, but in his time he was mostly dismissed. My mental model of Trump and his team is that he’s a bad-faith business person who leverages transaction costs to the hilt and whose narcissism makes him effective at assembling imcompetent yes men. But, and I can’t emphasize this enough, we don’t really know what’s happening internally, there’s just too much noise in the information stream. What we can effectively observe, however, is the policy bundle and platform messaging on which he is compaigning.

That bundle is overwhelmingly negative. Beyond traditional scapegoating, the picture being painted of the current United States is bleak. Pessimistic, dystopian imagery appeals to plenty of people from the left and right extremes, but I struggle to think of a time in US history where the median American did not believe in America as both a good idea and a good place to live. A lot of people when discussing the MVT focus on the prediction that both parties will, in a vaccuum, arrive at identical platforms, an idea that seems false on it’s face. This is not unlike the prediction of physics that a feather and a bowling ball will fall at the same velocity in a vacuum – to demostrate that they don’t from the top of your apartment building is to both miss the point and place the people around you in intellectual (if not mortal) danger.

The most important insight in the MVT is the gravity of the median. Or, in the case of the current election, the speed with which one party will reclaim any branding opportunities around said median when the opposition abandons them. I have no doubt there are some veteran leaders within the RNC that are fuming over the long term costs of letting the Democratic party claim the mantle of the more patriotic and optimistic party. These are the kind of brands that are hard to take from the opposition- you pretty much have to wait for them, in a moment of foolishness or chaotic happenstance, to release their grip. Which I suspect the Republicans have.

I have no doubt the Democrats will find a way to do makes similar mistakes with this or other positions in the future. Politics is chaos and the median voter is far easier to find on an abstract two-dimensional curve than in reality. But that doesn’t mean we can pretend the median voter isn’t out there and that they don’t matter. It’s a simple model that may always be wrong, but it will never lead you astray.

Top EWED Posts of 2024

The following are notable posts from 2024, in descending order by the number of views this year.

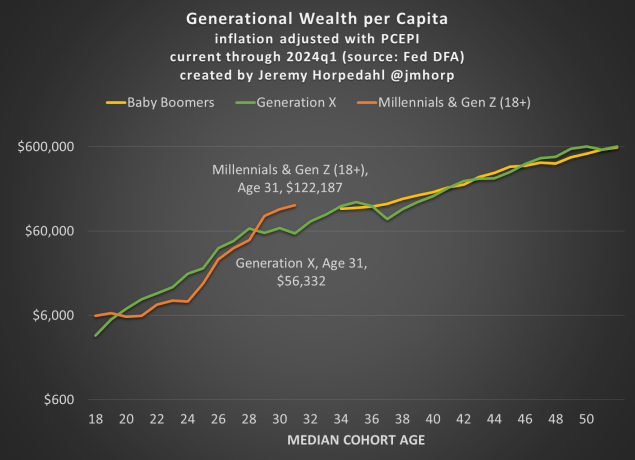
  1. Young People Have a Lot More Wealth Than We Thought Jeremy Horpedahl was first to this scene. American Millennials, on average, have money. Perhaps this is becoming common knowledge now among folks that read The Economist. The US is getting gradually richer, and the average young adult is benefiting. You can see more from Jeremy by following him on Twitter/X.
  2. Civil War as radical literalism   Mike Makowsky writes, “There’s a million war movies, most of which have arcs and metaphors strewn throughout. The problem with making a moving about a hypothetical civil war in the modern United States is that the audience will spend so much time looking for the heroes, villains, and associated opportunities to feel morally superior that it seems almost impossible to deliver an effective portrayal of what it might actually feel like to wake up to a US civil war…”  
  3. Is “Rich Dad  Poor Dad” a Fraud? Scott explores whether a popular finance book is based on a false premise.    
  4. Is the Universe Legible to Intelligence? I (Joy) do philosophy. It also has practical implications. Can machines outsmart us, for better or worse? How smart can anything physical be. Maybe, as @sama says, “intelligence is an emergent property of matter…” However, maybe “intelligence” only goes so far. We have many posts on artificial intelligence this year.
  5. How To Drive a Turbocharged Car, Such as a Honda CR-V This is one of those pieces by Scott that people find through search engines when they are looking for help.
  6. Grocery Price Nostalgia: 1980 Edition You can use our search function to find everything from this year about the topic of inflation.
  7. The US Housing Market Is Very Quickly Becoming Unaffordable
  8. Predicting College Closures James reflects on closing universities and what indicators might help stakeholders like parents and faculty anticipate the next event.
  9. Counting Jobs (Revisited) Jeremy did something that might have sounded boring at the time. Yet, soon afterwards there was serious interest in the question of : Did 818,000 jobs vanish?
  10. Why Avocado on Toast? As an avocado toast person, I loved this. I’m glad many other people found  Zachary’s post interesting.
  11. Recovering My Frozen Assets at BlockFi, Part1. How Sam Bankman-Fried’s Fraud Cost Me.
  12. Why Don’t Full Daycares Raise Prices? The cost of childcare is an important issue. James wrote this from personal experience, and I pointed out something similar before.
  13. This post only got medium traffic in terms of the number of views this summer. Now that we know who the candidate will be, it’s interesting to look back and see a vindication of betting markets. Who Will Be the Democratic Presidential Candidate? Follow the Money (Betting Markets)
  14. Honorable mention to Mike’s post from 2022 that continues to get many search hits: Why Agent-Based Modeling Never Happened in Economics

At this point, the EWED authors have each written enough words to constitute a book. Watching this blog grow and flux with the rest of the internet has been fascinating.

You can subscribe to our WordPress site to get posts sent to your email. The widget for putting your email in should be on the right side of your screen on a computer, or you can find it by scrolling to the bottom of the home page on a mobile device. WordPress will let you customize your preferences so that you get emails batched once a week if you prefer that to Every Day.

Persistent Beliefs

The things that happen between people’s ears are difficult to study. Similarly, the actions that we take and the symbolic gestures that we communicate to the people around us are also difficult to study. We often and easily perceive the social signals of otherwise mundane activities, but they are nearly impossible to quantify systematically beyond 1st person accounts. And that’s me being generous. Part of the reason that these things are hard to study is that communication requires both a transmitter and a receiver. One person transmits a message and another person receives it. Sometimes, they’re on slightly or very different wavelengths and the message gets garbled or sent inadvertently and then conflict ensues.

Having common beliefs and understandings about the world help us to communicate more effectively. Those beliefs also tend to be relevant about the material world too. A small example is sunscreen. Because a parent rightly believes that sunscreen will protect their child from short-run pain and long-run sickness, they might lather it on. But, due to their belief, they also signal their love, compassion, and stewardship for their child. A spouse or another adult failing to apply sunscreen to a child signals the lack thereof and conflict can ensue even when the long-term impact of one-time and brief sun exposure is almost zero.

People cry both sad and happy tears because of how they interpret the actions of others – often apart from the other external effects. Therefore, beliefs imbue with costs and benefits even the behaviors that have seemingly immaterial consequences otherwise. We can argue all day about beliefs. And while beliefs might change with temporary changes in the technology, society, and the environment, core beliefs need to be durable over time. Therefore, if this economist were to recommend beliefs, then I would focus on the prerequisite of persistence before even trying to find a locally optimal set.

Here are three inexhaustive criteria for a durable beliefs:

Continue reading →

People Are Paying for Music Again

Recorded music sales peaked in 1999- then came Napster and other ways to listen to the exact music you want for free. Recorded music sales still haven’t fully recovered, but with the rapid growth of paid streaming since 2014, they have been increasing again:

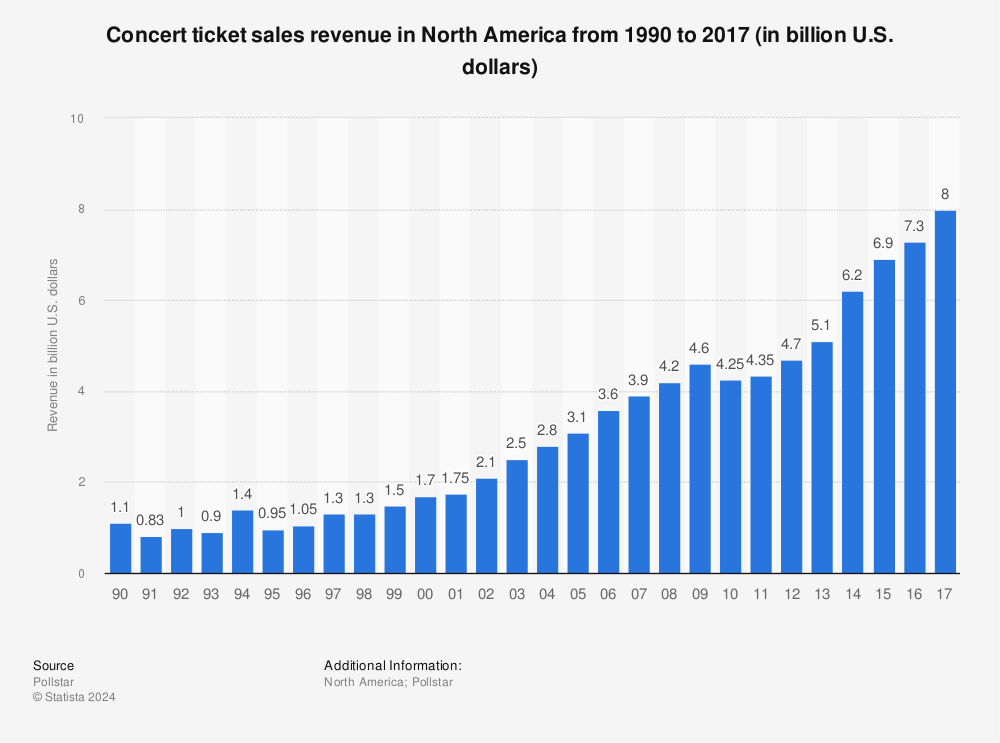
Meanwhile, live music sales have exploded since the ’90s:

Source: https://www.statista.com/statistics/306065/concert-ticket-sales-revenue-in-north-america/

The latest report from Pollstar on the top live tours is positively glowing:

2023 was a colossus, the likes of which the live industry has never before seen. If 2022 was a historic record-setting year, which it was, then this year completely blew it out of the water— by double digits. Total grosses for the 2023 Worldwide Top 100 Tours were up 46% to $9.17 billion

When you combine live and recorded sales, total spending on music has now passed the 1999 peak; this is the biggest the market for music has ever been. Of course, this doesn’t mean its an easy time to be a musician; touring is hard work and, as always, record labels and others are taking a big share of the money before it gets to artists. And opinions differ about whether today’s environment is good for creating good new music.

There are dozens of songs about how the road is hard, and the more time you spend on the road, the less they sound like cliches than like a simple and sometimes stark description of your life. Sooner or later everybody spots the exit that has their name on it –John Darnielle

The BLS data is noisy but suggests that the number of musicians in the US has been fairly flat and is projected to stay that way. A lot will depend on whether live music continues to grow, how much of that is captured by a few superstars, and whether the current streaming paradigm continues, or goes in a more or less artist-friendly direction. But now that consumers are willing to pay for music again, artists at least have a fighting chance.

Did 818,000 jobs vanish?

This morning the Bureau of Labor Statistics released the latest quarterly data for their Quarterly Census of Employment and Wages for the first quarter of 2024. Along with this release is the announcement of their preliminary “benchmark estimate” for March 2024, which will eventually (next year) be used to revise employment data for the Current Employment Statistics program. To keep all of the alphabet soup of programs clear in year head, CES is the more familiar “nonfarm jobs” data that is released each month, usually with some media fanfare.

Benchmarking is an important part of the process for many data releases, because the monthly CES data is based on a survey of employers, a subset of the total. But the QCEW data is the universe of employees — at least the universe of the those covered by Unemployment Insurance law, which is something like 97-98% of workers in the US. So the numbers will never match exactly (CES is supposed to be measuring all workers, not just the 97-98% covered by UI), but they should be pretty close. The media reports the CES monthly data more prominently, because it is more timely and usually pretty close to correct — but benchmarking is the process to see just how correct those initial surveys were.

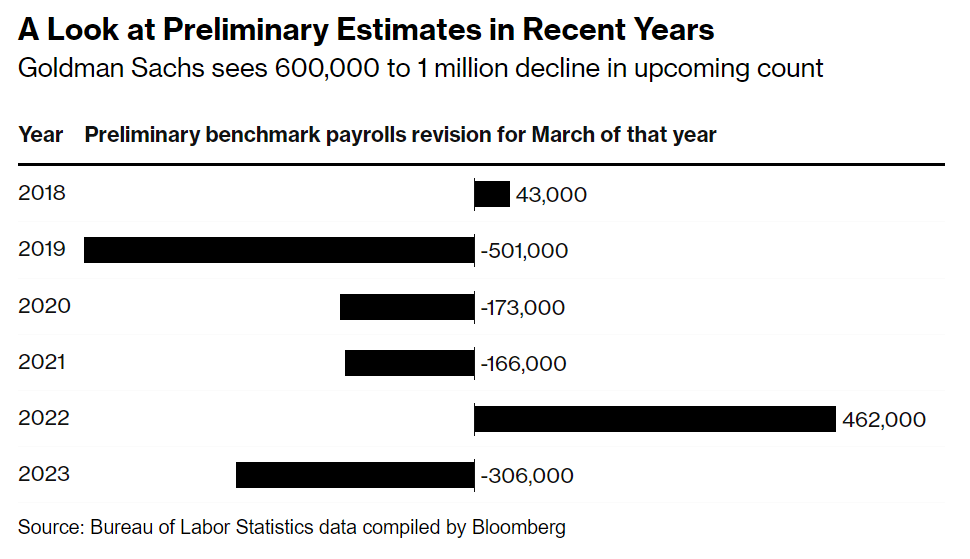
That brings us to the release today, which is the preliminary estimate of the benchmark adjustment for March 2024 (it will be finalized early in 2025). And that preliminary estimate was a big number, with a downward revision projected of 818,000 jobs. To put this in perspective, the current CES data shows 2.9 million jobs were added between March 2023 and March 2024, so this estimate suggest that the job growth was overstated by perhaps 40 percent. That’s a big revision, though large revisions are not unheard of: the same figure for March 2022 was an estimated 468,000 jobs higher, while March 2019 was 501,000 jobs lower. But this year is a big one (largest absolute number since 2009). Here’s a chart summarizing recent years revisions from Bloomberg:

I’ve covered this topic before, such as an April 2024 post where I noted that as of September 2023, there was an 880,000 gap in job growth between the CES and QCEW over the prior year. So this was not unexpected, and in the days leading up to the report, close followers of the data were forecasting that the revision could be up to 1 million jobs.

Continue reading →

Many Impressive AI Demos Were Fakes

I recently ran across an article on the Seeking Alpha investing site with the provocative title “ AI: Fakes, False Promises And Frauds “, published by LRT Capital Management. Obviously, they think the new generative AI is being oversold. They cite a number of examples where demos of artificial general intelligence were apparently staged or faked.  I followed up on a few of these examples, and it does seem like this article is accurate. I will quote some excerpts here to give the flavor of their remarks.

In 2023, Google found itself facing significant pressure to develop an impressive innovation in the AI race. In response, they released Google Gemini, their answer to OpenAI’s ChatGPT. The unveiling of Gemini in December 2023 was met with a video showcasing its capabilities, particularly impressive in its ability to handle interactions across multiple modalities. This included listening to people talk, responding to queries, and analyzing and describing images, demonstrating what is known as multimodal AI. This breakthrough was widely celebrated. However, it has since been revealed that the video was, in fact, staged and that it does not represent the real capabilities of Google’s Gemini.

… OpenAI, the company behind the groundbreaking ChatGPT, has a history marked by dubious demos and overhyped promises. Its latest release, Chat GPT-4-o, boasted claims that it could score in the 90th percentile on the Unified Bar Exam. However, when researchers delved into this assertion, they discovered that ChatGPT did not perform as well as advertised.[10] In fact, OpenAI had manipulated the study, and when the results were independently replicated, ChatGPT scored on the 15th percentile of the Unified Bar Exam.

… Amazon has also joined the fray. Some of you might recall Amazon Go, its AI-powered shopping initiative that promised to let you grab items from a store and simply walk out, with cameras, machine learning algorithms, and AI capable of detecting what items you placed in your bag and then charging your Amazon account. Unfortunately, we recently learned that Amazon Go was also a fraud. The so-called AI turned out to be nothing more than thousands of workers in India working remotely, observing what users were doing because the computer AI models were failing.

… Facebook introduced an assistant, M, which was touted as AI-powered. It was later discovered that 70% of the requests were actually fulfilled by remote human workers. The cost of maintaining this program was so high that the company had to discontinue its assistant.

… If the question asked doesn’t conform to a previously known example ChatGPT will still produce and confidently explain its answer – even a wrong one.

For instance, the answer to “how many rocks should I eat” was:

…Proponents of AI and large language models contend that while some of these demos may be fake, the overall quality of AI systems is continually improving. Unfortunately, I must share some disheartening news: the performance of large language models seems to be reaching a plateau. This is in stark contrast to the significant advancements made by OpenAI’s ChatGPT, between its second iteration (GPT-2), and the newer GPT-3 – that was a meaningful improvement. Today, larger, more complex, and more expensive models are being developed, yet the improvements they offer are minimal. Moreover, we are facing a significant challenge: the amount of data available for training these models is diminishing. The most advanced models are already being trained on all available internet data, necessitating an insatiable demand for even more data. There has been a proposal to generate synthetic data with AI models and use this data for training more robust models indefinitely. However, a recent study in Nature has revealed that such models trained on synthetic data often produce inaccurate and nonsensical responses, a phenomenon known as “Model Collapse.”

OK, enough of that. These authors have an interesting point of view, and the truth probably lies somewhere between their extreme skepticism and the breathless hype we have been hearing for the last two years. I would guess that the most practical near-term uses of AI may involve some more specific, behind the scenes data-mining for a business application, rather than exactly imitating the way a human would think.

Interpreting candidate policies

Interpreting policy talking points from people running for office is difficult for a variety reasons, but it essentially boils down to the fact that voters often do not want the outcomes that would be produced by the policies they will in fact vote for. Candidates, in turn, must find a way to promise policies they will either do their best not to deliver or, if they do deliver them, said policies will be bundled with other policies that will mitigate their effect.

Interpreting the true intended policy bundle being signaled by a candidate is fraught with traps, not least of which our personal biases. If I want to like a candidate, for social or identity reasons, I will have a tendency to interpret their policy proposals as part of a broader, unspoken, bundle that I like. If I don’t want to like a candidate, perhaps because they are a petty, boorish lout whose principle aptitude appears to be grifting at the margins of legality and leveraging the high transaction costs of our legal system, then I will subconsciously interpret each policy proposed as part of a more insidious unspoken bundle.

How should voters and pundits navigate an environment where information is limited and bias is largely unavoidable? I don’t know, but here’s how I try anyway.

  1. Assume every candidate has basic competency in appealing to their base.
  2. Assume every candidate wants to appeal to the median voter.
  3. Do not assume anyone knows who the median voter is.
  4. Assume both candidates and their advisors have the same capacity to assess how their respective bases will react to a proposal and how it will actually impact them, but do not assume they know how the median voter will react and be affected.

In essence, candidates will always have a deeper familiarity, with greater repeated interactions, with their voter and donor bases. They know how they will react and how they will actually be impacted. Platforms will be designed around navigating contexts where popularity and expected impact are in conflict. What this means is that, in the aggregate,

  1. A candidate stands to do the most damage when advocating for policies that will aid their base at the expense of the median
  2. A candidate will create the most uncertainty when the desires of their base are at odds with the consequences for their base.

For example, assume both major parties are advocating for trade restrictions. Let’s call them the Plurality party and the Majority parties. Trade restrictions will hurt the median voter, full stop. The Plurality party, whose indentity constitutes a minority of the total population but the largest share of the population of any subgroup, stands to gain the most through policies that extract from others in a negative sum game. It will be easier to take their candidate’s policies at face value because of uncertainty around the median voters preferences, in part due to voter uncertainty about how policies will affect them.

The Majority party, on the other hand, is more fractured in the subgroups that constitute its more numerous whole. They can be thought of an encompassing group coping with the high costs of intragroup bargaining. Their greater numerical advantage in elections is partly, if not wholly, nullified by difficulty solving collective action problems and their need to solve positive sum games whose benefits are spread too thinly to excite their base. Further, the Majority party is inclusive of the median voter, about which there is greater uncertainty. The Majority party, as such, has greater incentive to rely on a form of subtextual deception. To win elections, they will need to propose the policies that the various elements their base wants while also bundling them with other policy elements that will mitigate their consequences in the aggregate and leave options open downstream as consquences for the median are made manifest. Interpreting proposals of the Majority party demands more Straussian reading, which also means that greater care is needed in monitoring your own bias. Because all complex political economy aside, sometimes parties do in fact just have bad ideas.

Good luck.

Sticky Prices as Coordination Failure Working Paper

“Sticky Prices as Coordination Failure: An Experimental Investigation” is my new paper with David Munro of Middlebury, up at SSRN.

We ask whether coordination failures are a source of nominal rigidities. This was suggested in a recent speech by ECB President Christine Lagarde. She said, “In the recent decades of low inflation, firms that faced relative price increases often feared to raise prices and lose market share. But this changed during the pandemic as firms faced large, common shocks, which acted as an implicit coordination mechanism vis-à-vis their competitors.”

Coordination failure was suggested as a possible cause of price rigidity in a theory paper by Ball and Romer (1991). They demonstrated the possibility for multiple equilibria, and we perform the first laboratory test to observe equilibrium selection in this environment.

We theoretically solve a monopolistically competitive pricing game and show that a range of multiple equilibria emerges when there are price adjustment costs (menu costs). We explore equilibrium selection in laboratory price setting games with two treatments: one without menu costs where price adjustment is always an equilibrium, and one with menu costs where both rigidity and flexibility are possible equilibria.

In plain language, for our general audience, the idea is that the prices you set might depend on what other people are doing. If other people are responding to a shock (for example, Covid driving up labor costs all over town might cause retail prices to rise) then you will, too. If every other store in town is afraid to raise prices, then there is a certain situation where you might resist adjusting your prices, too (price rigidity).

Results: First, when there is only one theoretical equilibrium, subjects usually conform to it. When cost shocks are large, price adjustment is a unique equilibrium regardless of the presence of menu costs, and we see that subjects almost always adjust prices. When cost shocks are small and there are menu costs rigidity is a unique equilibrium and subjects almost never adjust. Conversely, with small cost shocks subjects almost always adjust when there are no menu costs.

The more interesting cases are when the parameters allow for either rigidity or flexibility to be selected. We find that groups do not settle at the rigidity equilibrium. Rather, depending on the specific nature of the shock, between half and 80% of subjects adjust in response to a shock. The intermediate levels of adjustment are represented here in this figure as the red circles that fall between the red and green bands where multiple equilibria are possible.

In the figure above, the red circles are higher when the production cost shock gets further from zero in absolute value. We see that the proportion of subjects adjusting prices is proportional to the size of the cost shocks. This is consistent with the interpretation that the large post-COVID cost shocks acted as an implicit coordination mechanism for firms raising prices. Our results provide a number of interesting insights on nominal rigidities. We document more nuance in the paper regarding heterogeneity and asymmetry. Comments and feedback are appreciated! If it’s not clear from the EWED blog how to email me (Joy), find my professional contact info here. 

Services, and Goods, and Software (Oh My!)

When I was in high school I remember talking about video game consumption. Yes, an Xbox was more than two hundred dollars, but one could enjoy the next hour of that video game play at a cost of almost zero. Video games lowered the marginal cost and increased the marginal utility of what is measured as leisure. Similarly, the 20th century was the time of mass production. Labor-saving devices and a deluge of goods pervaded. Remember servants? That’s a pre-20th century technology. Domestic work in another person’s house was very popular in the 1800s. Less so as the 20th century progressed. Now we devices that save on both labor and physical resources. Software helps us surpass the historical limits of moving physical objects in the real world.


There’s something that I think about a lot and I’ve been thinking about it for 20 years. It’s simple and not comprehensive, but I still think that it makes sense.

  • Labor is highly regulated and costly.
  • Physical capital is less regulated than labor.
  • Software and writing more generally is less regulated than physical capital.


I think that just about anyone would agree with the above. Labor is regulated by health and safety standards, “human resource” concerns, legal compliance and preemption, environmental impact, and transportation infrastructure, etc. It’s expensive to employ someone, and it’s especially expensive to have them employ their physical labor.

Continue reading →