Let’s Be Thankful for Food Abundance

Despite recent increases in prices of food, we should still all be very thankful this Thanksgiving for the abundance of affordable food available in the modern world. Looking back at my past few blog posts, I notice that I have been very food-centric in my choice of topics! And last week I also showed how the Thanksgiving meal this year will be the second cheapest ever (only behind 2019). While it’s absolutely true that food prices are up a lot in the past 2 and 4 years, they probably aren’t up as much as you have heard.

It’s always my preference to take as long-term perspective as possible when thinking about economic progress. So here’s the best way I’ve come up with to show how cheap and abundant food is today: food as a share of household spending fell dramatically in the 20th century.
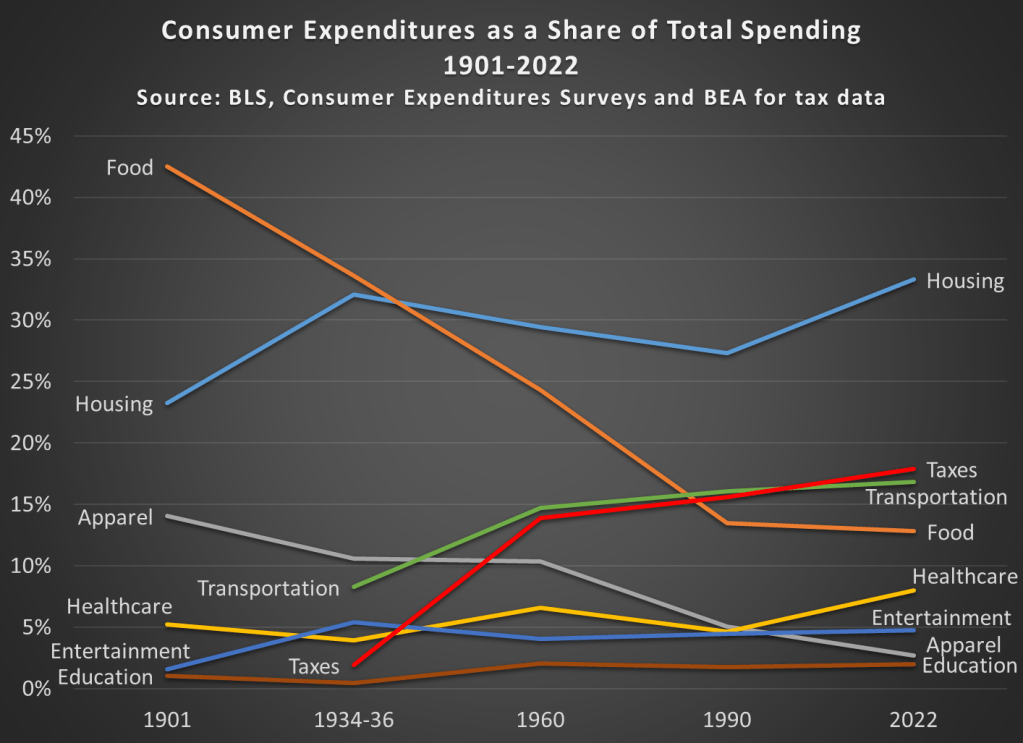
Most of the data in this chart comes from the BLS Consumer Expenditure Surveys. This survey was done occasionally since 1901, and then annually since 1984. I also use BEA data to estimate personal taxes paid as a percent of spending (the CEX Surveys have some tax data, but it’s not reliable nor consistent). I picked as close to 30-year intervals as I could (with a preference for showing the earliest and latest years available), and I chose spending categories that are 90-100% of total expenditures in most of these years. Keep in mind also that these are consumer expenditures. As a nation, we spend a lot more on healthcare and education than this chart suggests, but most of that spending is not directly from households (of course, it is indirectly). Think of this chart as an average household budget.

I hope the thing that jumps out at you is that the amount money households spend on food has fallen dramatically since 1901, from over 42 percent to under 13 percent of household expenditures. To be clear, this data includes both spending on food at home and at restaurants (after 1984 we can track them separately, and groceries are pretty consistently about 60 percent of food spending). And you may be wondering about very recent trends too, such as before the pandemic. In 2022, household spent slightly less on food than they did in 2019, falling from 13.5 to 12.8%.

You may also notice that taxes have increased, though not much since 1960. Housing cost have been consistently high, and also a bit higher than 1990, going from 27 percent to 33 percent in 2022. And housing is now the single largest budget expenditure category, but for most of the first half of the 20th century, it was food that was the largest. And since people aren’t changing their housing situation more than once a year (if that), it would also have been food that dominated weekly and monthly budget decisions and worry about price fluctuations.

This year there will be lots of complaining about prices around the Thanksgiving table. And much of that is warranted! But let’s also be thankful on this food-intensive holiday for how cheap the food is.

And if some smart-aleck youngster tries to tell you that they learned on TikTok that things were better during the Great Depression (yes, people are really saying this!), have them watch this video by Christopher Clarke. Or show them that in the mid-1930s an average family spent one-third of their budget on food in my chart above, or how much labor it would have taken to buy that turkey in the 1930s (about 40 times as much time spent working as today).

Mutiny in Silicon Valley:  OpenAI Workforce May Quit and Join Microsoft If Board Does Not Resign and Bring Back Former CEO Sam Altman

The bombshell news in the tech world as of late Friday was that, in a sudden coup, the board of OpenAI fired CEO and tech entrepreneur Sam Altman, and demoted company cofounder and former president Greg Brockman. The exact grounds for their decision remain somewhat murky, but apparently Altman wanted to move faster with AI deployment and monetization than some board members were comfortable with.

The OpenAI organization burst on the scene in the past year with the release of advanced versions of ChatGPT. This “generative” AI technology can crank out computer code and human-like text articles and reports and images. Naturally, students have taken to employing ChatGPT to write their essays for them. And so, professors now use AI to detect whether their students’ essays were machine written or not.

Fellow blogger Joy Buchanan has addressed the rising problem of erroneous information (“hallucinations”) that can appear in AI generated material. There is a movement to slow down the development of AI, for fear it will lead to The End Of The World As We Know It (TEOTWAWKI).  (Interestingly, all of the business commentators I listened to today dismissed the alleged world-ending dangers of generative AI as largely deliberate hype on the part of AI developers, to create a buzz – which it has.)

Having hitched itself technically to OpenAI technology, and having poured something like $13 billion into funding OpenAI, giving it a 49% ownership stake in part of the business, Microsoft was obviously concerned about the effect of Altman’s dismissal on its own AI plans.  As it became clear that the board action would lead to substantial dysfunction at OpenAI, Microsoft carried out its own coup, by hiring Altman and Brockman to run a big in-house AI research initiative, and making it clear that anyone else who wanted to resign from open AI could have their old jobs back, under their old leaders, in Seattle.  And indeed, as of late Monday, nearly all of OpenAI’s employees had signed an open letter stating that unless the OpenAI board quits, they “may choose to resign from OpenAI and join the newly announced Microsoft subsidiary.”

Investors are still trying to figure out what all this means for Microsoft. A pessimistic take is that the corporation has to take a big write down on a $13 billion investment, if the OpenAI organization  (valued a month ago at $90 billion) loses its momentum. An optimistic take is that Microsoft may get the human capital crown jewels of this leading tech outfit for simply the cost of salaries (and signing bonuses), instead of shelling out to buy the enterprise as such. Also, having the technology all in-house would remove the vulnerability of Microsoft currently faces with having a key piece of its future in the hands of a separate organization. There is debate on how much the intellectual property held by OpenAI would inhibit Microsoft from forging ahead with its own version of ChatGPT.

According to Wikipedia:

Shares in Microsoft fell nearly three percent following the announcement.   According to CoinDesk, the value of Worldcoin, an iris biometric cryptocurrency co-founded by Altman, decreased twelve percent.   After hiring Altman, Microsoft’s stock price rose over two percent to an all-time high.  

According to The Information, Altman’s removal risks a share sale led by Thrive Capital valuing the company at US$86 billion.   A potential second tender offer for early-stage investors is also at risk.   Altman’s removal could benefit OpenAI’s competitors, such as Anthropic, Quora, Hugging Face, Meta Platforms, and Google.  The Economist wrote that the removal could slow down the artificial intelligence industry as a whole.  Google DeepMind received an increase in applicants, according to The Information. Several investors considered writing down their OpenAI investments to zero, impacting the company’s ability to raise capital. Over one hundred companies using OpenAI contacted competing startup Anthropic according to The Information; others reached out to Google Cloud, Cohere, and Microsoft Azure.

There is a slight possibility that the open AI board could take a big hit for the team, and bring back Altman and Brockman and then resign in order to keep the organization intact. If that happens, the deployment of generative AI would accelerate – – which might destroy the world.

THIS JUST IN: ALTMAN BACK IN CHARGE AT OPENAI

If there was a prize for “worst board decision of the year” it would have to go to the move late last week to fire Sam Altman. But just when you thought there was no more drama to be milked out of this scene, the news Wednesday is that the OpenAI board is out, and Altman is back in as CEO at OpenAI. Microsoft is presumably happy to have the organization intact, and it seems that those pesky timid souls who were trying to go slow on AI proliferation have been swept aside. TEOTWAWKI here we come…

Stop and Frisk was an Unmitigated Disaster

Sometimes we think things have been incontrovertibly been proven, but we really only know them. Other times we think we know them but we really only think them. It’s always interesting when we something we think becomes something we know. We share those beliefs a little more often with a little more confidence. We start trying to tilt the balance of common knowledge one conversation at a time. I’d argue, however, that we would often be better served to wait until something is proven, as much as something can be proven. Or, at the very least, that our conversational was weight shifted far more when truly compelling evidence hits the scene.

I already believed that New York City’s infamous “Stop and Frisk” program was bad. That the bad outweighed the good. I was always careful to soften my language, to hedge my claims, however, because I always suspected there had to be some margins on which the program yielded some benefit to someone, somewhere, in some context. Criminal deterrence is real, after all.

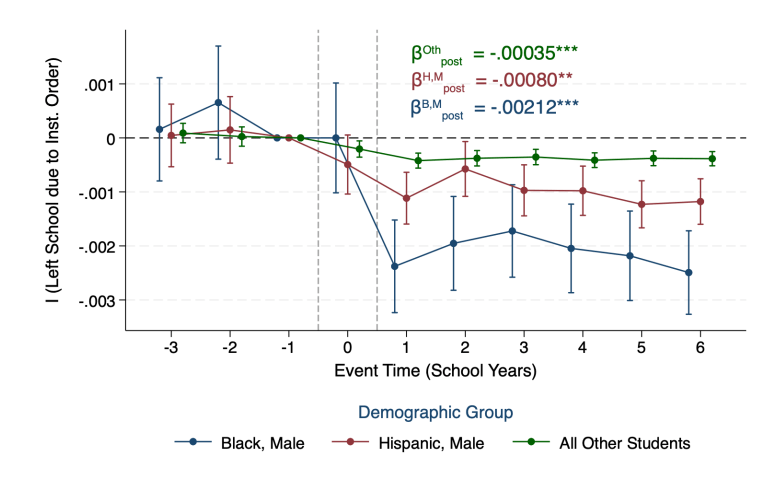
I no longer feel any need to soften my language or claims one iota. There are research papers that change your priors. There are also ones that harden them into granite. Jonathan Tebes and Jeffrey Fagan have a new working paper they are presenting at conferences and quietly circulating that provides the single most compelling research effort into the effects of Stop and Frisk I have come across to date, one which makes the case that Stop and Frisk had now measurable effect at the margin to deter crime while, at the same came, causing significant harm to the young Black men walking the streets of New York City.

Please go through the slides, but let me summarize. Using a credible and clever event study design around the end of Stop and Frisk, Tebes and Fagan are able to identify the effect of stops on crime, finding an impressively precise null effect. They then look the effect of these stops of neighborhood schooling outcomes, specifically interruptions to instruction, persistent absences, suspensions, and graduation. The result, again, is very clear: Stop and Frisk was a disaster for high school age Black Men.

I’m just going to leave it there. Read the slides, read the paper when they release it, update your priors. And when someone tries to tell you at Thanksgiving dinner this year that New York City is going straight to hell because they ended Stop and Frisk, have the confidence to vigorously attempt to update their priors. Will it work? I’ve never met your family…but probably not.

But you gotta try, right? It’s your duty. And then make yourself a drink or take an extra slice of pie knowing that you earned it.

The current alliance to counter digital piracy

U.S. Immigration and Customs Enforcement’s (ICE) Homeland Security Investigations (HSI) has joined forces with the Motion Picture Association (MPA) to launch a new initiative aimed at countering digital piracy and protecting a vital sector of the U.S economy.

The initiative is called Operation Intangibles.

Digital streaming services provide quick and easy access to creative works, such as music, television, movies. However, the growth of digital streaming services has presented new challenges when it comes to law enforcement’s ability to ensure vital copyright protection for the industry. This technology that has provided millions of people access to their favorite shows, has also enabled criminals to turn piracy into a crime that is no longer restricted to the hand-to-hand sale of illegally pirated media.

Digital piracy negatively impacts millions of jobs, results in less taxes being paid, and threatens innovation and creativity. Its effects are felt across multiple industries and includes the cost of corollary crimes on consumers such as the potential damage caused by hidden or embedded malware, as well as identity theft and financial crimes, such as credit card fraud.

There exists a National Intellectual Property Rights Coordination Center.

Recall, Napster was shut down in 2001. Limewire was shut down in 2010. Illicit downloading is happening through other channels.

According to this graph, people spent almost as much on vinyl records as they did on CDs in 2018. The Economist provided a nice chart (last updated in 2019) on the rise of streaming revenue and the collapse of traditional records sales.

Malinvestment Produces Knowledge

Austrian economists rightfully have some gripes about mainstream macroeconomics – specifically about aggregation. The conventional wisdom says that a fall in output can be prevented or remedied in the short-run by an expansion of total spending (via increasing the money supply). Total output is stabilized and the crisis is averted. Even if rising spending preceded the output decline, the standard prescription is the same.

The Austrian Business Cycle theory says that, actually, the prior expansion in spending resulted in yet-to-be-realized poor investments due to easy credit. The decline in output is self-inflicted by unsustainable endeavors, and the money supply expansion response prevents the correction. The consequence is more malinvestment. The Austrians say that the focus on gross investment is a misleading aggregation and commits the fallacy of composition that all investment is the same or the same on relevant margins.

Both schools of thought are on firm ground. I don’t see them as conflicting. They both make valid points and are correct about the world. The conventional wisdom is able to paper-over short-run hiccups, and the Austrians recognize that resources are suboptimally allocated. The two sides are talking past each other to some extent.

The market process of seeking profits and satisfying consumer demands is a messy process. Prices and profits (and losses) incentivize firms with information that they use to adjust their behavior. They innovate and reallocate resources from bad projects and toward money-making projects. When firms earn negative profits (a loss) they learn that their understanding of the world was wrong and that they malinvested their scarce resources. Therefore, malinvestment is a standard and *necessary* part of the market process of identifying and serving the changing and unknown demands of individuals. Without malinvestment we lack the necessary information to distinguish success from failure.

Mal-investment is harmful insofar as it represents resources that were invested such that future output did not rise as it could have otherwise. So, while malinvestment is necessary to the market process, a preponderance of it makes us poorer in the future. Luckily, firms have incentives and finite resources such that mal-investment remains somewhat tamed. Indeed, malinvestment is the cost that we bear for innovation and identifying what works.

The issue is that the above discussion is oriented to the long-run. The conventional wisdom is oriented toward resolving the short-run threats. The two meet one another when malinvestment realizations occur in a correlated manner. It’s not that policy causes malinvestment. Rather, depressed interest rates and easy credit prevent firms from identifying which of their projects turned out to be more or less productive. Firms persist in bad investments because they can’t discriminate between the failed and successful projects ex ante.

So, when interest rates suddenly rise, low or negative productivity projects are identified and resources are reallocated. The discovery and reallocation process takes time. And if many projects are found to be failures at once, then the result is a drop in economic activity that is detectable at the aggregate level. The problem is not that malinvestment exists. The problem is that malinvestment was permitted to persist and grow such that the eventual realization of losses is correlated and has macroeconomic effects. We observe spending, output, and employment declines. That’s the ‘business cycle’ part of the Austrian Business Cycle. Interest rates rising helps to identify the bad projects. That’s good. But policy that increases the popularity of bad projects is bad. It makes us poorer in the long-run and more vulnerable to declines in the short-run.

New Orleans Redux: SEA 2023

I’m heading to New Orleans tomorrow for the 2023 meeting of the Southern Economic Association, where I’ll present research on the labor market effects of Certificate of Need laws.

I’ll take this as an excuse to re-up two previous posts on New Orleans:

First, my travel guide post for anyone else heading there soon

Second, my bigger-picture take on how the city has changed over the last decade: Waxing Crescent: New Orleans 2013-2023

I recommend reading the whole thing, but here’s the conclusion:

As much as things have changed since 2013, my overall assessment of the city remains the same: its unlike anywhere else in America. It is unparalleled in both its strengths and its weaknesses. If you care about food, drink, music, and having a good time, its the place to be. If you’re more focused more on career, health, or safety, it isn’t. People who fled Katrina and stayed in other cities like Houston or Atlanta wound up richer and healthier. But not necessarily happier.

Hope to see some of you there!

Thanksgiving 2023 is the Second Cheapest Ever (Relative to Earnings)

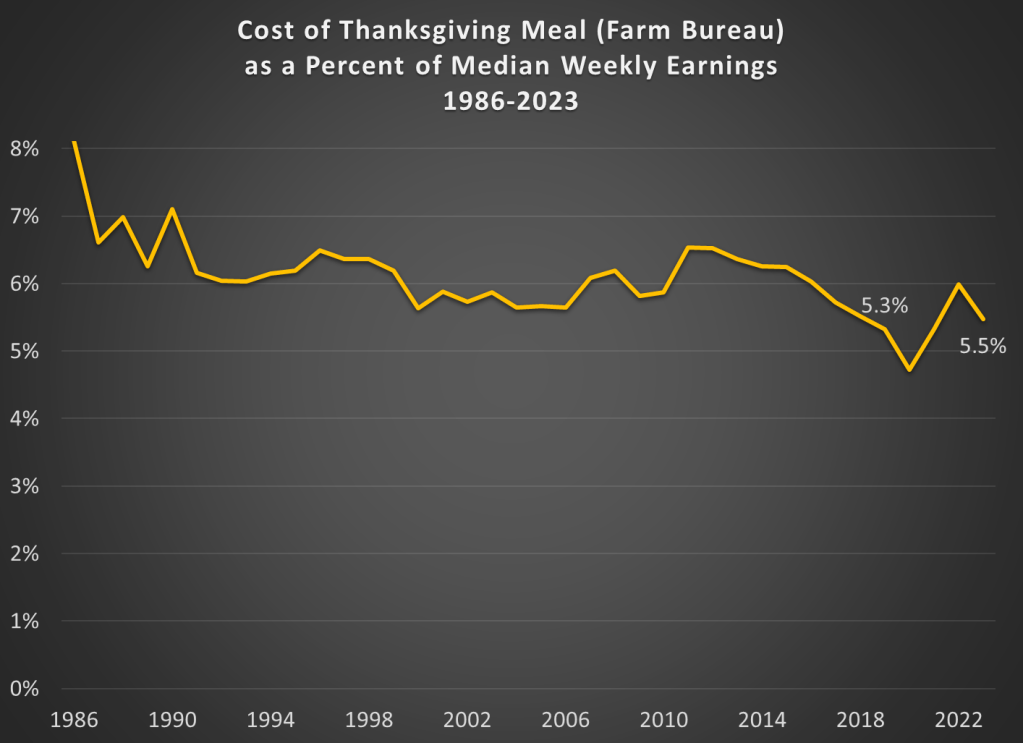
Continuing my tradition of Thanksgiving posts, Farm Bureau released today the latest data on the cost of a traditional Thanksgiving meal. There is welcome news for consumers, as the nominal price of the dinner is slightly lower than last year: $61.17 vs. $64.05 in 2022. The big factor in this decline was the fall in the price of turkeys, though eight of the 12 items in this meal are lower than 2022. As they note in the press release, this is still significantly higher than 2019: about 25% higher.

Regular readers will know what’s coming. Let’s compare those prices (and some historical prices) to earnings:

The Farm Bureau turkey dinner stands at about 5.5 percent of median weekly earnings from the third quarter of this year. That’s a touch higher than 2019, when it was 5.3 percent of weekly earnings. But notice that other than 2019, the figure for 2023 is the lowest ever! (Ignoring the weird years of the pandemic, when wage data is hard to interpret.) So we haven’t quite gotten back to 2019 levels, but we are at the same level as 2018. And lower than 2017. And all prior years too.

The last few Thanksgivings have been tough for Americans. This year, we can all be thankful for falling prices and rising wages.

“The Biggest Blunder in The History of The Treasury”: Yellen’s Failure to Issue Longer-Term Treasury Debt When Rates Were Low

That extra $4 trillion or so that the feds dumped into our collective checking accounts in 2020-2021 – -where did it come from? Certainly not from taxes. It was created out of thin air, via a multi-step alchemy. The government does not have the authority to simply run the printing presses and crank out benjamins. The  U.S. Treasury sells bonds to Somebody(ies), and that Somebody in turn gives the Treasury cash, which the Treasury then uses to fund government operations and giveaways. In 2020-2021, the Somebody who bought all those bonds was mainly the Federal Reserve, which does have the power to create unlimited amounts of cash, in exchange for government bonds or certain other investment-grade fixed income securities.

What is causing a bit of a kerfuffle recently is public assessment of what sorts of bonds that Janet Yellen’s Treasury issued back then. Interest rates were driven down to historic lows in that period, thanks to the Fed’s monster “quantitative easing” (QE) operations. The Fed was buying up fixed income hand over fist: government bonds, mortgage securities, even corporate junk bonds (which was probably illegal under the Fed’s charter, but desperate times…). This buying frenzy drove bond prices up and rates down.

All corporate CFOs with functioning neurons and with BB+ credit ratings refinanced their company debt in that timeframe: they called in as much of their old bonds as they could, and re-issued long-term debt at near-zero interest rates. Or they just issued 5, 10, 20 year low-interest bonds for the heck of it, raising big war-chests of essentially free cash to tide them through any potential hard times ahead. And of course, millions of American homeowners likewise refinanced their mortgages to take advantage of low rates.

What about the federal government? Was the Treasury, under Secretary  Yellen, similarly clever? No, not really. Because there is little serious doubt that the U.S. government will be able to pay its debts (grandstanding government shutdowns aside), the government can always find takers for 20- and 30-year bonds, as well as shorter maturity securities. A mainstay of government financing is the 10-year bond. And in 2020-2021, the Fed would have consumed whatever kinds of bonds the Treasury wanted to sell, so the Treasury could have issued a boatload of long-term bonds.

It seems that the Treasury issued a lot of 2-year bonds, rather than longer-term bonds. If they had issued say ten-year bonds, the government would have had a decade of enjoying very low interest payments on that huge slug of pandemic-related debt. But now, all those 2-year bonds are being rolled over at much higher rates and thus much greater expense to the government. (Since the federal debt only grows, almost never shrinks, maturing earlier bonds are not simply paid down, but are paid by issuing yet more bonds).

Veteran hedge fund manager Stanley Druckenmiller (reported net worth: $6 billion) commented in an interview:

When rates were practically zero, every Tom, Dick and Harry in the U.S. refinanced their mortgage… corporations extended [their debt],” he said. “Unfortunately, we had one entity that did not: the U.S. Treasury….

Janet Yellen, I guess because political myopia or whatever, was issuing 2-years at 15 basis points[0.15%]   when she could have issued 10-years at 70 basis points [0.70 %] or 30-years at 180 basis points [1.80%],” he said. “I literally think if you go back to Alexander Hamilton, it is the biggest blunder in the history of the Treasury. I have no idea why she has not been called out on this. She has no right to still be in that job.

Ouch.

Druckenmiller went on:

When the debt rolls over by 2033, interest expense is going to be 4.5% of GDP if rates are where they are now,” he warned. “By 2043—it sounds like a long time, but it is really not—interest expense as a percentage of GDP will be 7%. That is 144% of all current discretionary spending.

Unsurprisingly, Yellen demurs:

 “Well, I disagree with that assessment,” Yellen said when asked to respond to the accusation during an interview on CNN Thursday night. She said the agency has been lengthening the average maturity of its bond portfolio and “in fact, at present, the duration of the portfolio is about the longest it has been in decades.”

According to Druckenmiller, this is not quite true. It does seem that of the federal bonds held by the public (including banks), the average maturity (recently as long as 74 months) has indeed been a bit longer than usual in the past several years. However, this ignores the huge amount of government bonds held at the Fed:

“The only debt that is relevant to the US taxpayer is consolidated US government debt,” Druckenmiller said. “I am surprised that the Treasury secretary has chosen to exclude $8 trillion on the Fed balance sheet that is paying overnight rates in the repo market. In determining policy, it makes no sense for Treasury to exclude it from their calculations.”

Druckenmiller makes an important point. However, how this plays out depends on how the Fed treats these bonds going forward. If the Fed keeps these bonds on its balance sheet, and buys the replacement bonds, there will be actually very little interest expense to the government going forward. The reason is that the Fed is required to remit 90% of its profits back to the Treasury, so the gazillions of interest payments on those bonds and their replacements will largely flow right back to Treasury. However, if the Fed continues with reducing its balance sheet, forcing the Treasury to go the open market to roll these bonds over, Druckenmiller’s dire warnings will prove correct.

Because of this enormous debt overhang and the ongoing need for the government to sell bonds, I do not expect interest rates to go down as low as 2021 or even 2019 levels, unless there is a financial catastrophe requiring the Fed to become a gigantic net buyer of bonds once again.

OnlyFans models are creating cults politicians can only dream of

First, read this story from the NYT about the biggest producer of content on OnlyFans. TLDR; a couple have a compound in Florida and a full stable of employees (writers, editors, accountants, cooks, etc.) all being coordinated around the gigabytes of data generated by the supply and demand of their sexy content. If they were selling in a less stigmatized market, whis would be taught as a case study at business schools.

What I found interesting is how it simultaneously validated and assuaged all my fears about the opportunity to emotionally manipulate large numbers of people by using highly granular data. Don’t get me wrong, that’s arguably the story of every information-deficient marketing campaign ever, but I’m not talking about coarse, subliminal manipulation (“Look at this fully self-actualized person drive a car that signals their worth to strangers and their father”). I mean direct, interpersonal maninipulation through the fabrication of intimate parasocial bonds. The ability to allow customers to create their own, bespoke, false narrative in which they have a relationship with a beautiful stranger. At scale.

It’s that list bit that matters. What this couple have deconstructed is a formula for producing intimate parasocial relationships worth thousands of dollars to customer at scale.

The exploitation of fabricated relationships for income is the story behind the worlds oldest profession, not to mention most scams, for a very long time. The ability to produce them at any real scale, however, has been far more elusive. When someone pulls it off they’ve usually created a cult, whether it’s a new religion or a political cult of personality, and it’s worth taking note of. So have these Onlyfans creators laid out the blue print for future politicians, social entrepreneurs, and general power seekers? Are we at the beginning of an industrial revolution for social movements?

Actually, I kind of think they do have a blue print, but it’s going to be a minute before it crosses the chasm to other sectors because most fields that rely on parasocial relationships to grow don’t have the luxury of immediate profitability that sex work does. You might start your social movement with the ambition of analyzing every bit of data so your stable of employees in your Smithian pin factory of communications and content can rapidly grow your follower base, but you’re not going to have any money to pay them. What people tend to forget about sex work industries is that they generate revenue from minute one (that’s exactly what lures people into making what have historically been less than optimal long term personal decisions). By comparison, religious and political aspirants are a bunch of broke boys.

Religion and politics look like they have a lot of money until you consider size of the customer base (most people) and the sectors they influence (nearly all of them).  $14 billion was spent on federal election campaigns in the United States in 2020, the most ever. That sounds like a lot until you realize that a) it’s 2 and 4 year cycles and b) the federal government spends $6 trillion per year. By comparison, $5.5 billion poured through just OnlyFans, just last year. (Do I even need to convince you that new religious and social movements are notoriously short on cash?)

The story of each stage of the internet is the same thing over and over: a group of people couldn’t benefit from scale before but now they can. Social minorities looking to date couldn’t find each other before, now they can. People buying and selling pez dispensors can’t find each other, now they can. People with extreme beliefs were socially ostracized now they can find and reaffirm each other. People selling content to niche audiences used to have to find their customers through large media companies now they can do it directly. Bernie Sanders and Donald Trump both had disproportionate impact on American politics in part because they leverage the internet to disintermediate their ostenisble political parties. That’s the internet bringing scale to parts of the American electorate previously too distant from the median voter.

Power and ambition be damned, however, aspirant leaders are still not going to be able to build what two people selling naughty pictures in Florida were able to do because most people don’t want to pay for politics. Just ask every newspaper in the country struggling to stay afloat. We’re entering a new age of scale in the fake relationships being sold to us, but it will only be for the kinds of relationships we actually want. That doesn’t mean those will be emotionally nutritious relationships, but choice will remain intact. Portfolios of relationships for a lot of people are going to change, but I suspect its going to look less like Evita Peron and Jim Jones, and a lot more like Taylor Swift and Frito Lay.

Marketing will become more granular, more personal, more intrusive, and more effective. If this fills you with anxiety, I hope you can take some solace knowing its mostly going to happen for the stuff you are willing to pay for, like love, family, and your sense of self-worth. Data-enabled relationship fabrication will grow in market share as artificial intelligence crowds out the classically information driven side of marketing. The uncanny of valley of cringe is a customer relations disaster, a trap whose lines are invisible and always moving. For AI to learn where the boundaries lie is to move them. Which means this decidedly human labor market will grow all the faster. And a blue print for selling naughty content from a Florida couple will find its way to selling you damn near everything else.

Axios Survey of Americans on AI Regulation

Axios just surveyed over 2,000 U.S. adults to find that “Americans rank the importance of regulating AI below government shutdowns, health care, gun reform…” Without pressure from the public to pass new legislation, Congress might do nothing for now, which will lead to the rapid advance of LLM chatbots into life and work.

The participants seem more worried about AI taking jobs than they are excited about AI making life better. There is some concern about misinformation.** So, they don’t think AI will have no impact on society, but they also don’t see enacting regulation as a top priority for government.

At my university, the policy realm I know best, we will probably not be “regulating” AI. We have had task forces talking about it, so it’s not because no one has considered it.

The Axios poll revealed gender gaps in attitudes toward AI. Women said they would be less permissive about kids using AI than men. Also, “Parents in urban areas were far more open to their children using AI than parents in the suburbs or rural areas.” Despite those gaps in what people say, I expect that the gaps in what their children are currently doing with technology are smaller. Experimental economists are suspicious of self-reported data.

**Our results did not change much when we ran the exact same prompts through GPT-4. A version of my paper on AI errors that I blogged about before is up on SSRN, but a new manuscript incorporating GPT-4 is under review: Buchanan, Joy, Stephen Hill, and Olga Shapoval (2023). “ChatGPT Hallucinates Nonexistent Citations: Evidence from Economics”. Working Paper.