50% Endowment Returns Driven by Private Equity Investments: How Rich Universities Get Richer (But You Can, Too)

A recent headline in the Dartmouth student newspaper reads, “Dartmouth’s endowment posts 46.5% year-over-year returns, prompting additional spending on students”.  That seems like really great investing performance. But the sub-headline dismisses it as less-than-stellar, by comparison: “The endowment outpaced the stock market, but fell short when compared to other elite universities that have announced their endowment returns.” After all, fellow Ivy League university Brown notched a 50% return for fiscal 2021, which in turn was surpassed by  Duke University at 55.9% and Washington University in St. Louis at 65%. The Harvard endowment fund managers are a bit on the defensive for  gaining “only” 34% on the year.

The stock market has done well in the past year, but nothing like these results. What is the secret sauce here? Well, it starts with having money already, lots of it. That enables the endowment managers to participate in more esoteric investments. This is the land of “alternative investments”:

Conventional categories include stocks, bonds, and cash. Alternative investments include private equity or venture capital, hedge funds, managed futures, art and antiques, commodities, and derivatives contracts. Real estate is also often classified as an alternative investment.

It takes really big bucks to buy into some of these ventures, and it also takes a large  professional endowment fund staff to choose and monitor these sophisticated vehicles. Inside Higher Ed’s Emma Whitford notes:

Endowments valued at more than $1 billion, of which there are relatively few, are more likely to invest in alternative asset classes like venture capital and private equity, recent data from the National Association of College and University Business Officers showed.

“Where you’re going to see higher performance are the institutions with endowments over a billion,” Good said. “If you look at the distribution of where they’re invested, they have a lot more in alternative investments — in private equity, venture capital. And those asset classes did really well. Those classes outperformed the equity market.” 

…Most endowments worth $500 million or less invested a large share of their money in domestic stocks and bonds in fiscal 2020, NACUBO data showed. This is partially because alternative investments have a high start-up threshold that most institutions can’t meet, according to Good.

“You have to have a pretty big endowment to be able to invest in that type of asset class,” he said. “If you have a $50 million endowment, you just don’t have enough cash to be able to buy into those investments, which is why you won’t see big gains from alternatives in those smaller institutions.”

Virginia L. Ma and Kevin A. Simauchi report in The Crimson on Harvard’s Endowment, “Harvard Management Company returned 33.6 percent on its investments for the fiscal year ending in June 2021, skyrocketing the value of the University’s endowment to $53.2 billion, the largest sum in its history and an increase of $11.3 billion from the previous fiscal year.” This 33.6% gain, though, represents underperformance compared to Harvard’s peers; this is rationalized in terms of overall risk-positioning:

However, Harvard’s returns have continually lagged behind its peers in the Ivy League, a trend that appeared to continue this past fiscal year. Of the schools that have announced their endowment returns, Dartmouth College reported 47 percent returns while the University of Pennsylvania posted 41 percent returns.

Narvekar acknowledged the “opportunity cost of taking lower risk” in Harvard’s investments compared to the University’s peer schools.

“Over the last decade, HMC has taken lower risk than many of our peers and establishing the right risk tolerance level for the University in the years ahead is an essential stewardship responsibility,” Narvekar wrote.

In 2018, HMC formed a risk tolerance group in order to assess how the endowment could take on more risk while balancing Harvard’s financial positioning and need for budgetary stability. Under Narvekar’s leadership, HMC has dramatically reduced its assets in natural resources, real estate markets, and public equity, while increasing its exposure to hedge funds and private equity.

There it is again, the magical “hedge funds and private equity”.

Harvard’s fund manager went on to warn that the astronomical returns of the past year were something of an anomaly:

At the close of his message, Narvekar cautioned that despite the year’s success, Harvard’s endowment should not be expected to gain such strong returns annually.  “There will inevitably be negative years, hence the importance of understanding risk tolerance.”

The following chart illustrates, at least in Harvard’s case, how extraordinary the past year has been:

Source:  Justin Y. Ye

The fiscal year of these funds typically runs September to September, so it’s worth recalling that back in September of 2020 we were still largely cowering in our homes, waiting for vaccines to arrive. The equity markets were still down in September of 2020, whereas a year later the tsunami of federal and Fed largesse had lifted all equity boats to the sky. So, it is not realistic to expect another year of 50% returns.

Final issue: can the little guy pick up at least a few crumbs under the table of this private equity feast? In most cases, you have to be an “accredited investor” (income over $200,000, or net worth outside of home at least $1 million) to start to play in that game. From Pitchbook:

Private equity (PE) and venture capital (VC) are two major subsets of a much larger, complex part of the financial landscape known as the private markets…The private markets control over a quarter of the US economy by amount of capital and 98% by number of companies….PE and VC firms both raise pools of capital from accredited investors known as limited partners (LPs), and they both do so in order to invest in privately owned companies. Their goals are the same: to increase the value of the businesses they invest in and then sell them—or their equity stake (aka ownership) in them—for a profit.

Venture capital (VC) is perhaps the more attractive, heroic side of this investing complex:

Venture capital investment firms fund and mentor startups. These young, often tech-focused companies are growing rapidly and VC firms will provide funding in exchange for a minority stake of equity—less than 50% ownership—in those businesses.

Some examples of VC-backed enterprises include Elon Musk’s SpaceX, and Google-associated self-driving venture WayMo.

Venture capital takes a big chance on whether some nascent technology will succeed (in the fact of competition) many years down the road, which has the potential to make the world a better place for us all. Private equity, on the other hand, tends to be somewhat more prosaic, predictable, and sometimes brutal. Here is putting it nicely:

Private equity investment firms often take a majority stake—50% ownership or more—in mature companies operating in traditional industries. PE firms usually invest in established businesses that are deteriorating because of inefficiencies. The assumption is that once those inefficiencies are corrected, the businesses could become profitable.

In practice, this often entails taking control of a company via a leveraged buyout which saddles the new firm with heavy debt, firing lots of employees, improving some strategy or operations of the firm, and sometimes breaking it up and selling off the pieces. This was the fate of several medium-sized oil companies that got in the cross-hairs of corporate raider T. Boone Pickens.  “Chainsaw Al” Dunlop also became famous for this sort of “restructuring” or “creative destruction”.

Private equity activities can be very lucrative. But again, is there any way for you, the little guy, to get a piece of this action? Well, kind of. There are publicly traded companies who do this leveraged buyout stuff, and you can buy shares in these companies, and share in the fruits of their pruning of corporate deadwood. Some names are: Kohlberg Kravis Roberts (KKR), The Carlyle Group (CG), and The Blackstone Group (BX). The share prices of all these firms have more than doubled in the past year (100+ % return). If you had had the guts to plow all your savings into any one of these private equity firms a year ago, you would have had the glory of beating out all those university endowment funds with their piddling 50% returns.
Dry turkey and mediocre side dishes are optimal

The Take Economy demands not just that you distinguish yourself with opinions that deviate from the median person, but that the manner in which your opinion deviates is immediately distinguishable from everyone else who is similarly deviating. This leaves us with a tendency to focus on what we don’t like – enjoying something is further evidence of the monoculture, while hate comes in a million shades of beige.

I bring this up because hating Thanksgiving foods, particularly turkey, oven-baked turkey, has been in vogue for years, and I’m sure stuffing is next. Everything is too dry, too bland, yada yada yada. It’s a boring take most often made by boring people. Not that such things usually matter to me, but in this case it does because Thanksgiving as a meal is not an epicurean holiday, it’s an attempt to solve a coordination game across families, friends, and geographies. When solving a coordination problem with so many players, with preferences and cost-constraints that make broadly amenable large-scale get-togethers increasingly difficult. Between navigating travel costs, sleeping arrangements, and the inevitable negative political externalities that some jackass in your family is going to pollute the familial air with, the last thing you have the resources to cope with is culinary coordination. So what do we do? We come up with a pseudo-national, heavily regional menu that we coordinate on, a$1.99 per pound Schelling point that’s a steal at thrice the price.

The turkey’s too dry? Drown it in gravy. The stuffing is too bland? Your aunt has hot sauce in her purse. Your cousin is explaining the vagaries of 18th century 2nd amendment judicial rulings? There’s a bottle of brown liquor quietly being shared on the porch this very minute that you can partake in for the price of nothing more than a pleading glance and keeping your politics to your self.

The food isn’t the point, but if you’re still feeling the pain of a sub-optimal meal, you can order Chinese with us later, and I’ll happily explain to you why you’re not just ordering the wrong dishes, you’re ordering off the wrong menu. Because I got food takes, just not when the meal isn’t about the food.

Word Golf is a new online game

If you like Scrabble or Family Feud, then you might enjoy playing Word Golf. You can get started for free immediately by going to word.golf

You play by thinking of word associations to click from one concept to another. The challenge will get you thinking. Every game only takes about one minute, and there are simple instructions on the website to get you going right away. Unlike chess, you can do this for fun even without any time commitment.

Like Mike and Jeremy before me this week, I am writing about something I saw at the Emergent Ventures conference. It was an inspiring type of event. I met the young creator of Word Golf and was inspired by his vision for a new intellectual sport.

The game is built from data on how often words appear together on the internet. That’s why I compare it to the TV guessing game show Family Feud. You are not just thinking of synonyms to jump from one word to another. The challenge is to think of what words other people typically use in the same online article.

Word Golf is probably a better use of time than Candy Crush or Solitaire. (I played a lot of computer FreeCell at one point in my life but not anymore.)

Compulsory Schooling by Gender & Age

This weekend I’ll be at the Southern Economic Association Conference in Houston Texas. I’m organizing and chairing a session called Education Policy Impacts by Sex (you should come by and see me if you will be there too!).

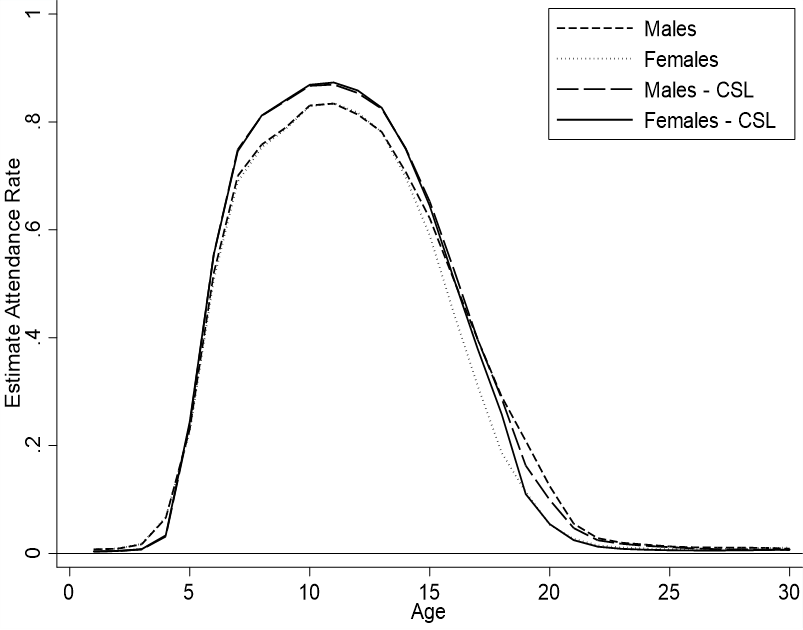
Personally, I will be presenting on the impact of compulsory school attendance laws on attendance. Today I just want to share and discuss a single graph that’s not my presentation.

Prior to my research, there was already a canon of existing literature on compulsory attendance legislation (CSL) and I’ve previously written on this blog about it (attendance, CSL, and differences by sex). However, the literature had some limitations. Authors examined smaller samples, ignored gender, or ignored different effects by age.

I examine full-count IPUMS data from the 1850-1910 US censuses of whites in order to investigate the so-far-omitted margins mentioned above. Here are some conclusions:

Prior to CSL:

  • Males and females attended school at similar rates until the age of 14.
  • After 14, women stopped attending school as much as men.
    • By the age of 18, the attendance gender gap was 10 percentage points.

After CSL

  • Male and female attendance increased from the ages of 6 to 14
  • Women began attending school more than prior to CSL until about age 18.
  • After the age of 18, women experienced no greater attendance than previously.
  • But, both sexes attended school less than prior to CSL for ages 5 and younger.
  • Men began attending school less after the age of 17.
  • CSL increased lifetime attendance for both males and females

Overall, examining the impact of CSL across many ages allows us to see when and not just whether people attended more school. Previous authors would say something like “CSL increased total years of school by about 5% on average”. For men, almost all of those gains were between the ages of 6 & 16. But women experienced greater attendance from ages 6 to 18.

Additionally, examining the data by age reveals that there was some intertemporal substitution. Once it became legally mandatory for children to attend school between the ages of 6 & 14, parents began sending their younger children to school at lower rates. Indeed – why invest in education for two or three early years of life if you’ll just have to send your children to school for another eight years anyway. Older boys dropped out of school at higher rates after CSL too. Essentially, the above figure became compressed horizontally. People ‘put in their time’, but then reduced investments at non-mandatory ages.

This reveals a shortcoming of the current literature, which focuses mostly on 14 year olds. By focusing on a popular age of attendance that was also compulsory, previous authors have missed the compensating fall in attendance at other ages. Granted, the life-time effect is still positive – but it’s attenuated by a richer picture. The picture reveals that individuals were not attending school by accident. Students or their parents had in mind an amount of educational investment for which they were aiming. When children were forced to attend school at particular ages, the attendance for other ages declined.

Inflation: Get Concrete, Get Specific

The recent debate over US inflation seems to be full of mood affiliation on both sides, where people start with a mood (“panic” or “don’t worry”) and then look for facts to fit the mood.

My natural temperament is “don’t worry” and that is what I’ve generally thought about inflation, but the latest number of 6.2% inflation over the last year is a bit concerning, and makes me glad the the Fed has announced they plan to taper off of new asset purchases. But overall I think people are still talking past each other, and I wish more people would answer these questions:

What will CPI inflation be over the next 12 months?

What specifically should the Fed do differently, if anything? How quickly should they taper and raise rates?

If you are currently thinking “panic” or “don’t worry”, what data could come in that would change your mind?

I’ll start with my answers, informed more by my gut than by quantitative models: my guess for inflation over the next year is 4-5%, the Fed has things about right but I’d say “tighten faster” rather than “tighten slower” if I had to pick. I expect inflation to slow noticeably in the spring as the economy transitions from the unusual boom in demand for goods back to demand for services after Christmas and the Delta wave, as more people get back to work and supply bottlenecks have time to work themselves out. I would start to get more seriously concerned if we see no slowing by June, or if market-based measures of inflation or NGDP projections start to move substantially (2pp) higher.

To the extent that I’ve been on the wrong side of this, I blame the cognitive bias I seem to fall prey to most often- mistaking reversed stupidity for intelligence. Just because lots of people make obviously incorrect predictions of hyperinflation doesn’t mean that inflation will be low.

No, 6.2% inflation per year is not in the same universe as hyperinflation (50% inflation per month)

*The usual disclaimer applies- my affiliation with the Fed gives me zero insider information about or influence over monetary policy and I don’t speak for them.

I’m Excited about a New World’s Fair

Everyone who attended the recent Emergent Ventures Unconference is excited. Craig Palsson is excited about the primal branding of the unconference. My co-blogger Mike Makowsky is excited about Plascrete (I was too! We listened to that pitch simultaneously).

I was most excited about the New World’s Fair. This is Cameron Weise’s project, for which he won an EV grant (see all the winners). I have always been interested in the history of World’s Fairs (though probably not as much as my wife). And they still exist, in a sense. There are still World Expos every few years, but as Cameron will tell you, these have mostly turned into “nation branding” exercises, promoting the host nation itself and whatever other countries set up their own exhibits.

But today, World Expos are not about promoting science, technology, and the future, as many World’s Fairs of the past did. And aren’t there already technological conferences, such as the Consumer Electronics Show (now just CES)? Yes, there are. And these are great. But they aren’t serving the same role as World’s Fairs used too.

This is the gap that Cameron Wiese is stepping into. I don’t know exactly what it will look like (he has lots of ideas!), nor exactly when it will happen. But I will be following his project closely, and you should too.

In the conclusion to his e-book The Great Stagnation, Tyler Cowen presents a solution to the stagnation: “Raise the social status of scientists.” I think a New World’s Fair would go a long way towards do this.

Eliminate the National Debt: Mint Trillion-Dollar Platinum Coins

The American patriots funded their Revolution largely by printing paper money, since they had no gold with which to buy supplies or pay troops. That got the immediate job done, but ended in disastrous inflation. Thus, when the U.S. Constitution was drafted a few years later, the states were explicitly forbidden to print paper money, and the federal government was deliberately not granted that authority.

Currently, printing of paper money is done by the Federal Reserve, which is essential a private bank on steroids, though under a certain amount of government oversight. What the U.S. Treasury (a part of the executive branch of the federal government) can do to cover its expenditures is to collect taxes, issue bonds and other debt, and also mint metal coins. 

These coins are considered legal tender. The size and value of most of these coins is spelled out in31 U.S. Code § 5112 – Denominations, specifications, and design of coins . For instance, gold coins can be struck in certain denominations between $5 and $50. Sharp legal eyes have noticed, however, that the value of platinum coins is left unspecified. The definition of such coins is left up to the discretion of the Treasury Secretary. 31 U.S.C. 5112(k) reads:

The Secretary may mint and issue bullion and proof platinum coins in accordance with such specifications, designs, varieties, quantities, denominations, and inscriptions as the Secretary, in the Secretary’s discretion, may prescribe from time to time.

Thus, in theory at least,  Treasury Secretary Janet Yellen could authorize the U.S. Mint to stamp 5 platinum coins, each bearing the words “One Trillion Dollars”. She could then (under heavy armed escort) walk these coins over to the Federal Reserve, and exchange them for nearly all of the $5.4 trillion in federal debt held by the Fed. These coins are by definition “legal tender”, which means that any creditor (bond-holder) must accept them to settle the debt represented by the bond.

Poof, the government would have another five trillion dollars to spend as it wished. No more bothering with issuing bonds to fund deficit spending, and no more pesky debt ceiling. This is a proposal which arises every few years, whenever the debt ceiling becomes an issue.

The Mint could even go ahead, pump out a total of 29 such coins, and retire the whole federal debt. No more interest to be paid on the national debt, no more hand-wringing over “can we afford it”. We can afford anything. Build it back better, tear it all down, and build it again even better. Jobs for all! And if people won’t work, send them money anyway. This puts us in a Modern Monetary Theory paradise.

Cooler heads have so far prevailed when the trillion-dollar coin ploy is proposed. Most parties agree it would be a violation of the spirit, if not the letter of the laws and customs of the land for the government to outright mint such quantities of fiat money. Arguably the purchase by the Fed of government debt  effectively amounts to the same thing, since the Fed conjures money out of thin air with which to buy these bonds. (Furthermore, the Fed remits to Treasury the vast majority of the interest that Treasury pays on those bonds, so the Fed purchase of these bonds really is free money for the government). However, the interposition of the overall bond market in the process and having the Fed as a quasi-independent counterparty maintain at least the semblance of traditional government funding via public debt.

Also, as Cullen Roche has pointed out, the trillions of dollars of secure, interest-bearing government debt floating around the financial markets serve a number of very useful purposes to keep those markets lubricated and functioning. Such bonds also provide a seemingly safe place for citizens and pension funds to park their funds. To redeem all these bonds with platinum coins and thus to yank them off the markets and out of millions of brokerage accounts would be a major upset. Not to mention the raging inflation that would surely follow such naked, unconstrained money printing. But this all makes for entertaining financial theater.

What kind of return do we want on our investment?

I had never spoken with someone so enthusiastic about what they could do with trash. A young, slender man from a city in India I was unfamiliar with explained to me how his machine transformed plastic refuse into an economically and environmentally superior substitute for concrete. This sort of techno-optimism fodder for “your daily reason to feel good” clickbait article provokes, but rarely maintains my optimism upon closer inspection. I listened, impressed by the person I was talking to, but unsure what to make of his elevator pitch.

Then he reached into his backpack and handed me a very real block of “Plascrete”. We’ve spent so much of the last 20 years inundated with ideas that were abstract software application propositions at best, and vaporware at worst, it was jarring to hold the physical manifestation of someone’s “big idea”. I spent the rest of the conversation, and a good chunk of my evening at the “unconference” being hosted by Emergent Ventures, thinking about the economic ramifications of Plascrete. What it could mean for developing countries to have a substitute for concrete that is 24 times stronger yet somehow 4 times cheaper – what it would mean for infrastructure and vertical housing construction. What the streets might look like picked clean of plastic bags and refuse. What happens to the lower tail of the wage distribution after the marginal product of trash-picking labor quintuples. How forecasted carbon emissions from developing countries might shift if the expected carbon footprint of construction were massively reduced.

But this post isn’t about Plascrete or the projected impact of any particular innovation. What I’m interested in this moment is the market for private venture capital.

The model of modern venture capital is built around the biggest of wins, those home run investments whose returns compensate for the more than 90% that largely fail. For the strategy to function, of course, means that every investment has to carry the possibility of prodigious returns, in the realm of 10 to 20-times investment, which limits the industries and technological categories under consideration. Tight profit margins are out. Factories, physical capital are out. Anything that might carry an inherent limitation to rapid scaling are out. What’s in are network consumer goods and zero marginal cost (e.g. software) products. So what does that leave out? Explicitly physical goods, such as inputs into shelter or food, things that require upfront investment in equipment where those costs increase with the scale of your output aspirations.

But that’s actually only the beginning of our problems. What about goods with enormous positive externalities, i.e. social benefits, that exist without the possibility of traditional property rights and monetization? Even if a private venture fund is culturally interested in such things, they are constrained by their model – any reduction in potential home run returns from their investment puts the short run solvency of their fund at risk, something unlikely to be tolerated by their investors. These problems are only compounded when considering positive externality generating technologies that are burdened with traditional physical capital needs and historically normal limits to scaling. Even if your product offers 100X social returns, that’s not going to keep the lights on for a series of high risk investments with private returns that top out at 5X.

Innovations whose adoption offers enormous positive externalities are, in theory, exactly why public support for general science exists (whether or not such things should fall within the domain of public funding agencies is a whole different question that I have no immediate interest in addressing). Let me simply say here that these hypothetical products require expertise in delivering a product to market and the capacity to appropriately take on risk. These are not the comparative advantages of large federal science funding agencies. Which leaves us with the dilemma motivating this entire rambling thought exercise. There seems to be an important gap in the market- and government-based institutions for funding innovation.

What I want to consider is the possibility of elevating the status and profile of private venture capital that goes towards profitable, self-sustaining technologies whose returns might only be considered prodigious if we include the broader positive externalities they have on human lives. The kinds of effects whose value may in fact scale exponentially as they diffuse through communities and networks, but will never be internalized into profits via property rights. I want to consider the reconstruction of the risk profile of an entire portfolio to optimize the ability of a fund to support these sorts of innovations in perpetuity. Earning returns sufficient to produce returns sufficient to self-sustain with a minimum of (if any) long run philanthropic subsidy.

Private capital with such a focus would find a niche that modern venture funds are unmotivated to serve and public scientific agencies are ill-equipped to support. Private funds focused on innovations with externally scaling returns would, in my half-baked hypothesis, would take on a two-tier model. The first tier would be composed of small investments scattered across a large number of very small grants (which is essentially the entire model of Emergent Ventures – I’m essentially plagiarizing the model I saw evidence of through two days of conversations with their grant recipients). These grants would predominantly be interested in people. These human lottery tickets would pursue their initial ideas through the proof-of-concept stages. Some would succeed, most will not, but all will benefit from their first connection to the broad international network of technology talent and talent-seekers. The small number who do succeed in producing compelling evidence of technological advancement would then enter the second tier, where large investments would be sought for a prototype and eventual distribution. What’s important to remember is that this remains a private good that must still enter and pass the market test. What distinguishes it is not an inability to economically self-sustain, but rather it’s inability to create profits so grandiose that it can subsidize a portfolio of failed moonshots. It’s prospective profitability need only justify it’s own independent risk of failure. This is not to say the bar is actually lower than traditional venture capital. While the profitability bar is lower, it must exceed a second, in many ways more difficult bar – it must produce a direct and attributable positive externality, be it through health, safety, or environmental channels. Its consumption must improve lives of not just its consumers, but those entirely uninvolved in its production or purchase.

I’m not an expert in venture capital or speculative philanthropy, but after the last week I can’t shake the idea that Michael Kremer was even more right than we realized: more people => more ideas => more economic growth. There are billions lottery tickets lying on the ground all over the developed world. We need to invent newer and better ways of picking more of them up.

Deficits and presidents

Wranglings over spending plans, deficits and public debt increases have been quite intense of late. What is quite surprising, at least at first glance, is that there are so few individuals who are arguing for reducing public spending. Right now, the most “hawkish” policy stance is a slower rate of spending increases. Why the pro-spending tilt of debates?

One could argue that its the pandemic. A crisis is, after all, a natural moment to increase spending. However, that argument is a bit weak now. This position was easily defensible six to twelve months ago, but not today when the economy is starting its recovery. If anything, as recovery is underway, the case for slashing spending levels is stronger than the case for raising them.

So, once again, why the pro-spending tilt? Let me point to the work of James Buchanan and Richard Wagner in Democracy in Deficit. In this work, whose lessons are underappreciated today, Buchanan and Wagner argue that there is an asymmetry in the political returns to fiscal policy. This is known as fiscal illusion. When a deficit occurs, the costs are delayed and thus harder to observe. The benefits are immediate. When a surplus takes place, the benefits are delayed and the costs (i.e. less spending, higher taxes) are immediate.

Second, there’s the far more serious threat of fiscal illusion—that the public’s perception of the true costs and benefits of government expenditures is misconstrued. As long as the costs of taxation are underestimated and that the benefits of public expenditures are overestimated, there’s fiscal illusion. The nature of politics thus creates a strange incentive system where governments reap more electoral rewards from deficits than from surpluses. If you buy Buchanan and Wagner’s explanation, the pro-spending tilt is easy to explain.

However, the empirical evidence for this is somewhat limited. For example, Alberto Alesina in the 1990s, showed that he could not find empirical patterns that confirmed Buchanan and Wagner’s theorizing. But, I have recent work (co-authored with Marcus Shera of George Mason University — a good graduate student of mine) which proposes a simple mechanism by which to observe whether the first condition for a pro-deficit/pro-spending tilt is present.

American presidents are incredibly mindful of their historical reputation. As I argued elsewhere, presidents consider historians as a constituency they want to cater to so as to be remembered as great. If there is a reward from engaging in deficit spending given by historians, this would suggest that presidents have at least some incentives to be fiscally imprudent. Phrased differently, such returns by historians would suggest some divergence between what is fiscally prudent and what is politically beneficial.

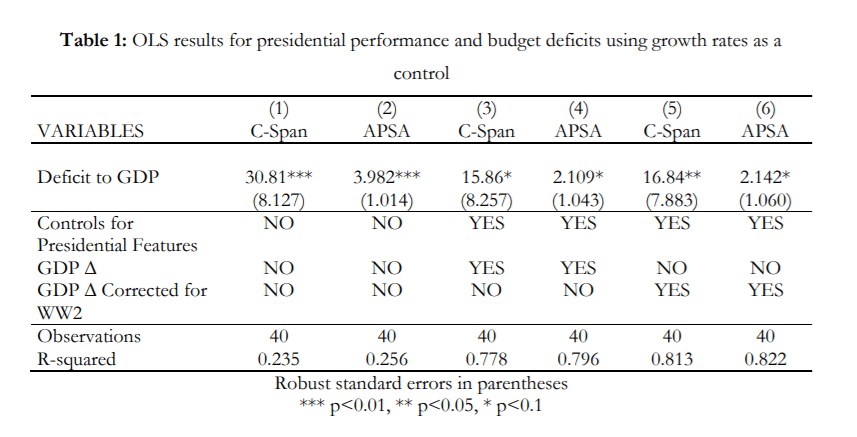
Using the surveys of American presidents produced by C-Span and the American Political Science Association, Marcus and I found that there are strong rewards to engaging in deficit spending. Without any controls for the personal features (e.g. war hero, scandal, intellect) of a president and the features of a presidency (e.g. war, victory in war, economic growth), an extra percentage point of deficit to GDP is associated with a strong positive reward to a president (see table below). Once controls are introduced, the result remains: there are strong rewards from engaging in deficit spending.

Thus, at any time, a president who is mindful of his place in the history books would be tempted to engage in deficit spending. While Marcus and I are somewhat cautious in the paper, I do think that we are presenting a “lower-bound” case for a pro-deficit bias. Indeed, one could think that the hindsight of history would lead to greater punitions for fiscal recklessness. After all, historians are not like voters — their time-horizons for evaluating a presidency are clearly not as short. If that is the case, one should expect that historians should be less likely to reward deficits. And yet, they seem to do so — which is why I argue this is a lower-bound case.

In other words, Joe Biden might simply believe that the extra spending will secure him a place in history books. If other presidents are any indication, he is making a good bet.

Data continues to improve sports performance

Joy: As a Data Analytics teacher, I often think about the applications of machine intelligence to work processes. Samford undergraduate Copeland Petitfils has written the following blog, which is a reminder to me that there are still many potential areas for growth.

Since “Moneyball”, we have seen the growth of analytics throughout sports. However, many teams have stuck to the same old way of playing baseball, like the Braves. This past May, the Braves took a new innovative approach and saw room for growth on their defensive side.

The general manager, Alex Anthopoulos, implemented a radical strategy and improved the defense by using shifts with data analytics. While “Moneyball” looked at the statistics of acquiring cheaper players who had good batting averages and improved the offensive side, the Braves looked at improving the defensive side and the way they shift between pitches to improve their chances of getting a ground ball out. A defensive shift in baseball refers to the infield changing positions from normal to a certain area of the infield based on the pitches and using stat cast to predict where the batter is most likely to hit the ball depending on the type of pitches. Shifting can increase the probability for players to get ground balls out rather than hits.

Statistically, the Braves ranked at the bottom of defensive shifts in the MLB, and Anthopoulos, the general manager, saw this as an opportunity to improve. The Braves started the 2021 season with no shifting at all to shifting on 50.6% of pitches by the end of the year, which was the highest in baseball this year only behind the Dodgers. The shifting ultimately allows the Braves to improve in converting ground balls to out rather than turning into hits. At the start of the season, the Braves converted under 75% of ground balls into outs which ranked middle of the pack in defense. However, since implementing the shift the number jumped to 77%, which was the second-best in baseball. Although these jumps in percentages seem small, they allowed the Braves to field 25 more ground balls into outs rather than hits.

The data analytics the Braves used allowed the players to be put in a better position to succeed, and as the season progressed, they started to get better and better at it. These decisions turned around the Braves’ season, and now they are on their way to the World Series for the first time since 1999 after beating the Dodgers in the NL Championship.

Coda by Joy: That said, guess who failed at data driven decision making? Zillow!

In a statement Tuesday, Chief Executive Rich Barton said Zillow had failed to predict the pace of home-price appreciation accurately, marking an end to a venture the company once said could generate $20 billion a year. Instead, the company said it now plans to cut 25% of its workforce… “We’ve determined the unpredictability in forecasting home prices far exceeds what we anticipated and continuing to scale Zillow Offers would result in too much earnings and balance-sheet volatility,” Mr. Barton said.